
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
WeRide (WRD) Secures Spain Permit And ADAS Launch, Is The Valuation Gap Real?
WeRide (WRD) is back in focus after two separate milestones. The company helped secure Spain’s first national Level 4 autonomous vehicle permit and also saw its WRD 3.0 driver-assistance tech reach mass-market production.
These milestones landed after a tougher run for the stock, with the share price down 40.47% year to date and the 1-year total shareholder return declining 45.68%. As a result, the recent regulatory win in Spain and WRD 3.0 roll-out are arriving as momentum has been fading rather than accelerating.
Scan beyond WeRide and compare it with other autonomous and AI-focused plays using our curated list of 38 robotics and automation stocks.
WeRide now trades at a steep discount to both analyst targets and intrinsic estimates after a sharp slide in the share price. Is that a valuation gap, or a warning that the market’s caution is justified as losses persist?
Most Popular Narrative: 60.3% Undervalued
WeRide’s most followed valuation storyline pegs fair value at $14.09, well above the last close at $5.59, which sets a high bar for what needs to go right.
The dual deployment of L4 robotaxis and L2+ WePilot 3.0 ADAS in mass production vehicles from Chery EXEED and GAC allows data and software to be reused across product lines. This can spread R&D spending over a larger revenue base and potentially support higher group level margins.
See why 6 investors see WeRide as 60% undervalued.
Result: Fair Value of $14.09 (UNDERVALUED)
Still, the WeRide narrative leans heavily on regulatory momentum and high vehicle utilization, so slower permit approvals or weaker rider demand could quickly challenge those assumptions.
Find out about the key risks to this WeRide narrative.
Another View On WeRide’s Valuation
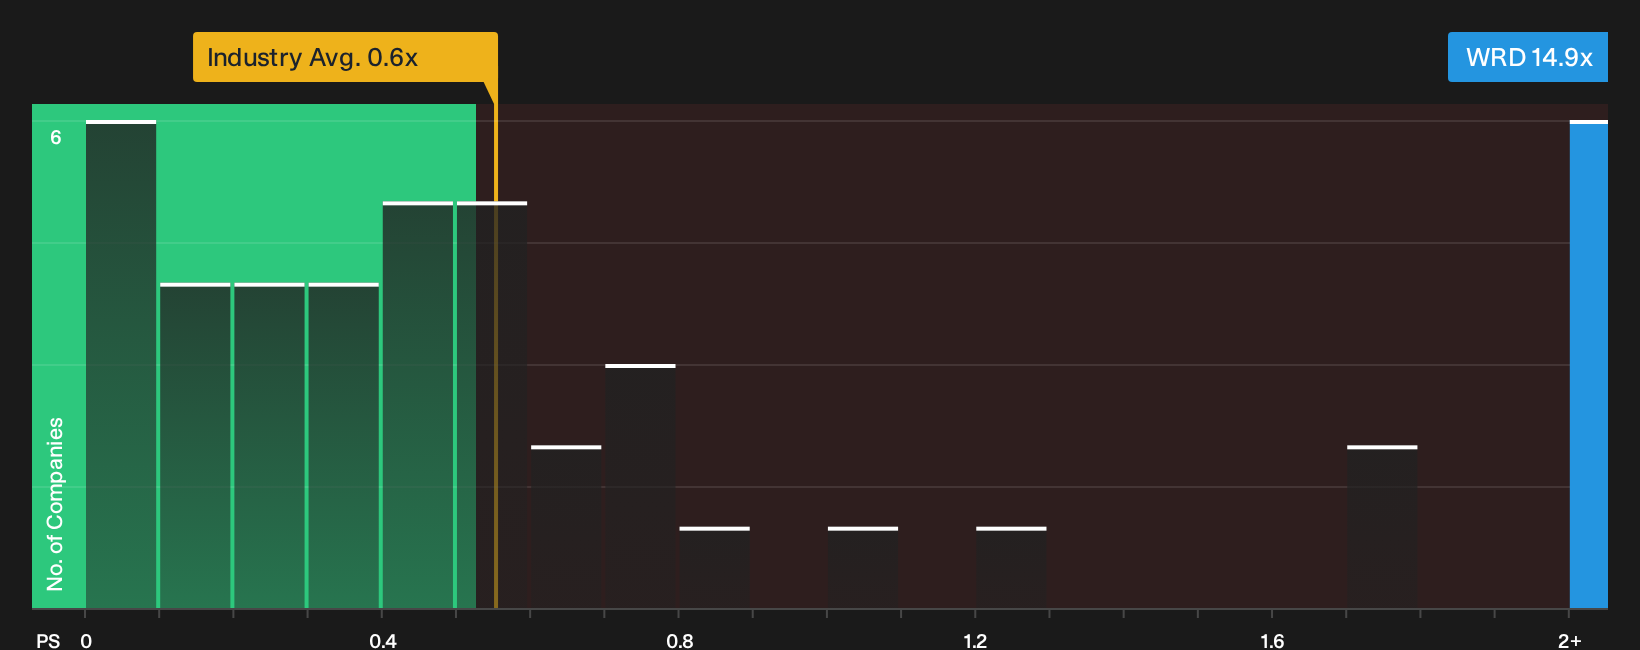
The earlier fair value story for WeRide leans on analyst targets and long term earnings assumptions. A different lens comes from the revenue multiple. The stock trades on a P/S of 14.9x against an industry average of 0.6x and a fair ratio of 4.4x, which points to a rich tag rather than a clear bargain. Is that a premium investors are comfortable underwriting while the business is still loss making?
Sense check that pricing gap against the detailed numbers in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on WeRide is split, with valuation signals pulling in different directions, so it makes sense to move quickly and inspect the raw metrics yourself. If you want to see what the optimistic camp is focusing on, start by reviewing its 2 key rewards.
Looking for more WeRide-sized investment ideas?
If you want broader context around WeRide and do not want to miss other potential setups, use the Simply Wall Street Screener to surface new ideas fast.
- Target steadier compounding opportunities by scanning a 11 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Hunt for mispriced potential by reviewing a 16 high quality undiscovered gems with solid fundamentals that have not attracted broad attention yet.
- Anchor your watchlist with sturdier cash generators by focusing on a 6 dividend fortresses offering higher yields backed by robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com