
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is DoD Software Approvals Altering The Investment Case For Parsons (PSN)?
- Parsons Corporation recently secured nine "Awardable" designations for its digital solutions across the U.S. Department of Defense's Platform One and Tradewinds marketplaces, reflecting formal recognition of its mission-focused software offerings for rapid deployment to warfighters.
- This cluster of award-ready approvals strengthens Parsons' position inside key Pentagon procurement channels, with the potential to streamline contract awards and deepen its role in defense digital modernization programs.
- We will now examine how Parsons' investment narrative could be influenced by these multiple DoD awardable designations for its digital platforms.
Parsons Investment Narrative Recap
To own Parsons, you need to believe in a long runway for defense and critical infrastructure work, plus a gradual mix shift toward higher margin digital solutions. The nine new Department of Defense awardable designations speak directly to that belief, because they validate Parsons’ software offerings and could support its Federal Solutions segment after the earlier confidential contract loss.
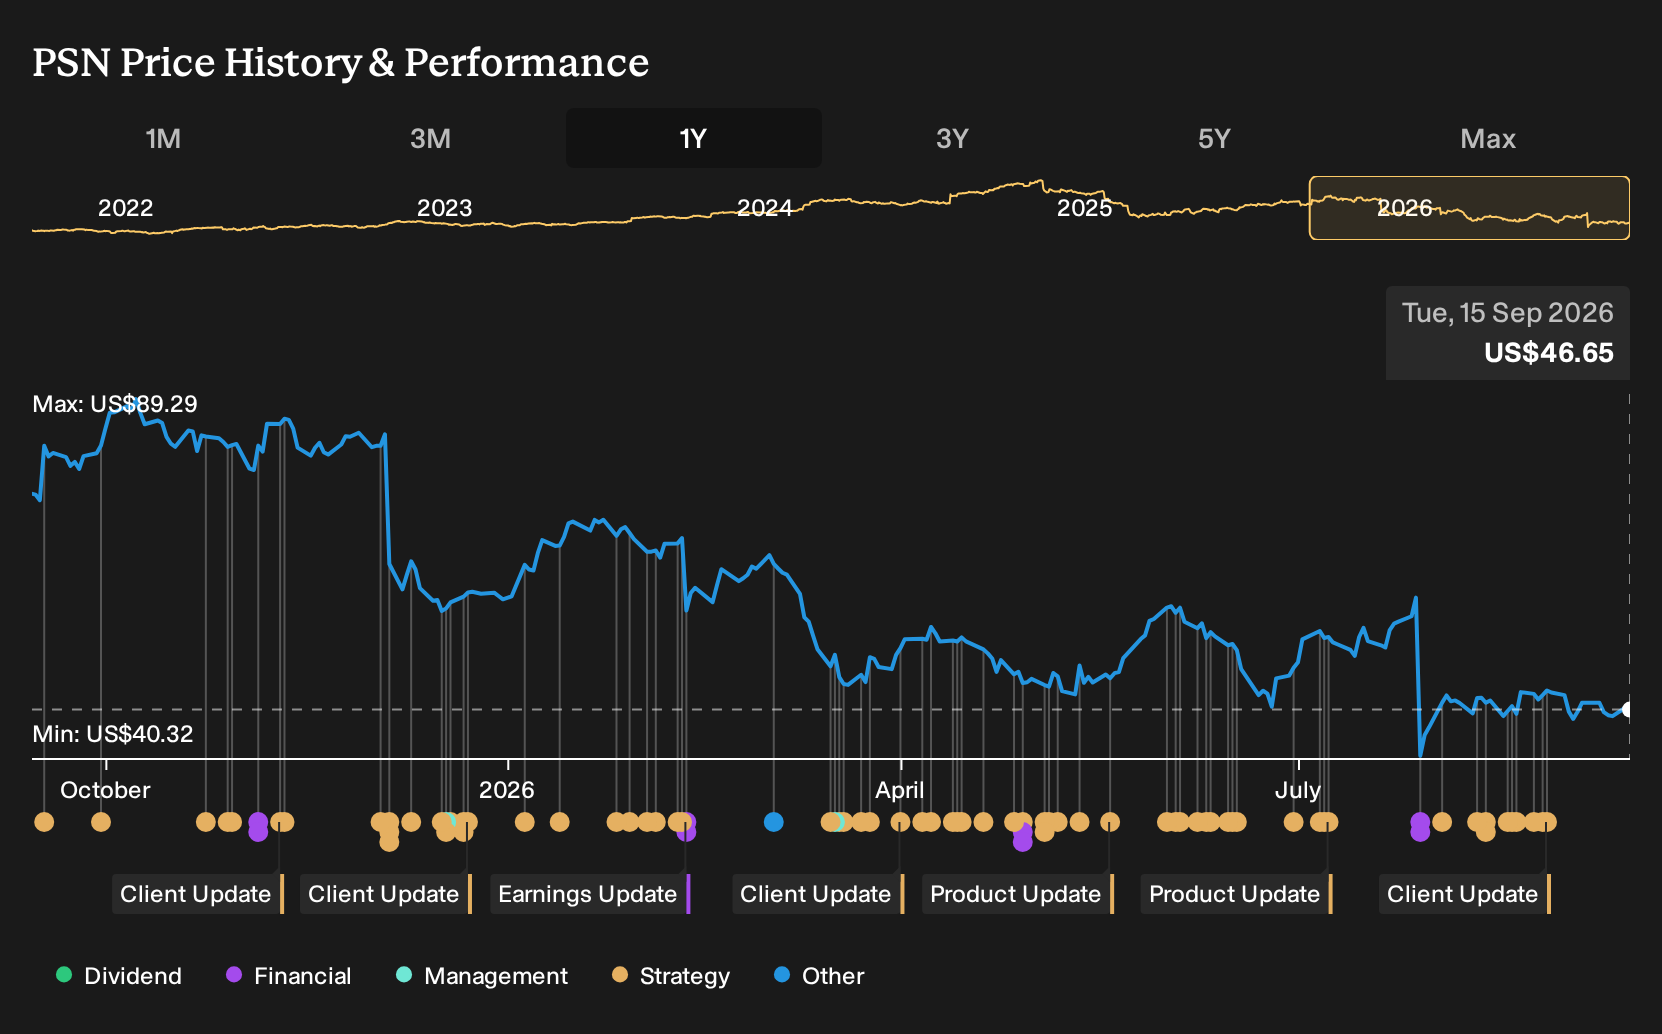
In the short term, the key swing factor is whether management can backfill that revenue gap and stabilize margins that currently sit at 2.5%, below last year’s 3.7%. The biggest risk remains heavy dependence on U.S. government budgets and contract timing, which can amplify earnings volatility, especially with a leveraged balance sheet and a share price that has already fallen 38% over the past year.
The clearest near term operational focal point related to this news is the upcoming Jefferies Global Industrials Conference presentation on 9 September 2026. Parsons’ CEO Carey Smith and CFO Matt Ofilos will have a platform to give investors more detail on how these awardable designations could affect backlog quality, win rates and the mix between traditional engineering work and software heavy federal programs.
For anyone tracking catalysts, that session matters because management can address key concerns in one setting. Investors are likely to listen closely for commentary on contract pipeline health, integration progress from past acquisitions such as CTI, and how the firm is thinking about debt, given high leverage alongside forecasts for faster earnings growth than revenue.
Parsons' current analyst framework points to US$7.2b in revenue and US$407.1m in earnings by 2029. That path assumes revenue advances at 4.7% per year and earnings rise by about 2.6x from US$157.4m today.
Uncover why Parsons' fair value indicates a 25% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a very different angle, focus on Parsons’ digital push. The most optimistic analysts leaned hard into this before the awardable news, baking in revenue of about US$7.7b and earnings of roughly US$459.4m by 2029. That is a far brighter story than consensus, and these fresh DoD designations may push opinions even further apart.
Explore 3 other Parsons fair value estimates, including one that suggests as much as 154% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Parsons research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Parsons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Parsons' overall financial health at a glance.
Looking for more investment ideas beyond Parsons?
Once you have a view on Parsons, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener is built for exactly that kind of targeted hunting, so you can filter by quality, balance sheet strength or income potential rather than scrolling through tickers at random.
- If capital preservation is high on your list, you could start with stocks that combine resilience with measured risk profiles by reviewing 11 resilient stocks with low risk scores.
- If you are more interested in companies that pair solid fundamentals with room to rerate, you could scan a curated set of quality businesses trading below their estimated worth through 34 high quality undervalued stocks.
- If portfolio income is a priority, you could focus on firms aiming to offer robust cash payouts by checking out a hand picked group of high yield candidates via 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com