
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NWPX Infrastructure (NWPX) Pullback Puts Its Water Infrastructure Valuation Narrative To The Test
NWPX Infrastructure (NWPX) has drawn investor attention after a sharp pullback, with the stock down about 13% over the past month and 27% over the past 3 months despite strong longer term returns.
That pullback comes after a strong run over the year, with NWPX Infrastructure posting a year-to-date share price return of 60.59% and a 1-year total shareholder return of 94.73%. However, the recent 30-day share price decline of 12.86% and 90-day drop of 27.12% suggest momentum has cooled as investors reassess the balance between growth potential and risk at a latest share price of $101.22.
Scan how NWPX Infrastructure compares to other water and infrastructure plays by running through the hand picked 38 power grid technology and infrastructure stocks in the same space.
NWPX Infrastructure now trades near $101 after a steep reset, while its longer term chart still shows very strong gains. Does that recent slide now tilt the risk reward in favour of fresh buyers, or not?
Most Popular Narrative: 7% Undervalued
With NWPX Infrastructure closing at $101.22 against a widely followed fair value marker of about $109, the current reset raises questions about whether recent price weakness has gone further than the underlying fundamentals.
The company's record-setting performance in Q2 2025, improving free cash flow, robust backlog (up 20% sequentially to $348M), and consistently healthy demand in both Water Transmission Systems (WTS) and Precast segments indicate strong underlying business momentum. These factors may support higher revenue and earnings in coming years.
The company is benefitting from long-term secular trends such as aging U.S. water infrastructure and increasing federal and state infrastructure spending (including IIJA-funded projects). These dynamics are likely to provide a steady and reliable pipeline of demand, which could positively influence revenue and future growth visibility.
See why 2 investors see NWPX Infrastructure as 7% undervalued.
Result: Fair Value of $109.33 (UNDERVALUED)
Still, that 7% discount to fair value can unwind quickly if government funded water projects slow or if substitute materials start to eat into NWPX Infrastructure's pipeline orders.
Find out about the key risks to this NWPX Infrastructure narrative.
Another View: SWS DCF Flags Richer Pricing
While the popular NWPX Infrastructure narrative leans on a fair value of about $109 based on analyst targets and earnings assumptions, the SWS DCF model points in the opposite direction. On that cash flow lens, the shares at $101.22 sit above an estimated value of $87.46, which frames the stock as overvalued rather than cheap. That split in outcomes leaves a simple question for investors: Which set of assumptions feels more realistic for the next decade of cash generation?
Look into how the SWS DCF model arrives at its fair value.
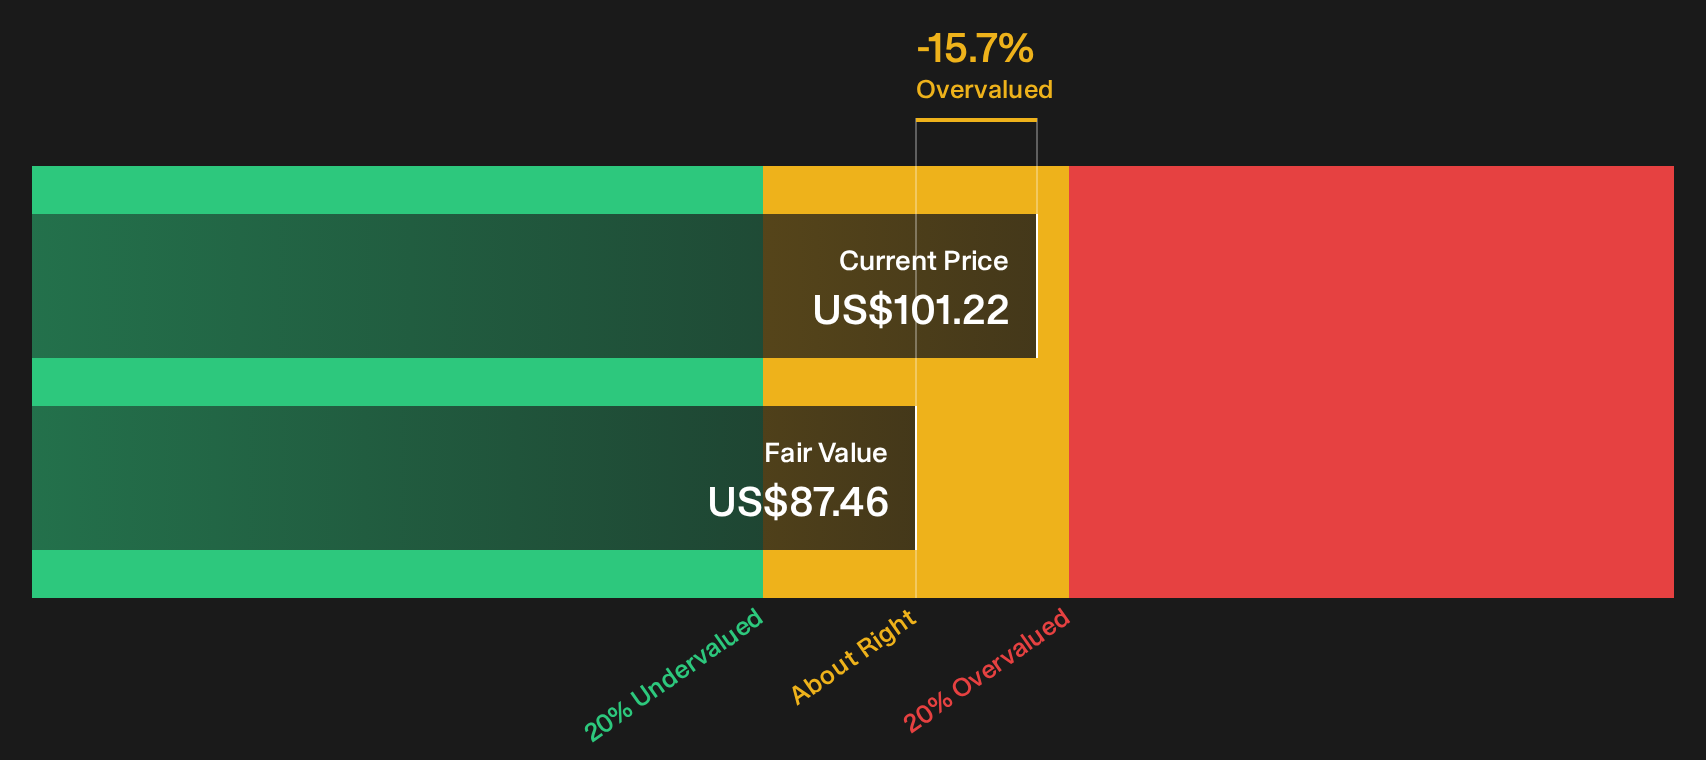
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NWPX Infrastructure for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on NWPX Infrastructure so far. If you want to move quickly and form your own stance, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond NWPX Infrastructure?
If NWPX Infrastructure has sharpened your focus on quality, do not stop here. Use targeted screens to surface other potential opportunities before the crowd reaches them.
- Target potential mispricings by scanning companies that screen as quality yet out of favor through the 34 high quality undervalued stocks.
- Strengthen the income side of your portfolio by focusing on reliable payers using the 6 dividend fortresses.
- Prioritise resilience by filtering for businesses with prudent funding and healthy metrics via the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com