
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Monte Dei Paschi Stock Green Bond Sale
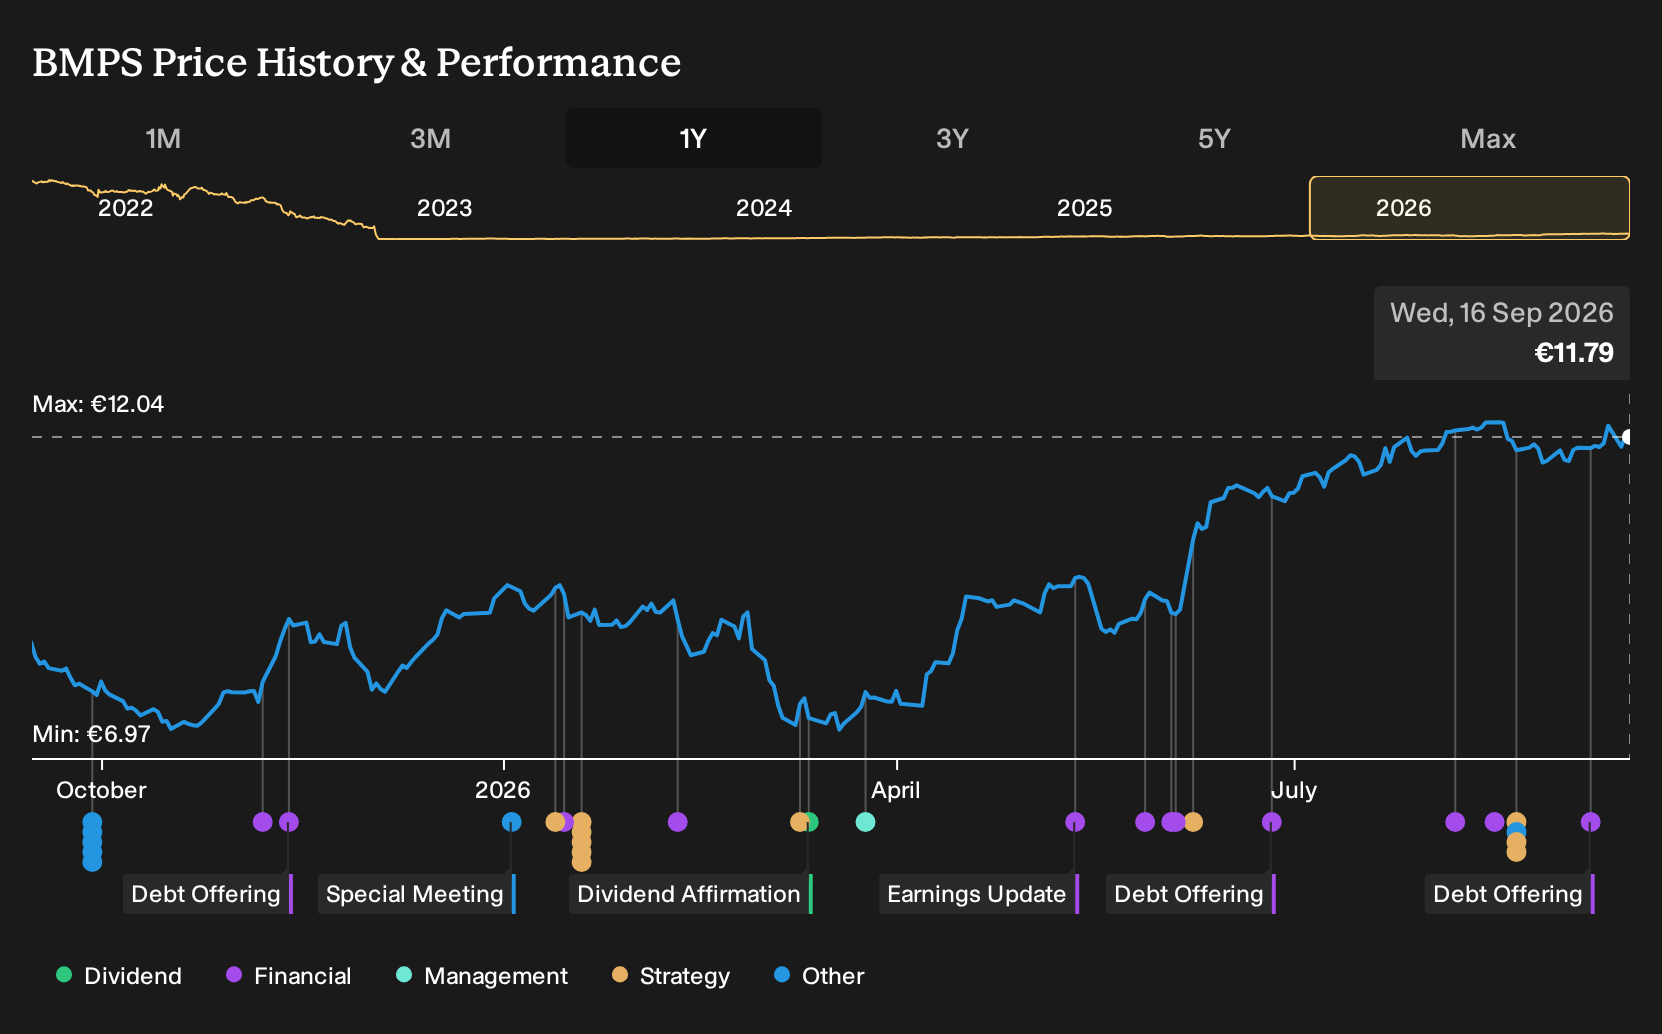
- Banca Monte dei Paschi di Siena has completed a €497.545 million placement of callable, subordinated, fixed to floating rate green notes due March 2037, issued under Regulation S at 99.509% of the €500 million principal.
- The green, subordinated, variable rate structure indicates that Banca Monte dei Paschi di Siena is targeting capital efficiency and investor demand for climate-labelled bank debt, while accepting higher funding complexity and long-dated obligations.
- This article will examine how Banca Monte dei Paschi di Siena's investment narrative intersects with this long dated subordinated green bond issuance.
Scan how Banca Monte dei Paschi di Siena’s latest green, subordinated bond fits into a wider funding trend by reviewing a curated list of solid balance sheet and fundamentals (195 results).
Banca Monte dei Paschi di Siena Investment Narrative Recap
To own Banca Monte dei Paschi di Siena, you have to believe the bank can turn current earnings strength and a 52.3% net margin into something resilient as rates ease and digital competitors keep chipping away at fees. The recent subordinated green bond looks more like balance sheet housekeeping than a major shift in the near term operating story.
The key near term swing factor remains execution on profitability while keeping asset quality in check, given a 2.6% bad loan ratio and an 81% allowance. The biggest risk is that higher costs, regulatory pressure and slower loan demand squeeze returns, while shareholder dilution and a stretched dividend policy limit flexibility if conditions tighten.
The new €500 million fixed to floating subordinated green notes sit against a backdrop of strong capital, with a reported CET1 ratio of 19.6%. That cushion already gives Banca Monte dei Paschi di Siena room to absorb shocks, support lending and keep optionality on payouts and M&A. The extra tier style funding mainly fine tunes that profile.
Because the bank has no other fresh operational announcements tied directly to this deal, the relevance circles back to catalysts already flagged by analysts. Strong capital and long dated subordinated funding can support plans around potential consolidation, technology investment and wealth management growth. It also interacts with the risk that a high dividend promise proves hard to sustain if profitability or asset quality slip.
Banca Monte dei Paschi di Siena's current analyst story points to revenues of €9.9 billion and earnings of €3.2 billion by 2029, based on forecast annual revenue growth of 20.7% and an earnings increase of about €0.3 billion from €2.9 billion today.
Uncover why Banca Monte dei Paschi di Siena's fair value indicates that Banca Monte dei Paschi di Siena is trading in line with its current price.
Exploring Other Perspectives
One alternate view on Banca Monte dei Paschi di Siena focuses on higher long term credit risk from faster retail lending, especially mortgages, rather than on capital strength. In this context, the most cautious analysts were working with around €9.3b of revenue and €3.0b of earnings by 2029 before this new green bond. Those figures point to a more fragile earnings path than the consensus, so this fresh subordinated funding could nudge expectations in either direction once analysts revisit their models.
Explore 4 other Banca Monte dei Paschi di Siena fair value estimates, including one that suggests as much as 22% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Banca Monte dei Paschi di Siena research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Banca Monte dei Paschi di Siena. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banca Monte dei Paschi di Siena's overall financial health at a glance.
Looking For More Investment Ideas Beyond Banca Monte dei Paschi di Siena?
Once you have a view on Banca Monte dei Paschi di Siena, it can help to compare that thesis with other businesses that have different balance sheet profiles, income mixes and risk levels. The Simply Wall St Screener is built for exactly that kind of side by side work, so you can pressure test your thinking rather than rely on a single story.
- If you want potential mispricings with quality fundamentals, start by scanning a 192 high quality undervalued stocks that already clears some key balance sheet and cash flow checks.
- For investors who care most about resilience and capital strength, filter for companies with conservative funding and cleaner leverage using a targeted 103 resilient stocks with low risk scores.
- If you prefer opportunities that fly under the radar, broaden your watchlist with a focused 618 high quality undiscovered gems that highlights businesses with solid fundamentals but lighter coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com