
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Saudi AI Lending Deal Could Be A Game Changer For Iron Mountain Stock (IRM)
- Iron Mountain announced partnerships with Saudi Arabia’s Social Development Bank and the Opéra national de Paris to deploy its InSight DXP platform, digitize document heavy financing workflows, and preserve visual archives through on site cataloguing and digitization.
- The twin focus on AI powered document processing for SME lending and cultural heritage digitization highlights how Iron Mountain is pushing its digital solutions into both regulated financial workflows and long dated archival content.
- We will now examine how Iron Mountain's investment narrative could be reshaped by its AI driven document processing push with Saudi Arabia.
Scan 60 AI infrastructure stocks to see how other data and document infrastructure plays are quietly building the rails behind AI heavy workflows, such as Iron Mountain's Saudi lending and Paris archive projects.
Iron Mountain Investment Narrative Recap
For Iron Mountain, the core belief is that its old world storage roots can fund and support a higher growth tilt toward data centers and digital solutions. The Saudi Social Development Bank deal fits that story because it shows real world adoption of InSight DXP in a regulated, document heavy setting rather than just a pilot or proof of concept.
The main near term swing factor still sits in execution on capital intensive projects, from data centers to AI platforms, against a backdrop of high leverage and interest costs that are not well covered by earnings. This Saudi project alone does not change that risk balance in a material way, but it does add evidence that the digital thesis is playing out in live workflows.
The Saudi SME lending deployment is the cleanest bridge between Iron Mountain’s AI narrative and its financial catalysts. InSight DXP is being used on real underwriting processes, with automation, validation against lending rules, and human review only for exceptions. That plays directly into management’s focus on digital workflow automation and higher margin recurring services.
For you as an investor, the useful question is how repeatable this type of project is across the 240,000 plus customer base and beyond. If execution goes to plan and the initial Saudi rollout expands to more products and document types, it could feed the digital segment that analysts already see as a key earnings driver, while still sitting on top of the existing records management relationships.
Iron Mountain's current analyst narrative points to revenues of US$9.9b and earnings of US$764.5m by 2029, anchored on 9.2% yearly revenue growth and an earnings increase of about US$345.8m from US$418.7m today.
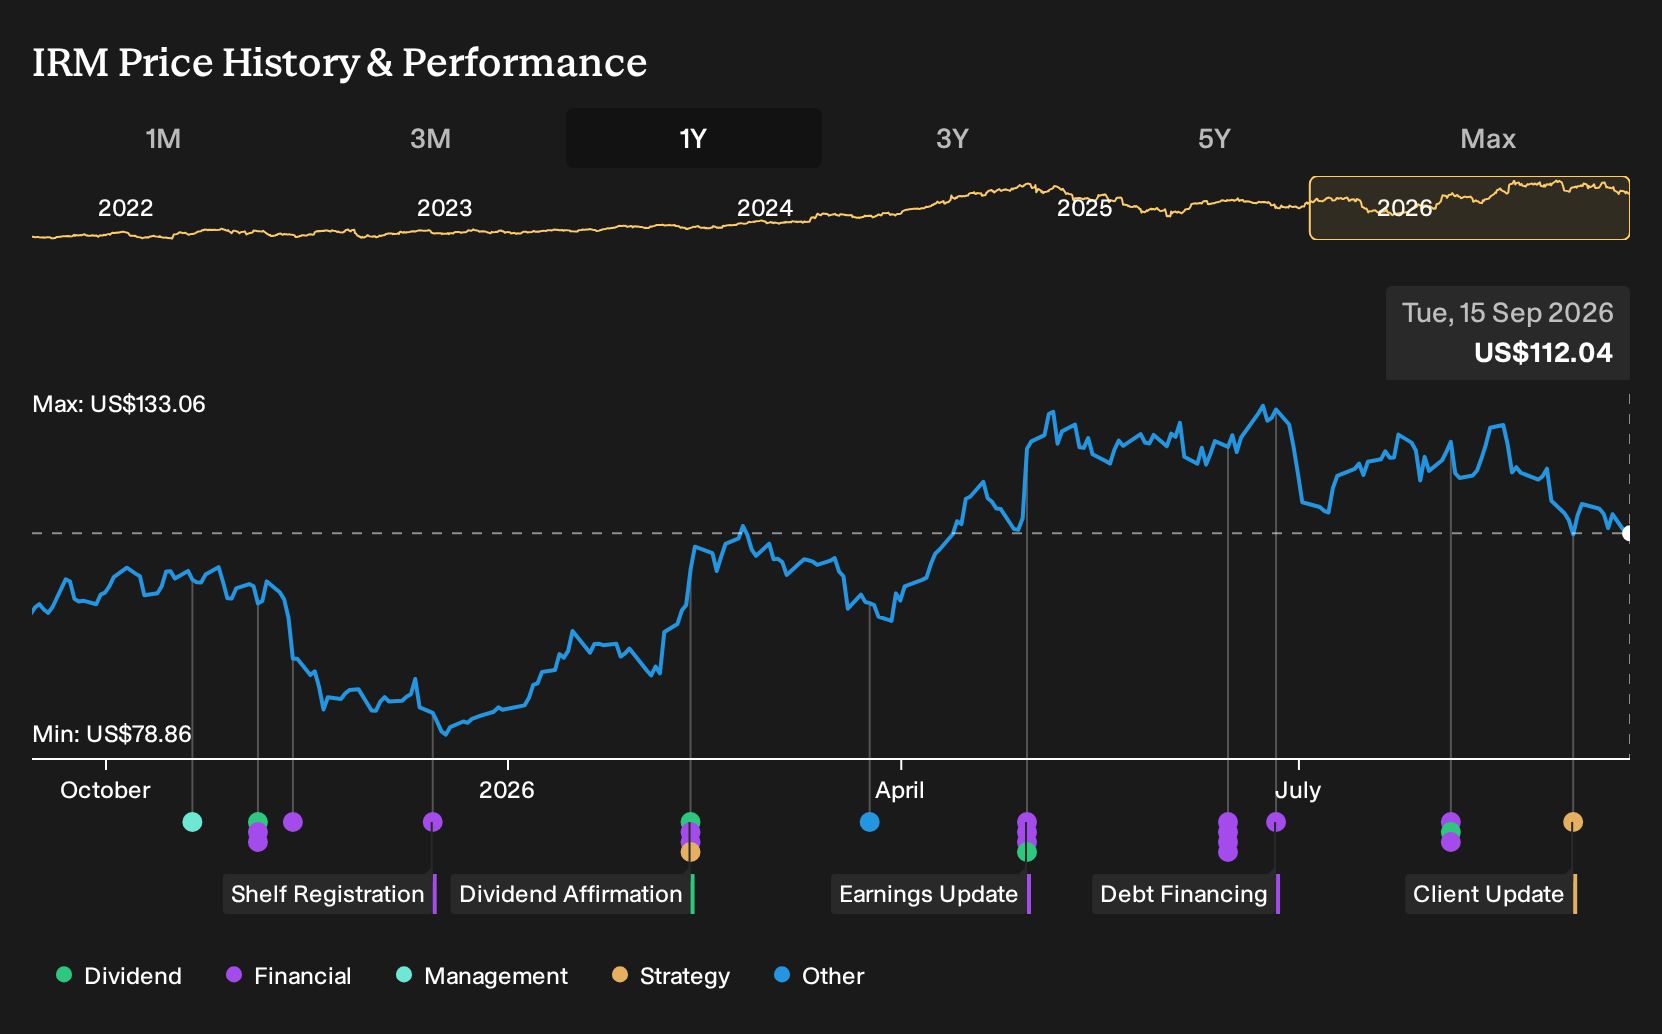
Uncover why Iron Mountain's fair value indicates a 30% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One alternate view is that execution risk on Iron Mountain’s AI platforms is the real swing factor. The most bearish analysts were pencilling in about US$8.9b of revenue and US$529.6m of earnings by 2029 before this Saudi lending deal, which is far more cautious than consensus. That gap shows how widely opinions differ, so it can be useful for you to explore both the pessimistic and the more optimistic narratives and then decide how this new AI workflow contract might shift your own expectations.
Explore 3 other Iron Mountain fair value estimates, including one that suggests it could be worth just $146.10!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Iron Mountain research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Iron Mountain. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iron Mountain's overall financial health at a glance.
Looking For More Investment Ideas Beyond Iron Mountain?
If Iron Mountain has sharpened your thinking about data, cash flow and risk, it can be useful to line it up against a wider watchlist built around clear themes that match your own goals.
- If you are hunting for quality at a discount, start with a focused set of 34 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- Income focused investors can scan for steadier payers by reviewing a curated group of 6 dividend fortresses that offer higher yields with an emphasis on resilience.
- For a more defense minded approach, filter for companies with sturdier finances using a 11 resilient stocks with low risk scores to see which businesses score better on balance sheet strength and risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com