
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Forget Nvidia: This Utility Stock Could Actually Outperform It From Here
Key Points
Nvidia is the face of today's bull market, but it needs an energy source like Oklo's reactors to continue the rally.
If Oklo grows tenfold, its implied market cap would be $67 billion. If Nvidia grows tenfold, its implied market cap would be $53 trillion.
A $67 billion market cap is realistic for Oklo if it can commercialize and scale reactors.
Nearly every bull market has a signature stock, a company that seems to contain that era's dominant story, investing trend, or valuation in miniature. A list of these avatars would have to include Microsoft in the personal computer revolution of the 1990s, Cisco in the dot-com era, Apple in the smartphone boom of the early 2010s, Tesla in the post-COVID-19 years before artificial intelligence (AI), and Nvidia (NASDAQ: NVDA) in the years since.
Three of the previous five are among the world's most valuable companies by market cap today, with Nvidia in first place. Despite Nvidia's remarkable ascent to power, with a roughly 146-fold gain over the last decade, I don't believe it will be the market's top performer over the next 10 years. Indeed, one utility stock that will probably surpass it in performance is one whose innovations could help power Nvidia -- and AI companies more broadly: Oklo (NYSE: OKLO).
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
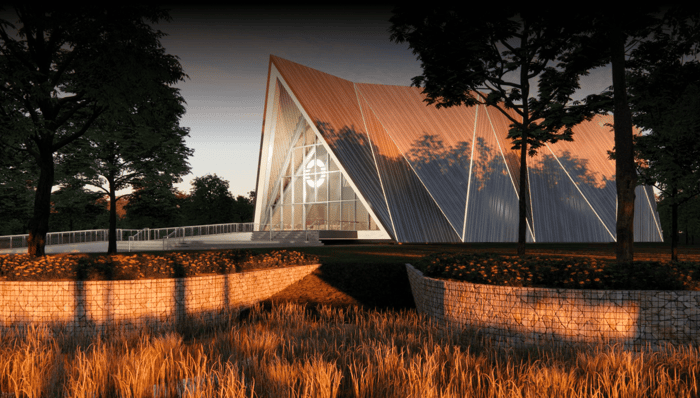
Image source: Oklo.
Small reactors, massive opportunity
Oklo, in a nutshell, is designing nuclear reactors. And not just any nuclear reactor: small nuclear reactors. Oklo's reactors are compact enough to fit on a few acres, roughly two or three football fields, while conventional nuclear power plants can span hundreds and hundreds of acres.
Why should investors care about a reactor that can fit on a few gridirons? Because of the potential for on-site power generation. If a company can get power from its own little power plant, that would limit how much it needs to draw from the grid. Less dependence on the grid means less exposure to grid outages and more certainty over power supply. And for power-hungry operations like AI data centers, that could be enormously valuable.
Oklo, to be sure, doesn't aim to sell reactors; like a traditional electric utility company, it will sell the power generated by the reactors it deploys. This adds another attractive layer to its business: Companies don't have to worry about owning or maintaining a reactor fleet themselves. Oklo would handle the complicated part and simply sell them electricity under long-term contracts.
Investors have already started to recognize Oklo's future value, which is a problem for the stock today but not one the company can't grow into over time. Oklo carries a hefty valuation of roughly $7 billion, which is more than 5,500 times its present-day sales. That doesn't scream value, and it makes Oklo's near-term growth seem unlikely to match, much less outperform, Nvidia or other established AI winners.
But if we look over the next 10 years, Oklo's valuation being smaller than Nvidia's suggests more room for upside. Just consider this: A tenfold gain in Nvidia would make it a $53 trillion-dollar company. On the other hand, a tenfold gain in Oklo would imply a $67 billion valuation, which is roughly $30 billion less than the market cap of Constellation Energy, currently America's leader in nuclear energy generation.
A $67 billion valuation in 2036 is entirely possible if Oklo's reactors can operate commercially. Since Oklo doesn't have a commercial reactor, however, any investment in it will be a gamble. I would recommend this nuclear stock only to those who can take that risk and wait a decade for the long-term hypothesis to play out.
Steven Porrello has positions in Nvidia and Oklo. The Motley Fool has positions in and recommends Apple, Cisco Systems, Constellation Energy, Microsoft, Nvidia, and Tesla. The Motley Fool has a disclosure policy.