
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Atlanticus Holdings (ATLC) Is Back In The Spotlight, But Why?
Atlanticus Holdings (ATLC) has attracted fresh attention after recent price moves left the shares down about 9% over the past month, yet still ahead roughly 40% year to date.
This recent pullback, including the 1-day share price return of down 1.71% and 30-day share price return of down 9.29%, comes after a strong year-to-date share price return of 40.24% and a 3-year total shareholder return above 200%. This suggests momentum has cooled, but longer term holders have still seen substantial gains.
Spot fresh momentum and potential pullbacks around Atlanticus Holdings by comparing it with a curated list of 34 high quality undervalued stocks that share strong cash flows and balance sheets.Atlanticus Holdings now trades about 9% below its recent level, yet sits more than 40% ahead year to date, while analyst targets and intrinsic estimates point to very different fair value anchors. Which reference point deserves more weight?
Most Popular Narrative: 30% Undervalued
Atlanticus Holdings closed at $93.05, while the most followed narrative points to a fair value of $133.50 based on its own set of assumptions and risks. The gap between those two anchors reflects an earnings path that investors need to examine line by line.
The acquisition and integration of Mercury Financial has roughly doubled the balance sheet to about US$7b and brought a US$3b portfolio under Atlanticus portfolio management methods. Management expects this to support higher yields and return on assets over time, directly influencing revenue and earnings.
See why 5 investors see Atlanticus Holdings as 30% undervalued.
Result: Fair Value of $133.50 (UNDERVALUED)
Still, this upbeat Atlanticus Holdings narrative leans heavily on Mercury integration delivering cost savings and on near prime borrowers avoiding a setback in payment behavior.
Find out about the key risks to this Atlanticus Holdings narrative.
Another View: SWS DCF Model Puts Atlanticus Holdings In A Different Light
A second lens on Atlanticus Holdings comes from the SWS DCF model, which points to a fair value of $85.58. That is below the current $93.05 share price, so this approach frames the stock as overvalued rather than 30% undervalued. Which story fits your own expectations for the business?
Our DCF model is only as strong as the cash flow assumptions you believe in, so it helps to walk through the mechanics before leaning on it too heavily. Look into how the SWS DCF model arrives at its fair value.
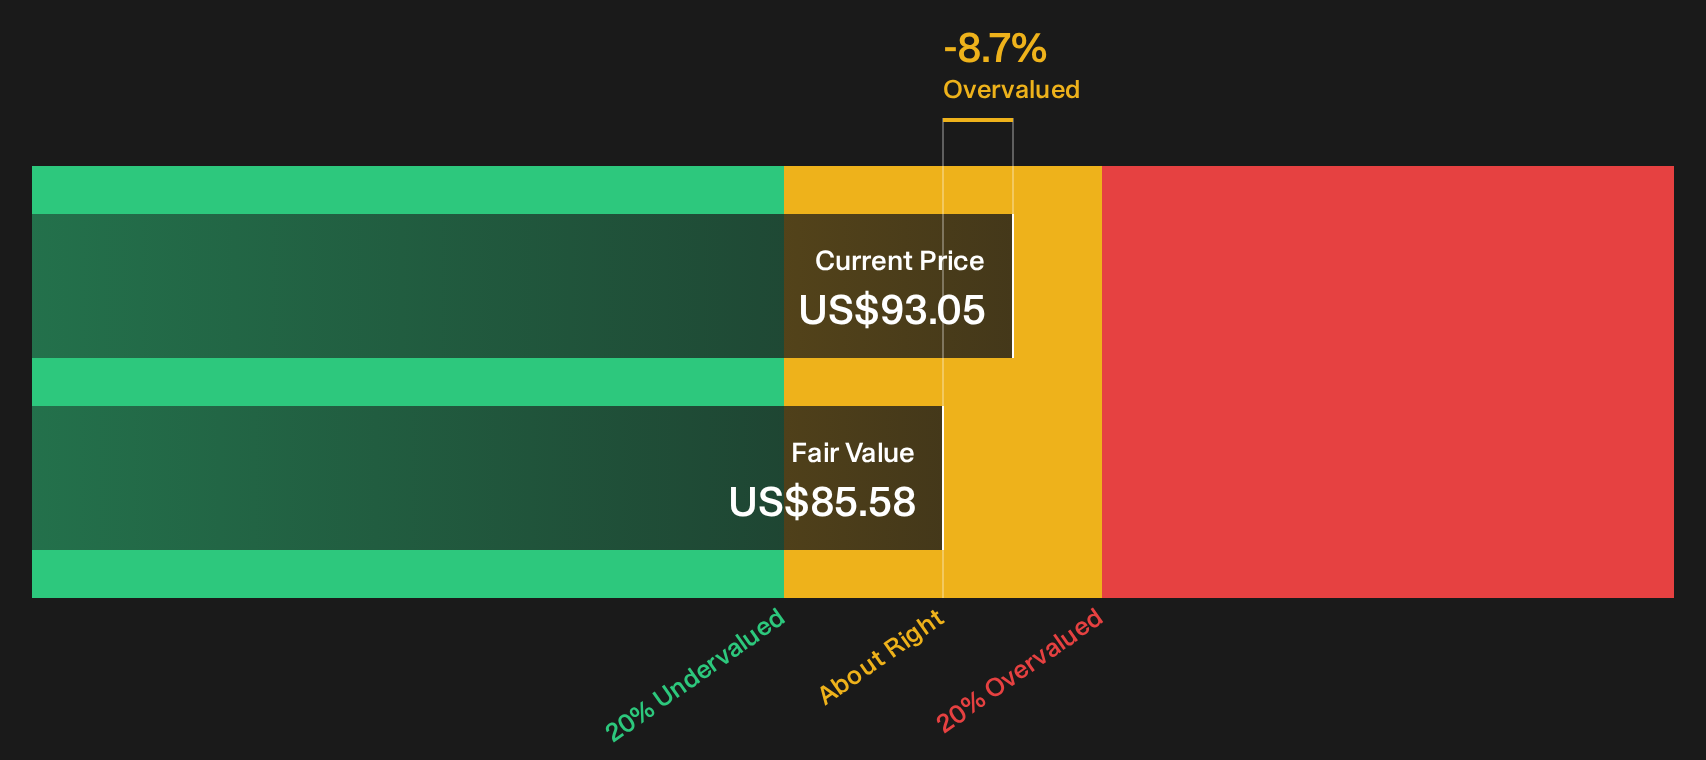
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Atlanticus Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this Atlanticus Holdings debate feels finely balanced, consider acting promptly. Review the numbers yourself, and weigh both the upside and the weak spots in 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Atlanticus Holdings?
Do not stop at a single stock. The next opportunity often appears where few investors are looking, and a structured screener helps you filter fast and stay selective.
- Target potential value opportunities by scanning a curated set of financially robust companies through the 34 high quality undervalued stocks.
- Prioritize capital preservation and smoother portfolio swings by focusing on companies filtered for resilience with the 11 resilient stocks with low risk scores.
- Hunt for quality that flies under most radars by reviewing the 16 high quality undiscovered gems before attention and pricing potentially shift.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com