
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ROHM (TSE:6963) Stock May Be Fully Priced Following New Resistor Launch
ROHM has logged a powerful run over the past year, and that kind of move naturally raises a question about what investors are paying for its sales today. With the share price now well above where it was a year ago, the key issue is how that market value lines up against the revenue base behind it.
- Over the past 12 months, ROHM has returned 118.2%, which puts a lot of pressure on the current price tag to be supported by the company's underlying sales.
- Fresh from launching its SDR01 Series of high anti-surge chip resistors for areas like automotive, industrial gear and AI servers, ROHM may be setting expectations for what future demand and revenue from these components can look like.
- Your read on ROHM is one view; the desks covering it have another. See what analysts think ROHM's shares could be worth.
The issue now is whether ROHM's recent share price level is adequately backed by the sales it is generating today and those investors reasonably expect it to produce.
If you are weighing ROHM against other ways to play this theme, it can help to compare it with a curated set of 60 AI infrastructure stocks.
Has ROHM Run Too Far on Sales?
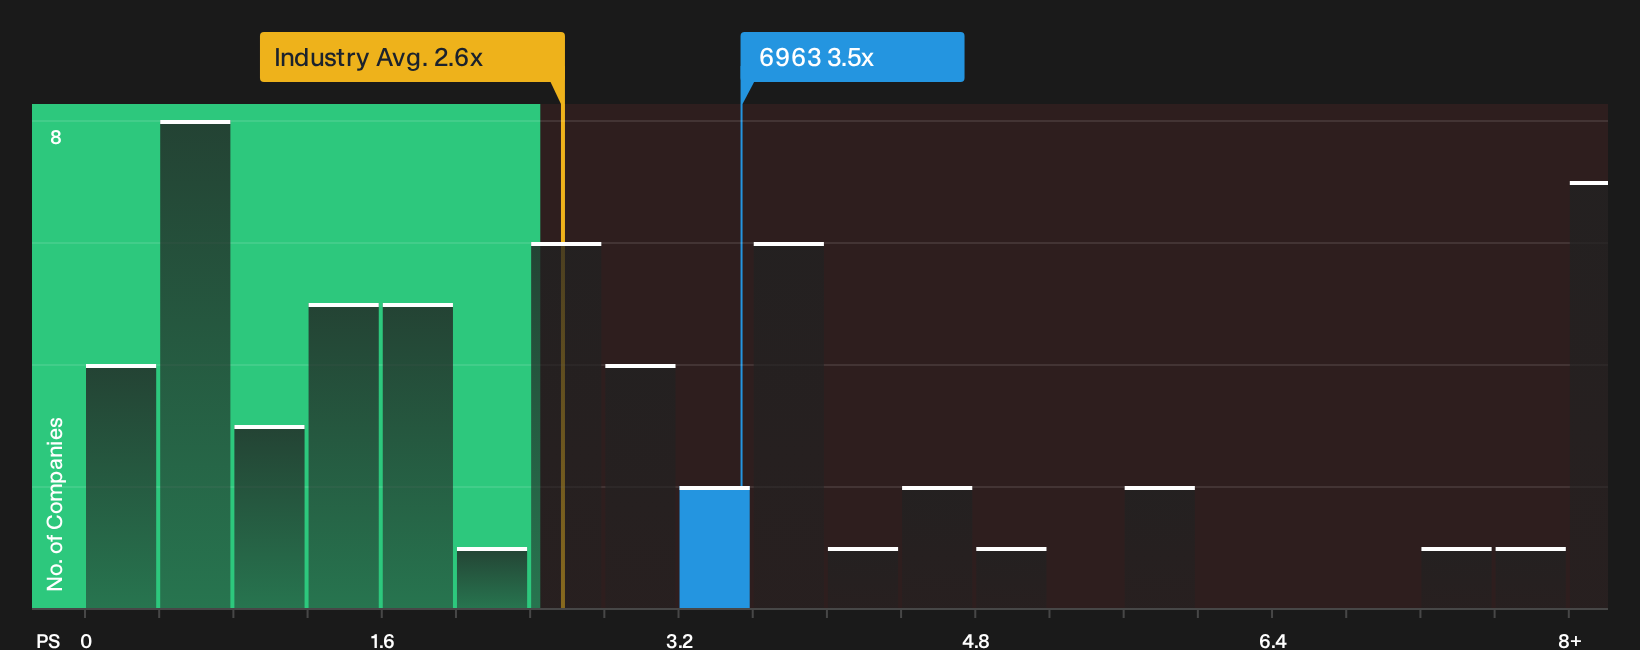
P/S is a useful lens for ROHM because the market is currently reacting more to its revenue potential than to its near term earnings profile. The stock trades on a P/S of 3.5x, which is above both the semiconductor industry average of 2.6x and the peer group closer to 2.2x. That points to investors paying a fuller price for each yen of ROHM's sales compared with many alternatives in the sector.
Because of the SDR01 resistor launch and the broader exposure to automotive, industrial and AI server demand, the pricing suggests the market is already assigning ROHM a premium top line story. On a tailored fair benchmark that adjusts for the business mix and risk profile, the current 3.5x P/S screens higher than the level that model would point to, which implies the shares screen overvalued on this metric alone. Despite the buzz around the new components, the multiple still asks buyers to accept a richer tag on sales than both peers and that customised reference point. Explore the numbers behind ROHM's P/S valuation.
The ROHM Narrative: What Would Justify Today's Price?
Narratives on ROHM pick up where the valuation puzzle leaves off by spelling out which growth paths, margin profiles and earnings trajectories would need to play out for the stock to justify a meaningfully higher or lower price than today. Each storyline links its implied number to a clear view on how ROHM's expansion, profitability and risk profile might evolve, giving you a reference you can return to as fresh information appears.
Community views on ROHM split sharply between those who see an AI power chip opportunity and those who focus on execution risk and rich expectations.
Bull case: 21% undervalued
"ROHM is planning to increase its production capacity and efficiency for SiC (silicon carbide) power devices, correlating with expected battery EV market growth…"
Discover why this Narrative puts ROHM at 21% undervalued.
Bear case: 31% overvalued
"The plan to shift SiC production from 6 inch to 8 inch wafers and increase in-house epi output is intended to cut costs, but if yield and quality on 8 inch lines lag expectations, ROHM could face higher scrap…"
Explore why this Narrative puts ROHM at 31% overvalued.
ROHM's valuation still hinges on who is in charge
Numbers only tell part of the story for ROHM, because the people setting priorities, taking capital decisions and the way they are rewarded can heavily shape what happens next. See who runs ROHM and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com