
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Materion (MTRN) A Bargain On Its Pullback Or Still Fully Priced?
Materion (MTRN) has drawn fresh attention after recent share weakness, with the stock down about 6% over the past week and roughly 15% in the past month. Investors are reassessing what the current pricing implies.
While the short-term share price return has cooled, with Materion down over the past week and month, the stock still carries strong momentum after an 86.32% year-to-date share price gain and a 109.47% total shareholder return over the past year.
Compare Materion's recent surge and pullback with a curated list of other materials companies by scanning the 28 best rare earth metal stocks for potential peers that may be moving on similar themes.
The question now is whether Materion’s sharp pullback after a strong run reflects fresh doubts about the business, or a reset in investor mood that leaves the valuation looking different.
Most Popular Narrative: 20.5% Undervalued
On the most followed view of Materion, the share price of $239.48 sits below a fair value estimate of $301.19. This estimate is based on detailed revenue, margin, and cash flow assumptions using an 8.94% discount rate.
Structural cost improvements, operational efficiencies, and favorable product mix within Electronic Materials are driving record-high EBITDA margins, with management expecting continued year-over-year margin expansion. This is expected to result in lasting changes in net profitability as volumes recover across semiconductor and electronics markets.
See why 11 investors see Materion as 20% undervalued.
Result: Fair Value of $301.19 (UNDERVALUED)
Still, Materion’s reliance on semiconductor and aerospace customers, along with exposure to specialty metal supply and pricing, could quickly challenge the upbeat margin narrative.
Find out about the key risks to this Materion narrative.
Another View: Materion Through Its P/E Lens
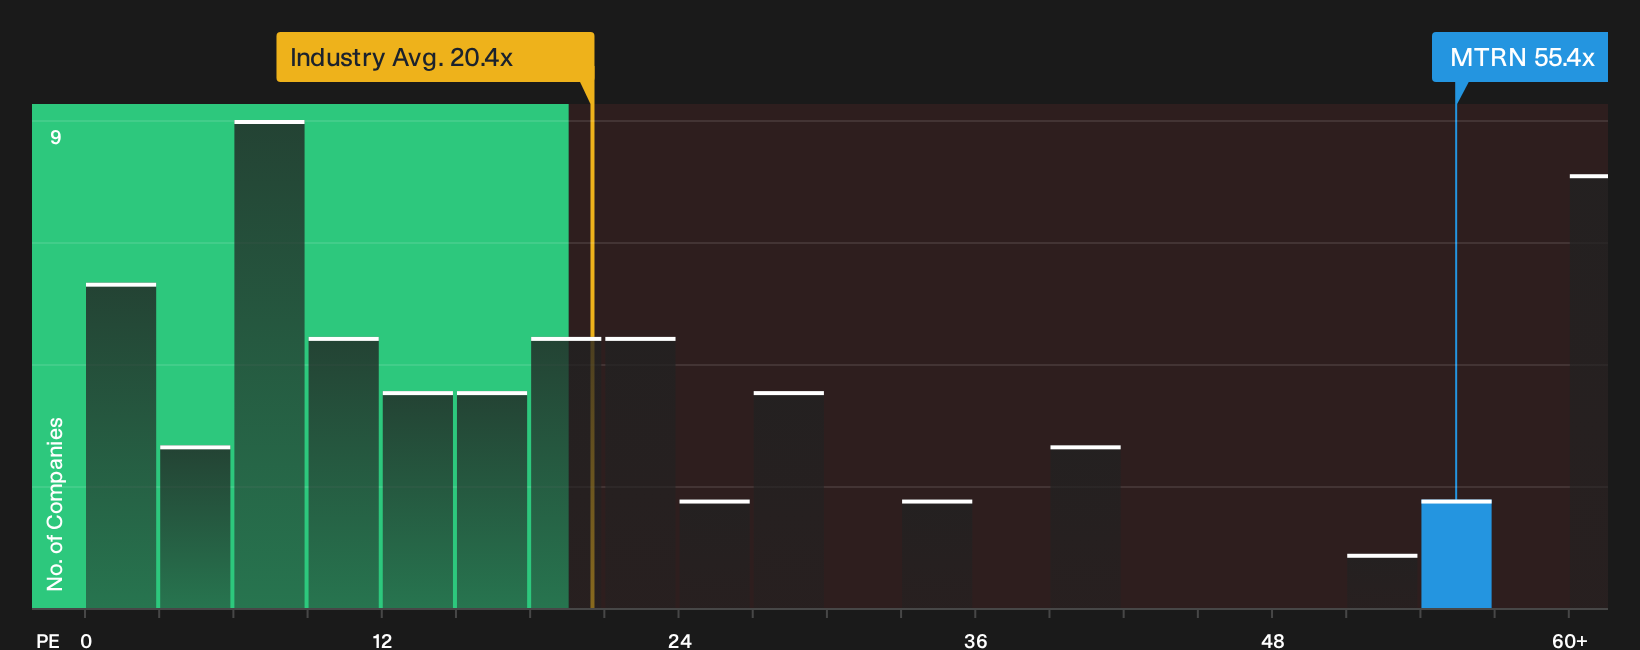
There is a very different picture when Materion is viewed through its current P/E ratio. The stock trades on 55.4x earnings, while the US Metals and Mining group averages 20.3x and the fair ratio for the shares is estimated at 33.4x. That gap points to meaningful valuation risk if sentiment shifts away from premium pricing.
To see how this earnings multiple ties back to the underlying assumptions on margins and growth, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around Materion can be confusing, so treat this as a prompt to move fast, review the numbers yourself, and pressure test every assumption against your own expectations. To weigh both the positives and the concerns in one place, start with the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Materion?
If Materion has sharpened your focus, do not stop here. Broaden your watchlist with fresh angles that could highlight very different risk and reward profiles.
- Target resilience by scanning companies with strong finances and low leverage through the list of solid balance sheet and fundamentals (22 results).
- Hunt for potential value by reviewing the 34 high quality undervalued stocks that combine quality fundamentals with discounted pricing.
- Spot emerging opportunities early by checking the 16 high quality undiscovered gems before they hit everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com