
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sempra (SRE) Stock Trades At A Premium On Fresh LNG Deal
Sempra has delivered a 45.6% total return over the past 5 years, yet its recent pullback and fresh liquefied natural gas commitments leave a clear question about what investors are paying for its earnings today. With the stock last closing at US$81.20, the issue now is how that price lines up with what the utility is currently earning and expected to earn.
- Over 5 years, Sempra’s 45.6% return puts real weight on whether the current share price still lines up with the earning power that supported that outcome.
- The 20-year LNG supply deal with Petrobras, tied to the roughly US$12b Port Arthur Phase 2 build out, may support expectations for future cash generation but also extends the capital and execution commitments that earnings need to cover.
- There is a second opinion on Sempra worth weighing. See what analysts think Sempra's shares could be worth.
The issue now is whether Sempra’s recent share price, after that longer term gain and new LNG agreement, is adequately explained by its earnings profile.
If you want context for Sempra’s earnings story and LNG expansion, it can help to compare it with a broader set of 38 power grid technology and infrastructure stocks
Is Sempra Fairly Priced on Earnings?
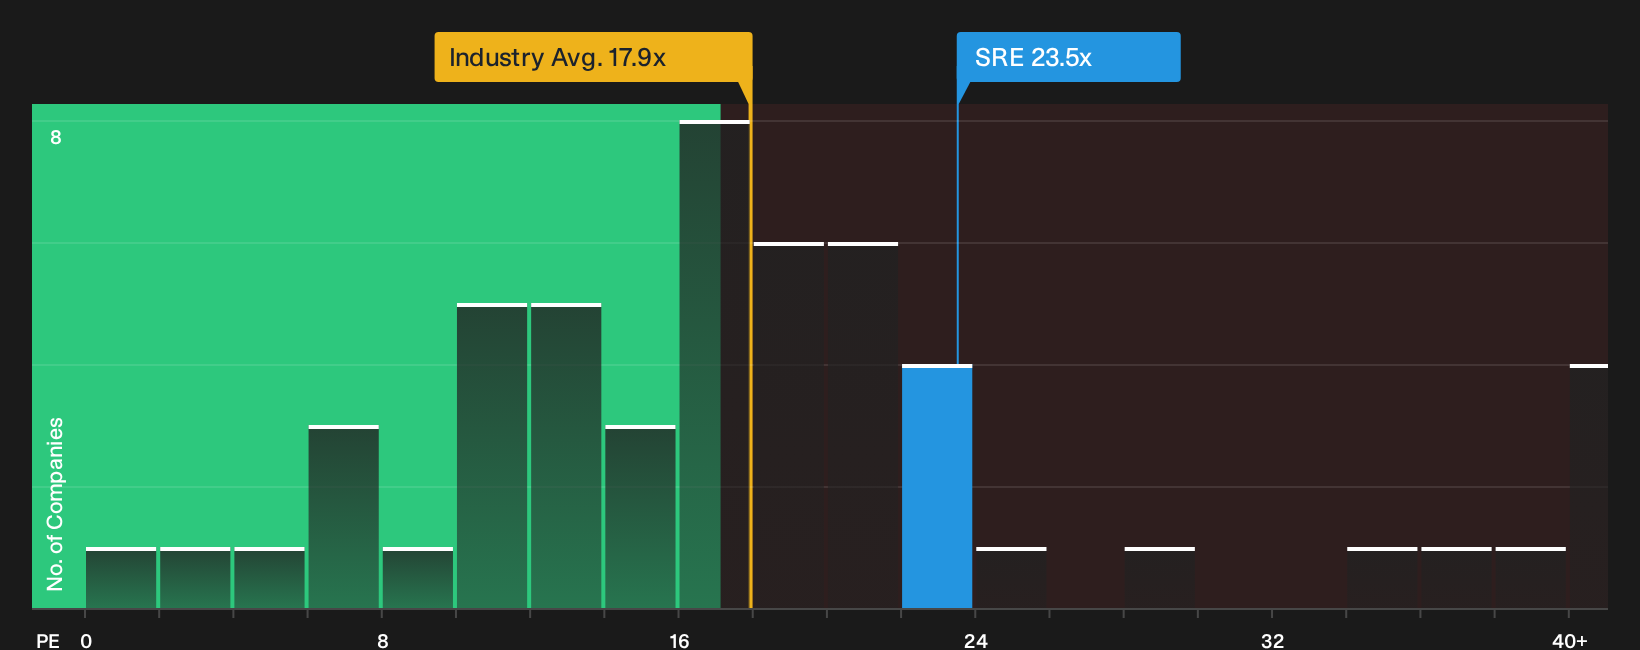
P/E is often the cleanest way to look at a regulated utility such as Sempra because earnings tend to be the main driver of value for this kind of business. On that yardstick, Sempra trades at about 23.5x earnings, compared with an Integrated Utilities industry average of roughly 17.9x and a peer group around 19.3x. That points to investors paying a clear premium for each dollar of current profit.
The modelled fair P/E multiple, which folds in Sempra’s growth profile, profitability, size and risk, sits close to the current ratio so the stock screens about right on this measure rather than distinctly cheap or expensive. Because the new 20 year LNG deal with Petrobras raises expectations for long term contracted cash flows, the fact the P/E is only slightly above that tailored fair level suggests recent enthusiasm has not pushed the earnings multiple to extreme territory. Explore the numbers behind Sempra's P/E valuation.
The Sempra Narrative: What Would Justify Today's Price?
Narratives on Sempra pick up where the P/E puzzle leaves off. They spell out which paths for future growth, margins and earnings would need to play out for the stock to look meaningfully cheap or expensive relative to today’s price. Each perspective treats Sempra’s fair value as a thesis that can be tracked over time, so you can see how the underlying business story holds up. These narratives are available on Simply Wall St’s Community page.
One of the top community narratives on Sempra: 22% undervalued
"LNG project progress and capital recycling at Sempra Infrastructure enhance cash flow, balance sheet strength, and capacity for profitable utility reinvestment..."
Discover why this Narrative puts Sempra at 22% undervalued.
The share price is only one side of the Sempra story
Sempra’s earnings and LNG commitments frame the financial picture, but the people setting priorities and how they are rewarded can heavily shape what you actually own. See who runs Sempra and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com