
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will ECOC 2026 Product Launches Change Viavi Solutions Stock Narrative
- Viavi Solutions recently showcased an expanded end-to-end data center and optical testing portfolio at ECOC 2026 in Malaga, including 1.6T Ethernet transceiver validation, AI fabric testing platforms, CPO and Silicon Photonics tools, quantum network evaluation, and high density fiber inspection and monitoring systems.
- The breadth of new products, from the ONE LabPro ONE-1600 and TestCenter D2 to MAP-300 and MAP-2800 test heads, points to Viavi Solutions leaning into higher complexity data center workloads and advanced optical architectures that can influence mix, R&D spend, and long-term demand for its test and monitoring ecosystem.
- We will now look at how Viavi Solutions' investment narrative is shaped by this ECOC launch of 1.6T data center test platforms.
Scan beyond Viavi Solutions and line up other potential beneficiaries of the AI data center buildout with our curated 59 AI infrastructure stocks.
Viavi Solutions Investment Narrative Recap
Viavi Solutions appeals to investors who buy into a test and monitoring business that leans heavily on high speed data center optics, while still carrying exposure to weaker wireless and service provider spending cycles. The immediate story hinges on whether strong interest in 400G to 1.6T infrastructure can offset a company that is still loss making with volatile returns.
The key near term swing factor remains execution in the data center ecosystem as orders track multi year upgrade cycles. The biggest current risk sits in delayed carrier and cable capex and in integrating recent acquisitions while carrying higher debt. This ECOC launch looks incremental rather than a clear inflection on its own.
The ONE LabPro ONE-1600 platform shown at ECOC 2026 is the most relevant piece for investors watching Viavi Solutions right now. It targets pluggable 1.6T transceiver validation with configurations that address both network equipment labs and production lines, as well as a lower priced ERP module for volume environments.
That matters because the main catalyst for the stock is whether Viavi can translate its 1.6T test portfolio into consistent orders as customers plan moves toward 1.6T and eventually 3.2T architectures. Execution risk is real, since revenue still depends on cyclical operators and geopolitically exposed supply chains, but this product family directly addresses the core upgrade theme.
Viavi Solutions' current analyst narrative points to revenues of US$2.5b and earnings of US$503.0m by 2029. That setup assumes 18.0% yearly revenue growth and an earnings swing of about US$533.4m, from a loss of US$30.4m today to the 2029 consensus figure.
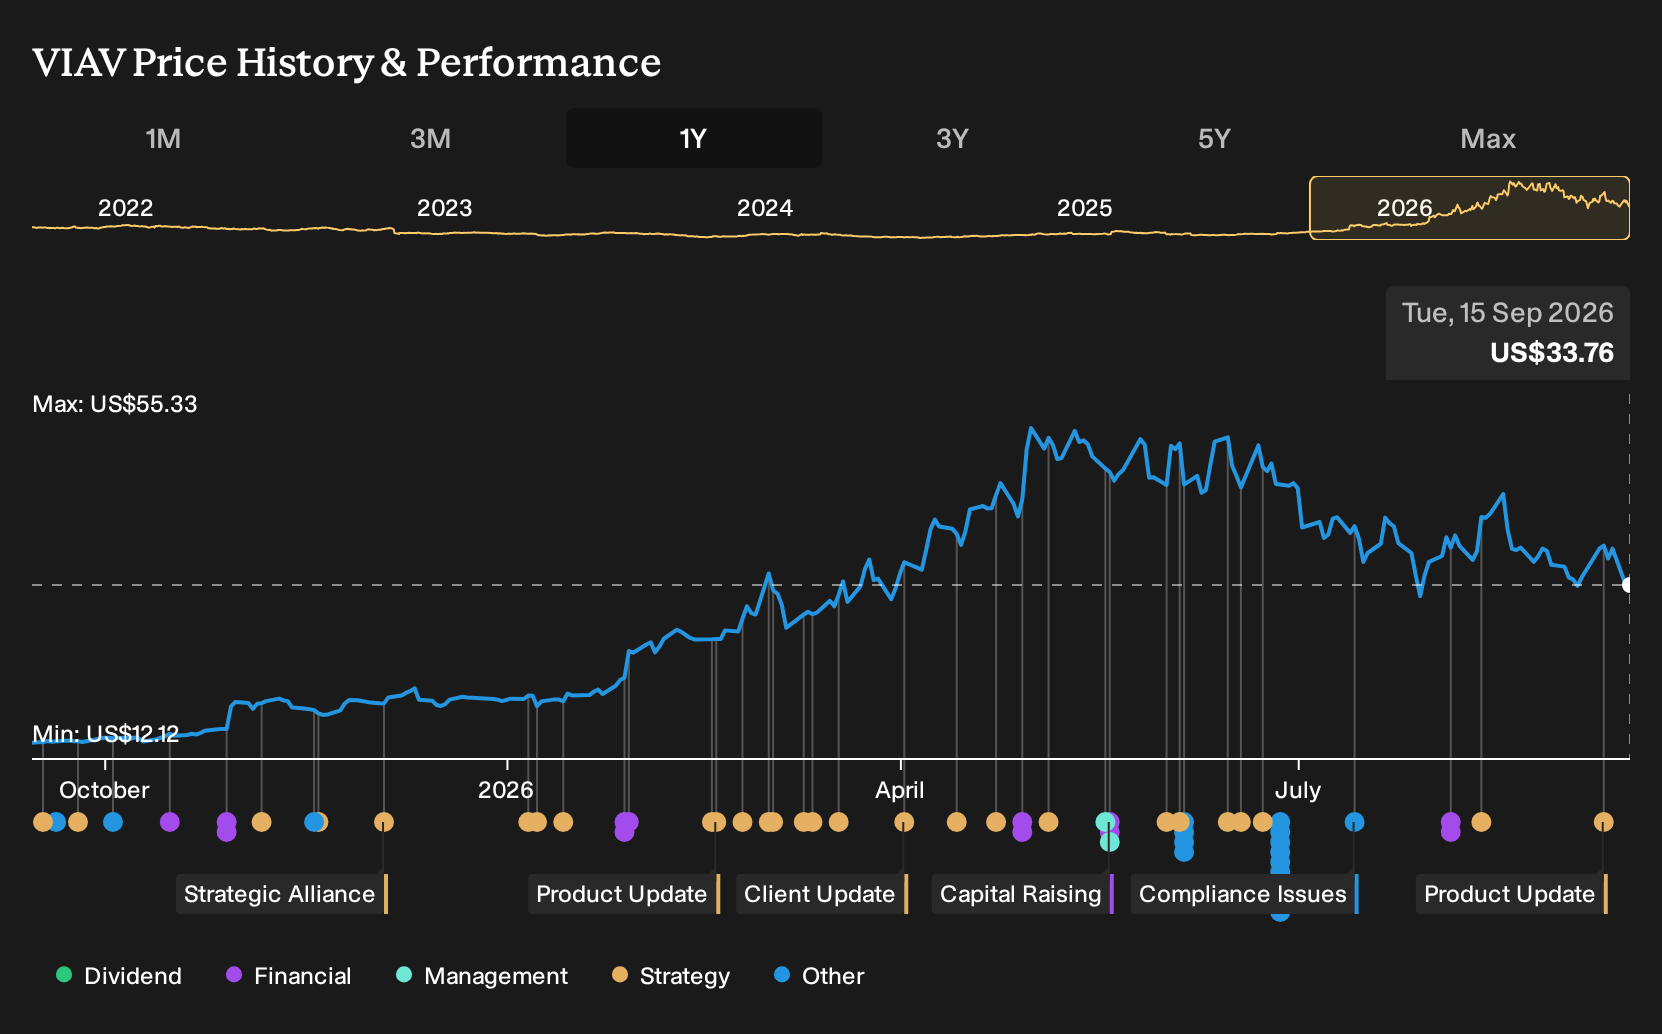
Uncover why Viavi Solutions' fair value indicates a potential 82% upside to its current price, a discount that could close sooner than many expect.
Exploring Other Perspectives
One alternate view focuses on Viavi Solutions being tightly hitched to AI data center spending cycles. The most cautious analysts were already only penciling in about US$2.5b of revenue and US$524.5m of earnings by 2029 before this ECOC news. That is a more pessimistic narrative. It shows how strongly opinions differ. Use this ECOC launch as a prompt to compare those assumptions with your own and explore several competing forecasts.
Explore 3 other Viavi Solutions fair value estimates, including one that suggests there could be as much as 17% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Viavi Solutions research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Viavi Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viavi Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Viavi Solutions?
Once you have a view on Viavi Solutions, broaden your watchlist by using the Simply Wall St Screener to scan for other stocks that match the kind of risk, quality, or income profile you are targeting.
- For investors who want quality at a discount, start with a curated set of 34 high quality undervalued stocks that may warrant a closer look.
- If capital preservation is your priority, focus on resilience first and see which companies appear in the 11 resilient stocks with low risk scores to anchor the cautious side of your portfolio.
- Those hunting for companies that already have robust finances can begin with a list of solid balance sheet and fundamentals (22 results) and look for ideas that pair balance sheet strength with the themes that interest you most.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com