
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Dividend Payout Altering The Investment Case For Domino's Stock (DPZ)?
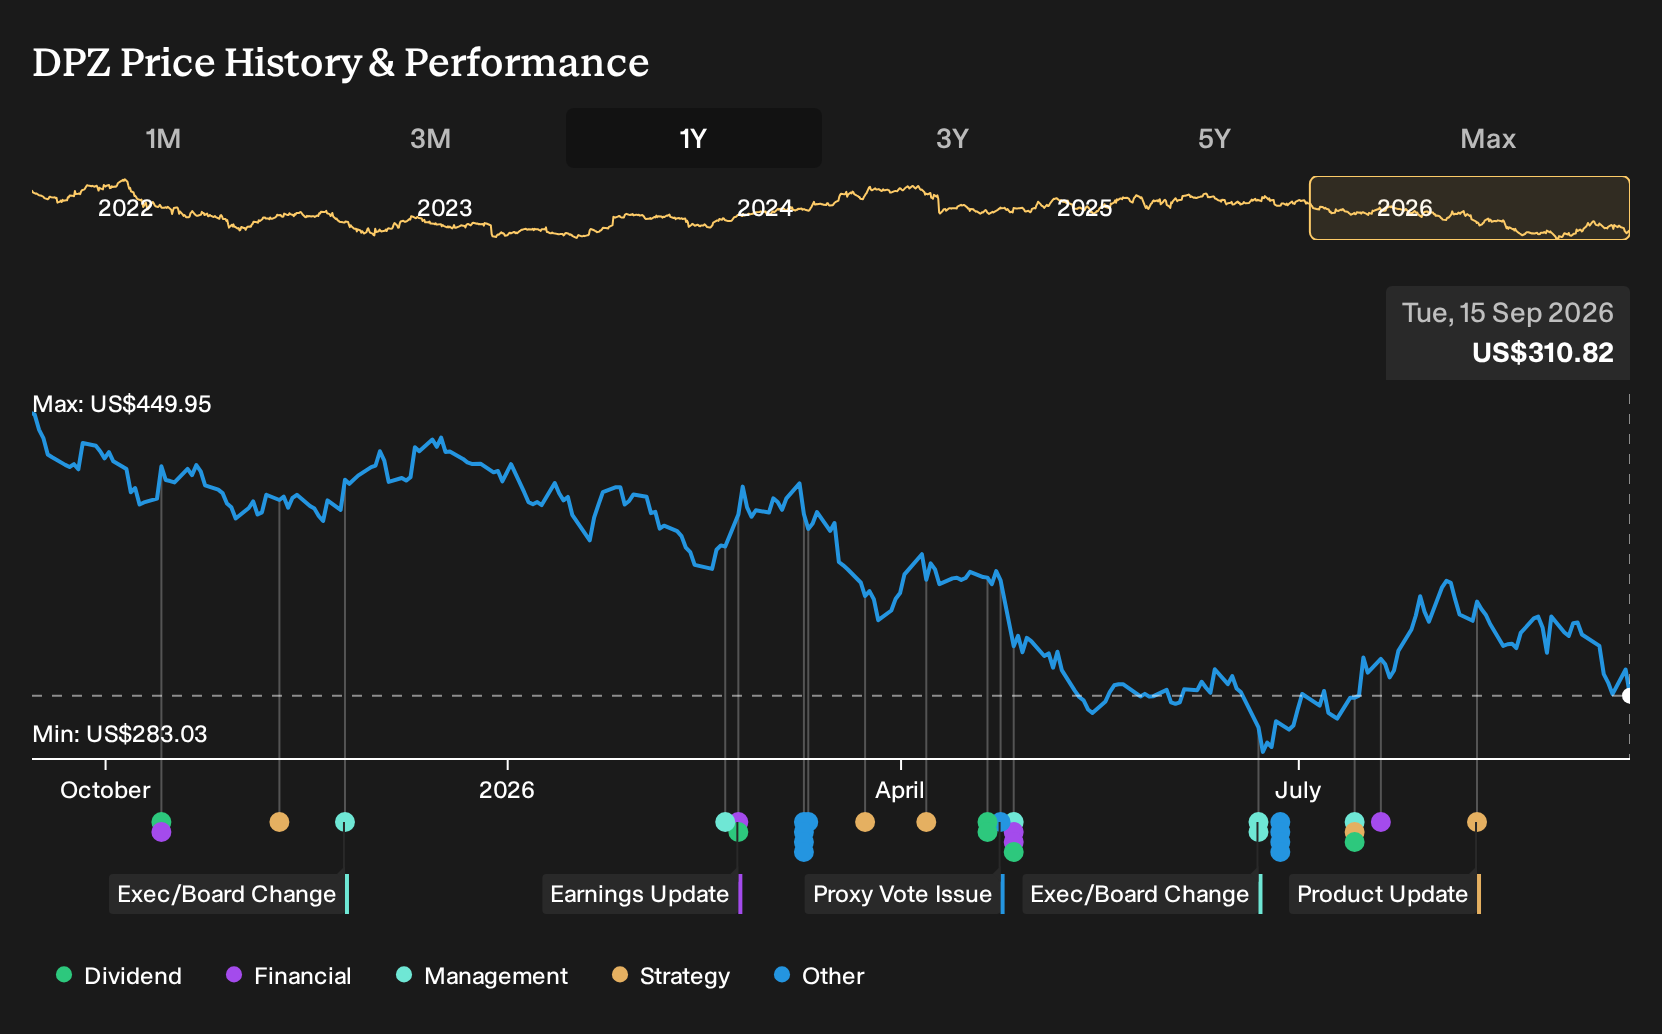
- Domino's Pizza announced a total dividend of $1.99 per share with an ex-dividend date that passed on 15 September 2026 and confirmed 13 Ohio store closures tied to an isolated former franchisee issue.
- The combination of a relatively low payout ratio, a dividend track record dating back to 2013, and limited franchise terminations highlights how Domino's Pizza is seeking to balance shareholder returns with franchise system stability.
- This article examines how Domino's Pizza's dividend commitment, together with isolated franchise closures, may influence the broader investment narrative around the business.
Domino's Pizza Investment Narrative Recap
To own Domino's Pizza, you need to believe that a global, franchise-heavy pizza chain can keep pulling in digital and delivery demand even as the broader pizza category looks flat. The key short term swing factor is whether recent delivery partnerships, loyalty changes and menu additions keep traffic and ticket size healthy.
The recent Ohio franchise closures look contained and management is already working on transfers, so the operational hit appears limited beside the wider unit base. The bigger watchpoint is pressure on franchisee economics, especially internationally, where slower unit growth or repeated closures could weigh on royalties and affect that core growth narrative.
The fresh US$1.99 per share dividend, with an ex date that passed on 15 September 2026, sits in the middle of this story. Domino's Pizza is signaling it wants to keep rewarding shareholders while still running a franchise system that can fund remodels, tech upgrades and marketing without stretching operators.
For you, that dividend is less about the yield and more about discipline. It competes directly with debt paydown, new store openings and supply chain investment. If traffic in the pizza category remains soft or procurement efficiencies fade, the balance between maintaining that cash return and funding growth projects becomes an important catalyst to track.
Domino's Pizza's current forecasts point to revenues of US$5.6b and earnings of US$733.0m by 2029, based on analysts assuming 3.8% yearly revenue growth and an earnings increase of about US$136.5m from US$596.5m today.
Uncover why Domino's Pizza's fair value indicates a 22% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One alternate angle on Domino's Pizza focuses on the bullish catalyst of carryout and aggregator demand. The most optimistic analysts were pencilling in revenues of about US$5.8b and earnings of roughly US$755.1m by 2029, prior to this dividend announcement and the Ohio franchise issue. You can treat those richer assumptions as one end of a wide opinion range that may shift as this news gets absorbed.
Explore 3 other Domino's Pizza fair value estimates, including one that suggests as much as 31% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Domino's Pizza research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Domino's Pizza. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Domino's Pizza's overall financial health at a glance.
Looking For More Ideas Beyond Domino's Pizza?
Once you have a handle on Domino's Pizza, it can help to line it up against other opportunities that match your income needs, risk tolerance, and time horizon. The Simply Wall St Screener lets you scan the market quickly using clear filters, so you can build a shortlist that genuinely fits how you like to invest.
- If you want income that aims to be more durable, check out a curated 6 dividend fortresses that focus on companies prioritizing cash returns to shareholders.
- For investors who prefer a margin of safety on price, start with a 34 high quality undervalued stocks and see which businesses currently trade below analyst-assessed fair value.
- When capital preservation matters most, consider beginning your research with a 11 resilient stocks with low risk scores that historically show more resilient fundamentals and balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com