
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Upcoming Earnings Will Impact AutoZone Stock Investors
- AutoZone marked a milestone by opening its 8,000th store in Murfreesboro, Tennessee, extending a 47 year build out across the U.S., Mexico and Brazil and adding more free diagnostic and tool lending services for local drivers and repair shops.
- The combination of a larger store network and service heavy offerings, such as Fix Finder diagnostics and Loan A Tool, sharpens AutoZone’s focus on parts availability and do it for me demand at a time when investors are considering a cautious earnings outlook and mixed analyst expectations.
- We will now look at how AutoZone’s investment narrative could be influenced by the 8,000th store milestone and the upcoming earnings report.
Contrast AutoZone’s 8,000 store milestone and mixed earnings sentiment with other repair focused retailers by scanning our curated list of list of solid balance sheet and fundamentals (22 results) for comparison.
AutoZone Investment Narrative Recap
For a shareholder in AutoZone, the core belief is that a dense store and distribution footprint can keep parts on hand, serve do it for me customers reliably, and convert that access into steady sales and high quality earnings. The 8,000th store fits that story operationally but does not by itself change the near term outlook. The bigger swing factor right now sits with how upcoming quarters balance store expansion, mega hub rollouts and supply chain investments against already pressured margins.
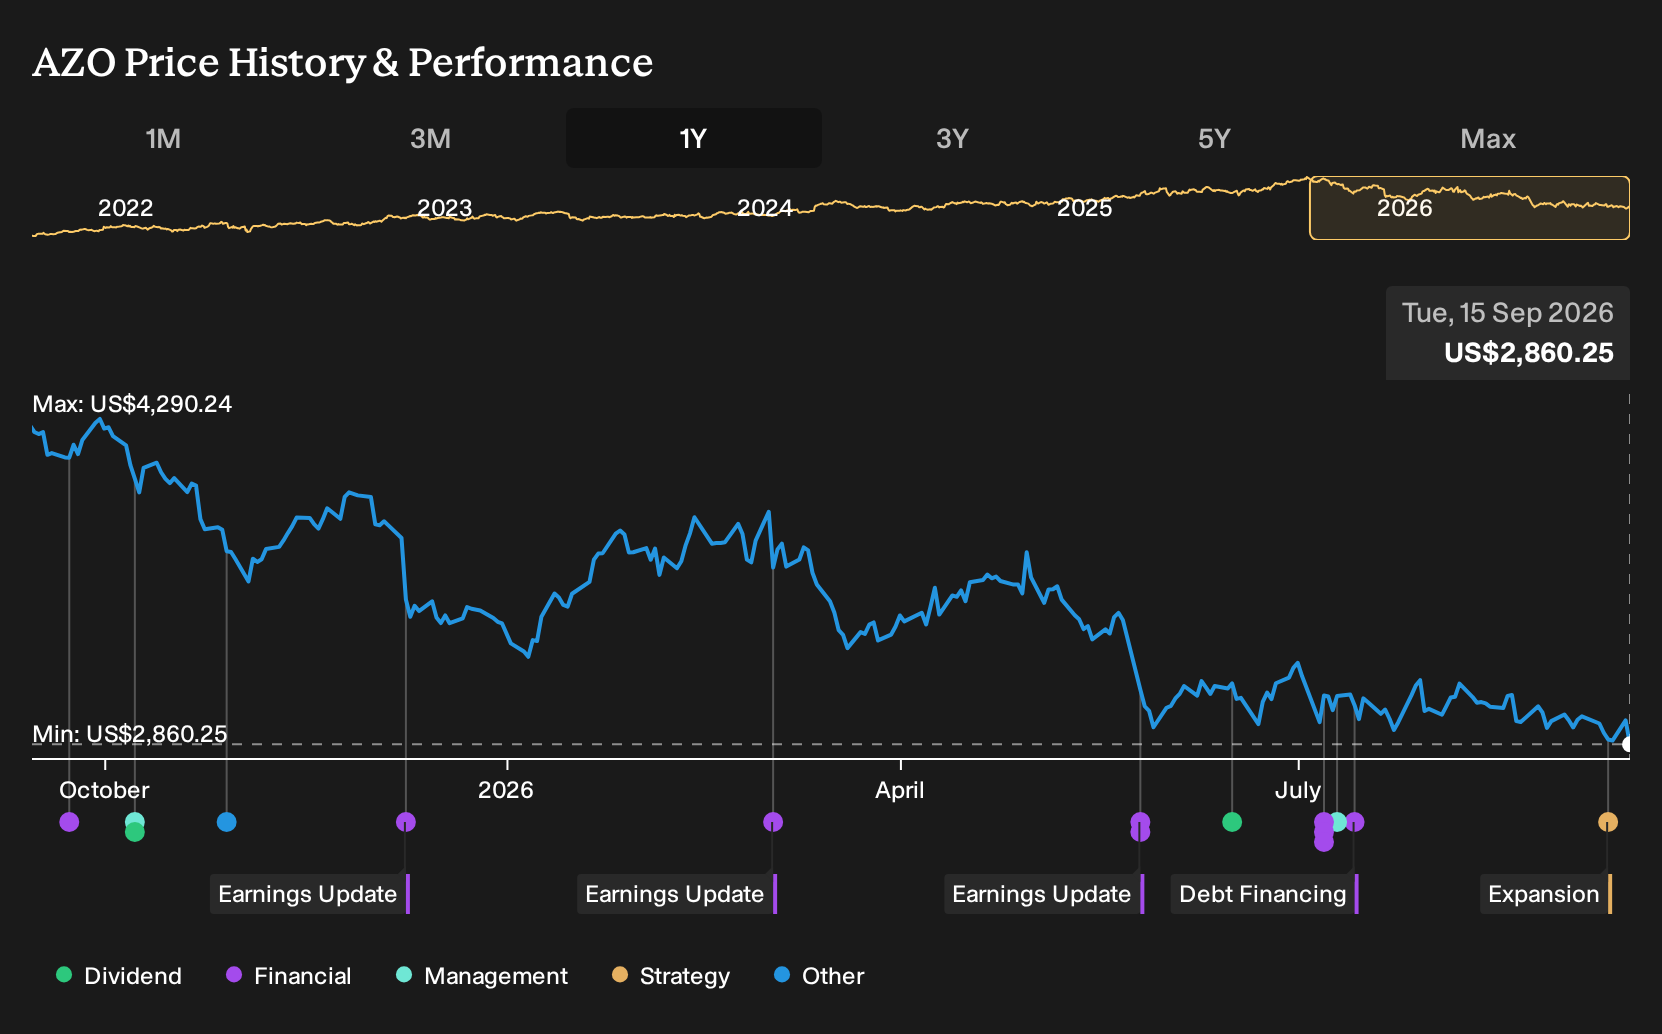
The immediate risk is that inflation, tariffs, FX and higher SG&A from growth projects compress profitability faster than new stores and commercial sales can support it. That tension is front and center heading into the September 22 earnings release, especially after the share price pullback and recent underperformance versus both the broader US market and the Specialty Retail group.
The most relevant recent thread for this expansion is AutoZone’s upcoming fiscal Q4 report, which some analysts view as a potential inflection if improving comparable sales hold up into fiscal 2027. The Murfreesboro opening and broader store count of 8,031 outlets across the U.S., Mexico and Brazil plugs directly into that same theme of availability and faster delivery for both retail and commercial customers.
In the short term, the key question for you is whether higher parts access and service heavy offerings like Fix Finder and Loan A Tool translate into enough revenue and EBIT to offset FX headwinds, cost inflation and international build out. Analyst commentary around earnings expectations and the Zacks Rank is worth being aware of, but the more practical focus is on execution at mega hubs, international stores and new automated distribution centers that need to start easing margin pressure over time.
AutoZone Forecasts and Assumptions Into 2029
AutoZone's narrative projects US$24.9b revenue and US$3.3b earnings by 2029. This implies 7.6% yearly revenue growth and an earnings increase of about US$0.8b from US$2.5b today.
Analysts building this profile are leaning on a few clear pillars. They expect profit margins to move from 12.4% today to 13.2% in three years, while earnings per share rise toward US$213.14 by around June 2029. Those figures already bake in an assumed 2.41% annual decline in the share count, so the projected profit pool is being spread over fewer shares over time.
For readers tracking valuation, the numbers assume AutoZone trades on a P/E of 23.5x those 2029 earnings, compared with 20.3x today and a current US Specialty Retail industry level of 20.1x. That multiple, combined with the US$24.9b revenue and US$3.3b earnings estimates for 2029, underpins the consensus price target of US$3,969.38, with a discount rate in the 8.7% range used to translate those future cash flows back to today.
There is a spread around that central view. The most optimistic analysts are pointing to earnings closer to US$3.7b and a price target of US$4,800. The more cautious end of the range is anchoring around US$3,200 per share. That band of outcomes reflects debate about how quickly mega hubs, international stores and new distribution centers convert operational gains into sustained profit improvement.
At the current share price of US$3,087.77, the consensus target implies a 22.2% gap that investors will notice. Before you anchor on that number, it is worth stress testing each leg of the story, from the 7.6% annual top line growth and margin lift to the higher future P/E, against your own view of AutoZone's ability to turn more than 8,000 locations, diagnostic services and tool lending into durable earnings power.
Uncover why AutoZone's fair value indicates a 39% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, views on AutoZone range from about US$3,029 per share to roughly US$3,969. That is a wide band for one ticker. When you also consider FX headwinds, tariffs and rising SG&A, it becomes clear why opinions differ so sharply. Consider exploring those alternative viewpoints directly.
Explore 2 other AutoZone fair value estimates, including one that suggests up to 39% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AutoZone research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AutoZone. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AutoZone's overall financial health at a glance.
Looking For More Investment Ideas Beyond AutoZone?
If the AutoZone story has sharpened your thinking and you want to test that framework on other opportunities, the Simply Wall St Screener can help you scan for companies that better match your risk profile, income needs and time horizon.
- If capital preservation comes first for you, filter for stocks that aim to keep volatility contained by starting with a 11 resilient stocks with low risk scores that already clear a basic resilience bar.
- If you would rather focus on cash returns, build a watchlist of income focused candidates using a set of 6 dividend fortresses that prioritize higher yields backed by underlying fundamentals.
- If you are hunting for opportunities that are not yet widely followed, broaden your research with a basket of 16 high quality undiscovered gems that pair strong financials with lower current visibility among investors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com