
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lotus Bakeries (ENXTBR:LOTB) Plans Major Biscoff Expansion, Is It Fully Priced?
Lotus Bakeries (ENXTBR:LOTB) has drawn fresh attention after its recent share price performance, with the stock up about 51% over the past year and roughly 66% over three years.
Recent trading has been choppy, with a 7-day share price return slightly in the red and a softer 30-day move. Even so, Lotus Bakeries still carries strong momentum given its year-to-date share price return near 48% and a 5-year total shareholder return above 100%, which points to sustained investor optimism about its risk and growth profile.
Compare Lotus Bakeries' run with a curated group of resilient consumer stocks screened for strong fundamentals in our 102 resilient stocks with low risk scores.
The sharp move in Lotus Bakeries, alongside solid reported revenue and net income growth, raises a simple tension. Are you paying for a stronger business, or for sentiment that has run ahead of the fundamentals?
Most Popular Narrative: 1% Undervalued
On the latest figures, Lotus Bakeries closed at €12,140, which sits slightly below the most widely followed fair value estimate of about €12,305. That small gap matters because it rests on a detailed view of capacity expansion, margins, and required returns.
Lotus Bakeries plans to invest at least €500 million from 2024 to 2030 in its largest expansion program to date, focused on scaling production capacity for the Biscoff brand. The investment will support new production facilities and expansions in Belgium and Thailand, as well as a new production hall at the Mebane, North Carolina site, which is expected to be operational by mid 2028.
See why 17 investors see Lotus Bakeries as 1% undervalued.
The narrative uses a 6.666% discount rate and assumes annual revenue growth of about 11.4% with profit margins near 13.1%. Together, these inputs produce a fair value estimate of roughly €12,305 per share. That compares closely with the current analyst consensus target of €12,305.20 and sits just above the recent closing price, so the story leans on the idea that the €500m capacity build and international reach can support these growth and profitability assumptions without stretching them aggressively.
Result: Fair Value of €12,305 (ABOUT RIGHT)
Still, the fair value story for Lotus Bakeries depends heavily on significant capital expenditures actually delivering and on raw material costs, especially chocolate, remaining manageable.
Find out about the key risks to this Lotus Bakeries narrative.
Another View On Lotus Bakeries' Valuation
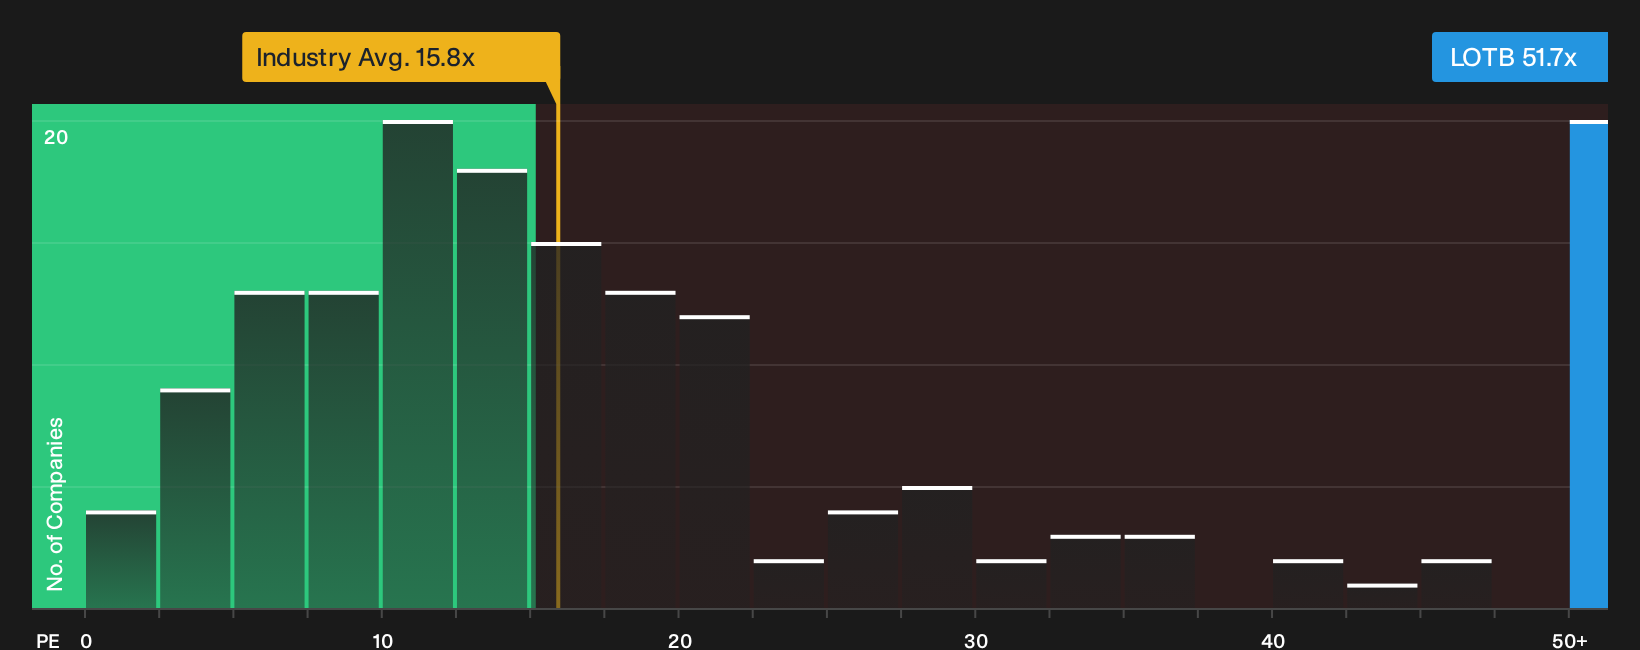
On earnings multiples, Lotus Bakeries looks much less forgiving. The stock trades on a P/E of 51.7x, while the fair ratio is 24.4x, the European Food group sits at 15.9x, and peers average 37.6x. That gap points to meaningful valuation risk if sentiment cools.
To see how this price stacks up against the underlying business, take a closer look at our valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed signals on Lotus Bakeries leave you undecided, move quickly and test the story against your own expectations and risk tolerance. To see what optimism in the market is focusing on, start by checking the 2 key rewards.
Looking for more investment ideas beyond Lotus Bakeries?
If Lotus Bakeries has sharpened your focus on quality, do not stop here. Broaden your watchlist now and give yourself stronger choices next time markets move.
- Target underpriced quality by scanning companies that combine resilient fundamentals with appealing valuations using the 195 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with sturdier payouts and higher yields through the 160 dividend fortresses.
- Prioritize resilience by filtering for companies with cleaner balance sheets and solid financial foundations in the list of solid balance sheet and fundamentals (195 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com