
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is FuboTV (FUBO) Cheap Following Mixed Third Quarter 2026 Results?
FuboTV (FUBO) is back in focus after third quarter 2026 results that paired higher global revenue and a record 5.75 million North American subscribers with weaker adjusted EBITDA and another quarterly loss.
The mixed third quarter update landed against a bruising backdrop for FuboTV, with the share price falling about 65% year to date and the 1-year total shareholder return down roughly 79%. However, the 3-month share price return of about 23% hints at some short term momentum rebuilding as markets reassess both the growth story and the risks around profitability.
Scan how FuboTV compares with other streaming and media plays by reviewing the hand picked 34 high quality undervalued stocks that may offer stronger combinations of revenue and balance sheet quality.
Bulls see FuboTV as a lower-priced way to own a growing sports streaming platform after heavy share price damage. Bears point to ongoing losses and weaker EBITDA. Which side do current valuation markers support next?
Preferred Price-to-Sales of 0.1x: Is it justified?
On simple sales-based markers, FuboTV screens as cheap. The stock last closed at $10.91 while trading on a P/S of just 0.1x, which is well below both peers and sector averages according to current checks.
The price to sales ratio compares what investors are paying for each dollar of revenue to what the business is currently generating. For a streaming platform like FuboTV that is still loss making but reporting $5,711.99m in annual television programming and distribution revenue, this kind of metric often becomes a primary shorthand for how the market is weighing scale against ongoing losses.
Relative value flags lean supportive for the bull case. The P/S of 0.1x is described as good value against the US Interactive Media and Services industry average of 0.9x and also compared with the narrower peer group average of 0.8x. Internal fair value work suggests an estimated fair P/S of 0.6x, which is materially higher than where the stock is trading today and is cited as a level the ratio could feasibly migrate toward if sentiment and fundamentals stay aligned with current forecasts.
Explore the SWS fair ratio for FuboTV.
Result: Price-to-Sales of 0.1x (UNDERVALUED)
Still, FuboTV carries clear risks, including ongoing net losses of US$55.06m and a 5 year shareholder return that has fallen about 96%.
Find out about the key risks to this FuboTV narrative.
Another View on FuboTV Using Our DCF Model
That low 0.1x P/S ratio presents FuboTV as very inexpensive on a sales basis. The SWS DCF model provides a similar perspective, with an estimated future cash flow value of $89.93 per share versus the current $10.91 price, which appears heavily undervalued. The key question is whether those cash flow assumptions will prove realistic.
Look into how the SWS DCF model arrives at its fair value.
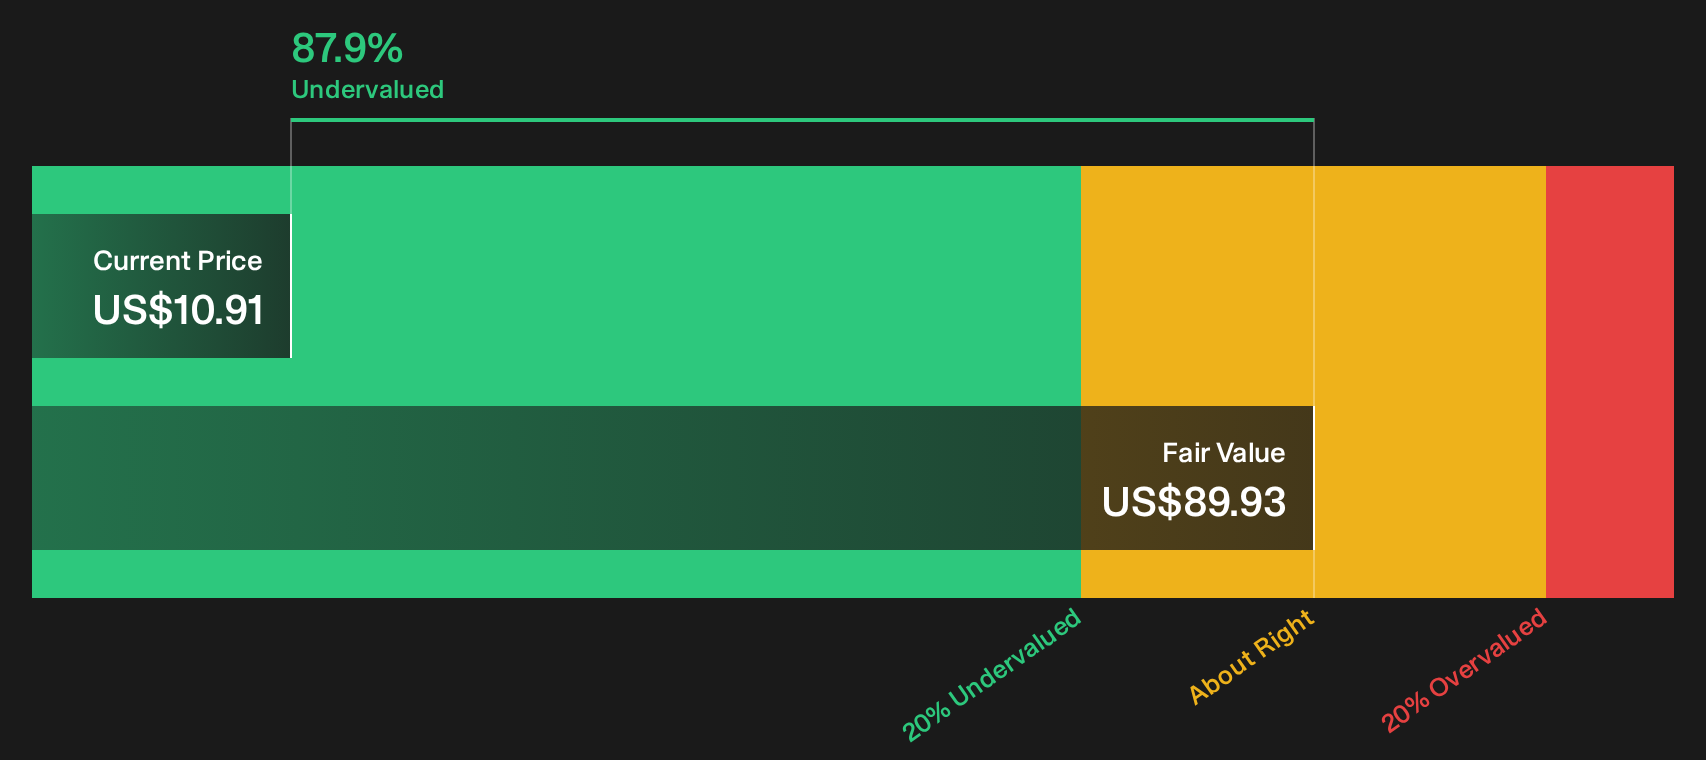
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FuboTV for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on FuboTV so far. If you want to move quickly and build your own conviction, weigh both the 4 key rewards and 2 important warning signs.
Looking for more FuboTV sized opportunities?
Want more ideas beyond FuboTV? Use a focused screener to quickly surface stocks that better fit your risk tolerance, time horizon, and financial goals.
- Target quality at a discount by scanning the 34 high quality undervalued stocks that couple stronger fundamentals with more conservative pricing.
- Prioritise resilience by reviewing the list of solid balance sheet and fundamentals (22 results) so potential downturns hit your watchlist less harshly.
- Hunt for future leaders early by checking the 16 high quality undiscovered gems before wider markets start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com