
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Certara Stock Is Up 5.0% What's Changed After Software Growth And Job Cuts
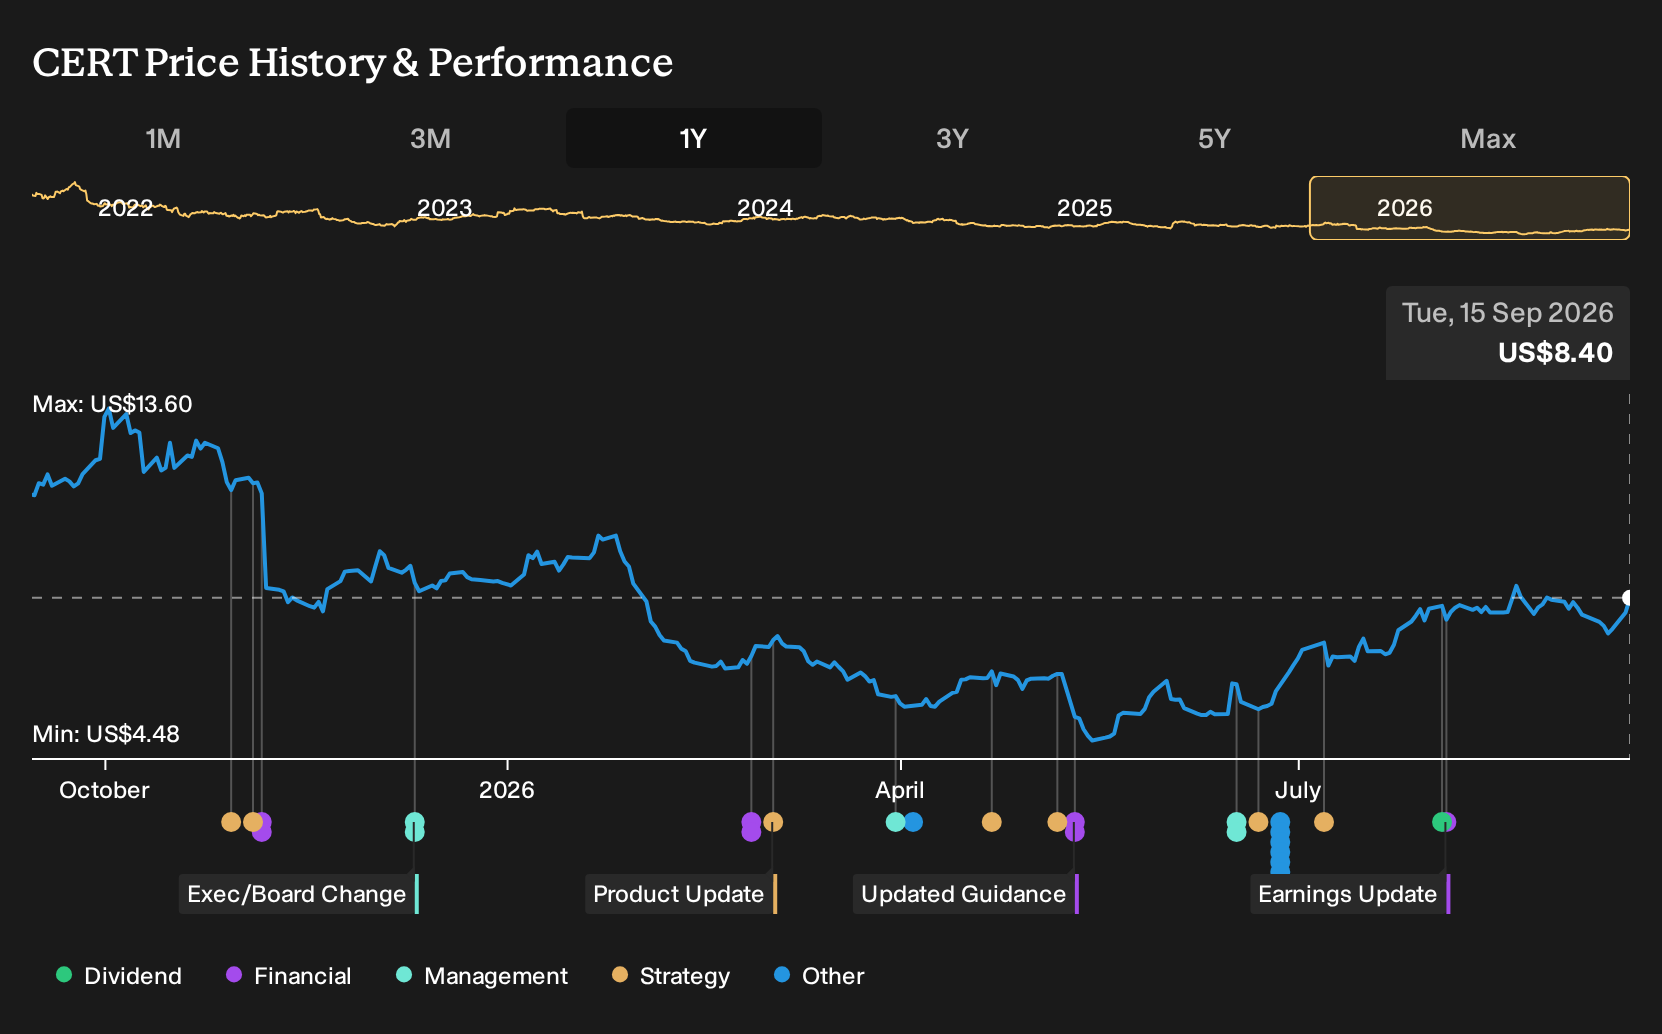
- Certara reported second quarter 2026 results with software revenue up 4%, software bookings up 9%, a net loss of US$6.1 million, a roughly 5% workforce reduction completed, and an extra US$50 million added to its share repurchase program.
- The combination of cost cuts, a higher buyback authorization, and growth in software activity highlights management’s push to reshape Certara around higher margin, recurring software income after selling its Regulatory and Medical Writing division.
- We will now assess how Certara's investment narrative is affected by workforce reductions alongside rising software revenue and bookings momentum.
Certara Investment Narrative Recap
To own Certara, you need to be comfortable with a story that leans heavily on recurring software, regulatory acceptance of biosimulation tools, and steady pharma adoption rather than rapid top line expansion. The latest quarter shows that software revenue and bookings are moving in the right direction while the overall business still reports a net loss of US$6.1 million.
The near term hinge point is whether software bookings momentum holds up as the firm trims about 5% of its workforce and finishes reshaping around higher margin offerings. Execution risk sits around pharma budget discipline, the pace of AI enabled platform uptake, and whether cost cuts slow product development or customer support.
The fresh authorization of an extra US$50 million for share repurchases is the clearest new signal in this update. It comes alongside modest software growth, a divestiture of lower margin activities, and ongoing losses. Investors are effectively being asked to assess whether Certara’s cash generation and balance sheet can comfortably support both product investment and buybacks.
For catalysts, the buyback interacts with earlier drivers such as Simcyp’s European Medicines Agency qualification and the planned AI enabled MIDD and CertaraIQ QSP launches. If those offerings keep attracting usage and support bookings, repurchases could incrementally increase per share exposure to any future earnings improvement. However, any stumble in adoption or large pharma spending would leave the business carrying both restructuring costs and capital return commitments.
Certara's narrative projects US$421.7 million revenue and US$15.8 million earnings by 2029. This implies fairly flat yearly revenue trends over the next few years and an earnings increase of about US$38.3 million from a loss of US$22.5 million today.
Uncover why Certara's fair value indicates a 3% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One alternate view focuses on Certara’s earnings potential rather than its software buzz. The most pessimistic analysts were modeling revenue of about US$398.5 million and earnings of roughly US$30.0 million by 2029, yet still saw downside. That gap in expectations shows how wide opinions can be, so explore these forecasts yourself before reacting to the latest quarter.
Explore 2 other Certara fair value estimates, including one that suggests as much as 17% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Certara research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Certara. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Certara's overall financial health at a glance.
Looking for more investment ideas beyond Certara?
If Certara has sharpened your focus on quality and risk, you can use that same lens to scan a wider opportunity set with the Simply Wall St Screener.
- If capital preservation sits high on your list, start with a curated 11 resilient stocks with low risk scores that keeps overall risk scores in check while still targeting equity upside.
- If resilient balance sheets matter most to you, narrow the field to a focused list of solid balance sheet and fundamentals (22 results) that already clears tough fundamental filters.
- If you want to cast a wider net for under followed opportunities, sort through a hand picked 16 high quality undiscovered gems that pairs quality metrics with quieter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com