
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
National Energy Services Reunited (NESR) Stock Looks Fully Priced After Its 5.4x Run
National Energy Services Reunited has delivered a very strong multi year share price run, and that kind of move naturally raises the question of whether the current tag is adequately backed by its earnings power. With the stock now well above where it traded a few years ago, the focus turns to what the business is actually producing in profit terms.
- Over the past 3 years the share price has gained about 5.4x, which puts real pressure on the earnings story to justify how far the valuation has moved.
- The business model is closely tied to providing oilfield services, so margins, contract quality and cash conversion can be crucial for judging how much of today's earnings profile is durable.
- There is a second opinion on National Energy Services Reunited worth weighing. See what analysts think National Energy Services Reunited's shares could be worth.
The stock's next move may depend on whether National Energy Services Reunited's current earnings are strong and consistent enough to support where the market is pricing it today.
If you want to stress test the same earnings question that hangs over National Energy Services Reunited against a broader field, take a look at 34 high quality undervalued stocks.
Is National Energy Services Reunited Fairly Priced on Earnings?
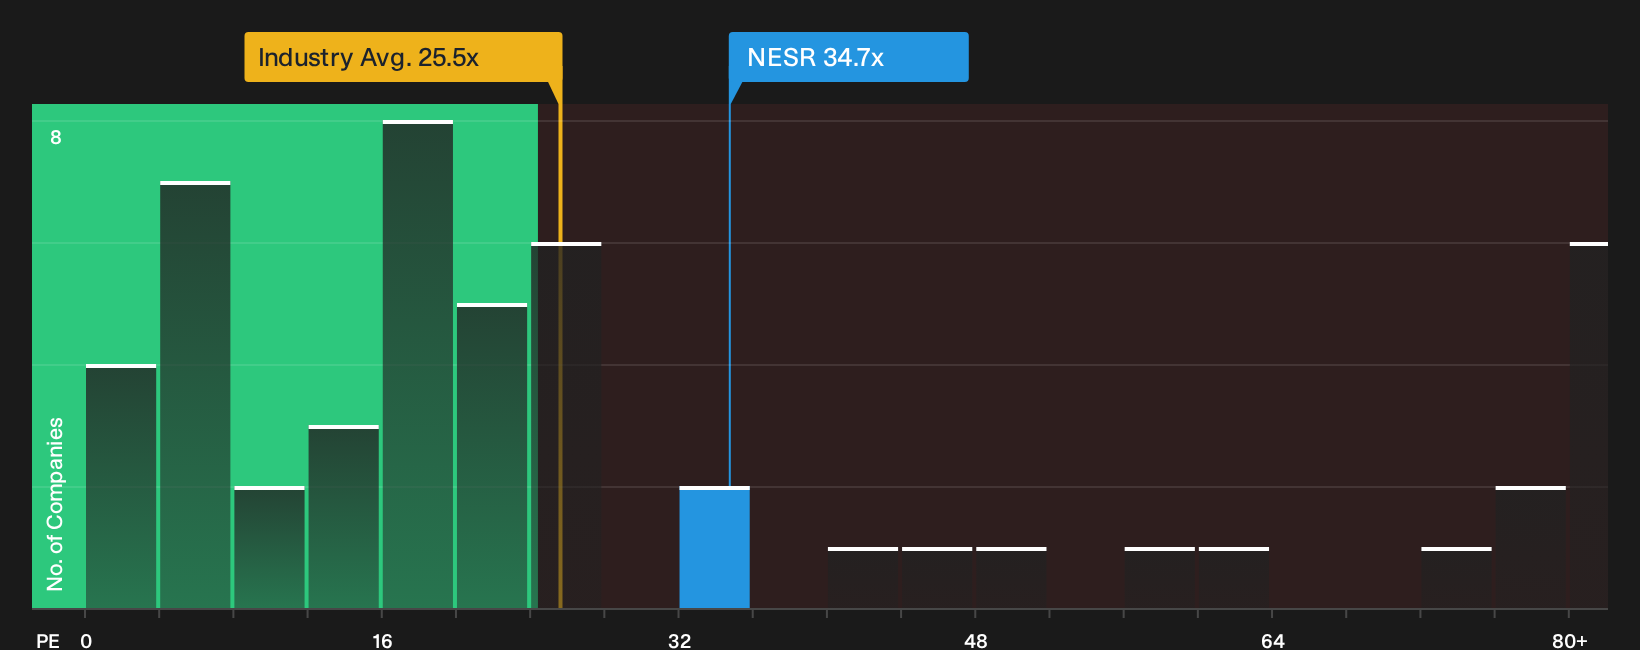
The P/E ratio is a useful starting point for National Energy Services Reunited because earnings are a key driver for how this oilfield services operator is valued. The stock trades on a P/E of 34.7x, which is above the Energy Services industry average of 25.5x. Compared with a peer group average of 60.0x, the multiple looks more moderate, so the market is not pricing it at the very top of the sector range.
A tailored fair multiple that blends National Energy Services Reunited's sector, profitability profile and risk comes out a little below the current P/E, which suggests the shares are roughly fully valued on this yardstick rather than clearly cheap or expensive. For an investor, that means the appeal of the current tag rests on how confident you are that the present earnings base can be sustained and that the business can justify a premium to the broader industry over time. Explore the numbers behind National Energy Services Reunited's P/E valuation.
The National Energy Services Reunited Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation question for National Energy Services Reunited leaves off by explaining which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or less than it is today. Each narrative treats National Energy Services Reunited's fair value as a specific thesis about the business that you can revisit over time, and they are available on the stock's Community page.
One of the top community narratives on National Energy Services Reunited: 20% undervalued
"Heavy macroeconomic, geopolitical, and industry shifts threaten NESR's contract stability, cash deployment, and long-term competitiveness versus larger, more technologically advanced rivals..."
Discover why this Narrative puts National Energy Services Reunited at 20% undervalued.
National Energy Services Reunited investors still have one more angle to check
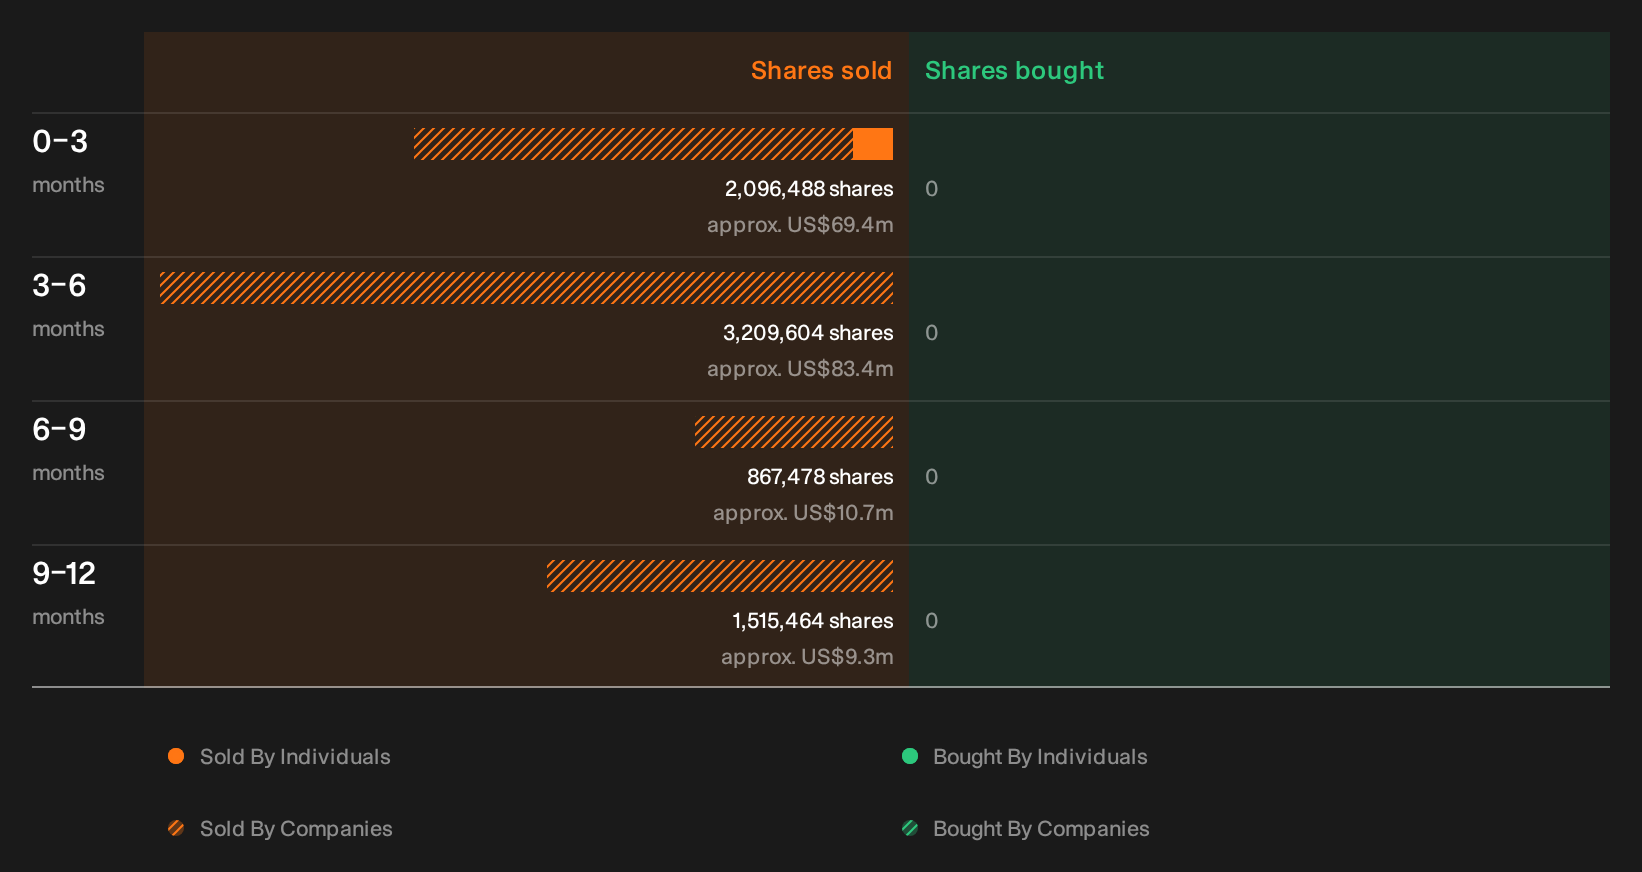
Price and earnings only tell part of the story for National Energy Services Reunited, because recent trading by key insiders can add a very different layer to the risk picture. See the recent insider selling flagged for National Energy Services Reunited.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com