
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Owens Corning (OC) Could Change Following Weaker Earnings Outlook
- Owens Corning faces investor scrutiny as upcoming earnings per share of about $3.20 and anticipated revenue sit below last year’s levels, which points to pressure on near term profitability.
- The tension between softer near term earnings expectations and ongoing investment in higher margin building materials highlights a gap between current business pressure and longer term potential.
- We will now look at how Owens Corning’s weaker near term earnings outlook could reshape the existing investment narrative around the business.
Contrast Owens Corning’s pressure on near term earnings with other building-related businesses that analysts see as mispriced by scanning our hand picked list of 34 high quality undervalued stocks.
Owens Corning Investment Narrative Recap
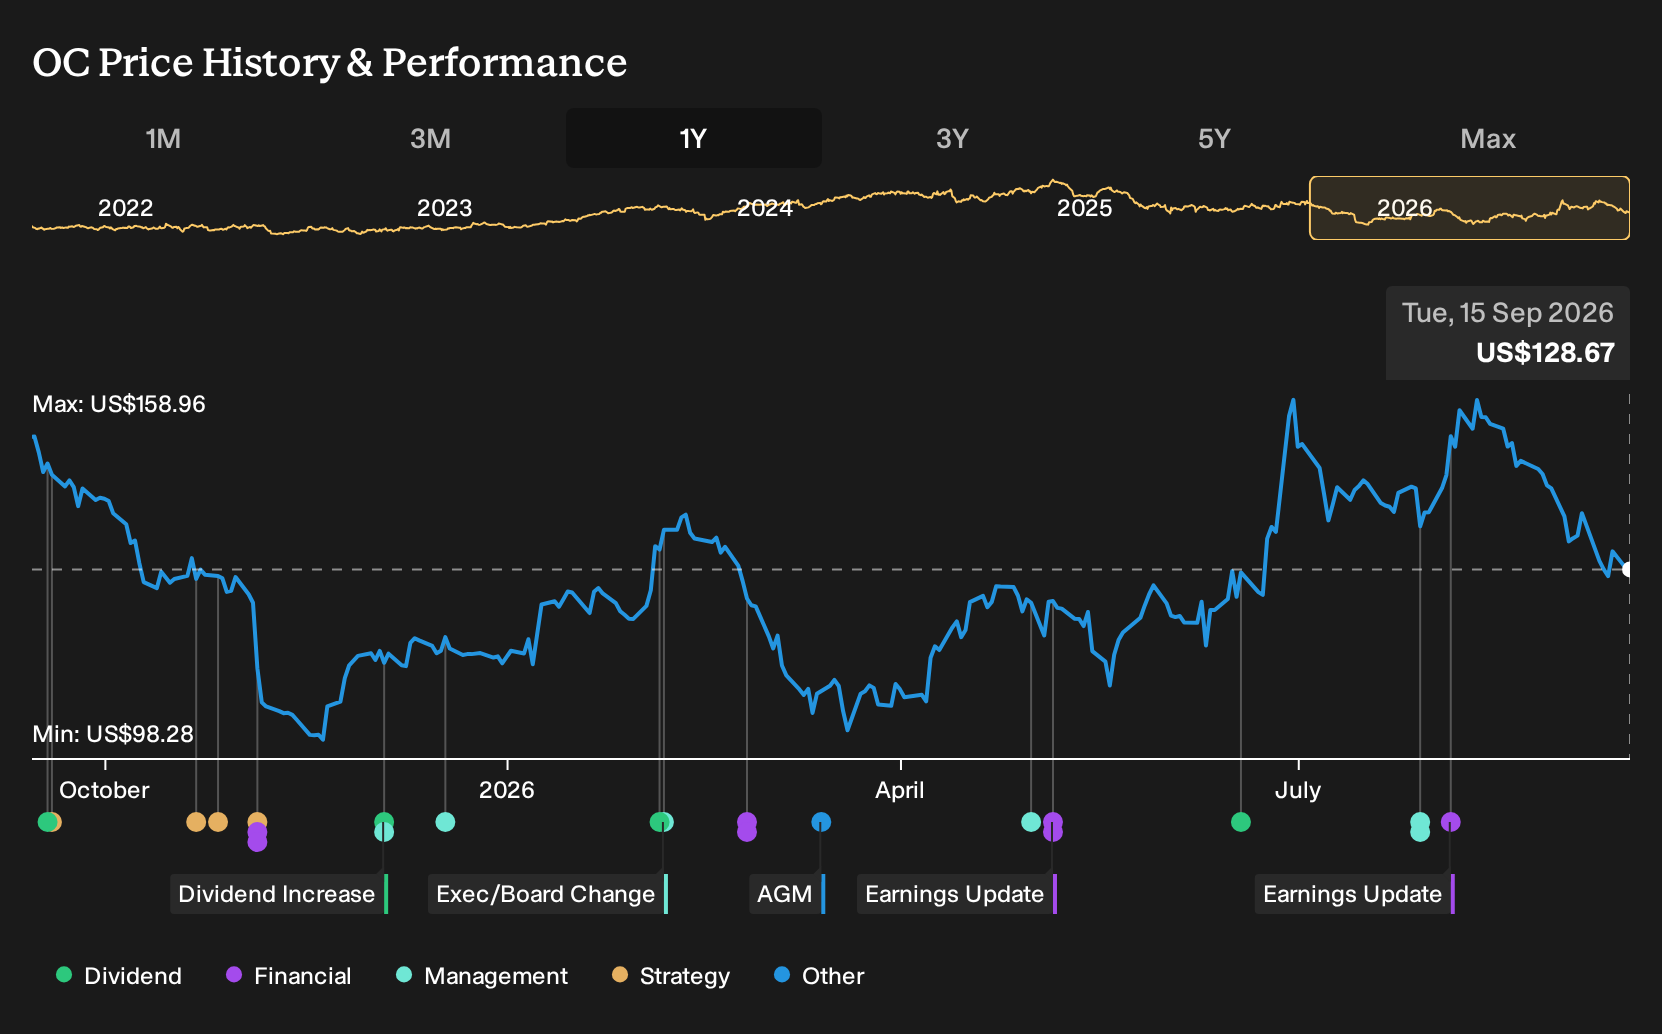
Owens Corning is essentially a bet that demand for insulation, roofing and doors tied to repair, remodel and nonresidential projects will be steady enough for its higher margin product mix and capacity investments to matter. The near term story now revolves around softer EPS and revenue expectations, while the share price has already fallen about 14.7% over the past month.
The key near term catalyst remains execution on those higher margin building materials and cost efficiencies across Roofing, Insulation and Doors. The biggest operational risk is still weak US and European housing and construction activity, including oversupplied insulation and roofing markets and potential pricing pressure, which the latest earnings softness does little to resolve.
The most relevant update tied to this pullback is the reset in upcoming quarterly expectations, with forecast EPS around US$3.20 on lower revenue than a year ago. That guidance frames the market’s concern that Owens Corning is hitting a cooler patch in demand just as it absorbs past expansion and integration work.
In the short term, the question is whether those earnings headwinds interrupt the longer running catalysts that analysts have focused on, such as the mix shift toward higher margin categories, cost savings from recent deals in Doors and new capacity aimed at energy efficient building products. If execution on those projects stays on track, this quarter’s weaker print is more of a timing issue than a change in the fundamental thesis, although it underscores how sensitive the business is to construction cycles and pricing in over supplied segments.
Owens Corning’s current revenue outlook in analyst models points to annual top line growth of 3.7%, with earnings expected to move from a loss of $429.0 million today to $1.9 billion by 2029. This represents an earnings increase of about $2.3 billion over that period and underpins consensus forecasts for roughly $11.0 billion of revenue and $1.9 billion of profit in 2029.
Uncover why Owens Corning's fair value indicates a 36% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Owens Corning, the most cautious analysts focus on the risk that its big capital projects take longer to fill. Before this update, the bearish group was modeling about US$10.9b of revenue and US$1.6b of earnings in 2029, which supports a lower price target and a clearly more restrained storyline. These estimates were set before the latest earnings expectations, so it is possible that both the upbeat and more restrained narratives could shift as new information lands.
Explore 4 other Owens Corning fair value estimates, including one that suggests as much as 7% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Owens Corning research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Owens Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Owens Corning's overall financial health at a glance.
Looking For More Owens Corning Alternatives?
If this Owens Corning update has you rethinking concentration risk, broaden your watchlist using the Simply Wall St Screener to surface other ideas that fit your style and risk tolerance.
- If you want potential mispricings backed by stronger fundamentals, start with a curated group of 34 high quality undervalued stocks that score well on both quality and valuation.
- For income focused investing, balance yield and staying power by scanning a focused set of 6 dividend fortresses that clear a 5%+ hurdle.
- When capital preservation matters most, concentrate on resilience by working through a short list of 11 resilient stocks with low risk scores that screen well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com