
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Power Assets Holdings (SEHK:6) Cools Near Term As Valuation Questions Come Into Focus
Power Assets Holdings (SEHK:6) has drawn investor attention after its stock closed at HK$60.15, with recent returns mixed over the past week, month, and past 3 months, yet materially stronger over longer periods.
Recent trading shows that momentum in the Power Assets Holdings share price has cooled in the near term, yet the stock still carries a 7.03% 3 month share price return and a 22.30% 1 year total shareholder return. This points to longer term strength despite short term hesitation.
Scan how Power Assets Holdings compares with other utilities that combine income potential with defensiveness by reviewing our curated list of 159 dividend fortresses.
The recent pullback in Power Assets Holdings after a strong year raises a simple tension. Are you seeing sentiment cool, or a price that still trails what the underlying assets justify next on valuation.
Price-to-Earnings of 7.2x: Is it justified?
On simple earnings terms, Power Assets Holdings trades on a P/E of 7.2x. This sits below the wider Hong Kong market yet above its own estimated fair P/E of 5.1x. The share price of HK$60.15 reflects that mix of apparent value against peers and a premium to the level suggested by the fair ratio model.
P/E compares what investors are paying for each unit of current earnings. For a mature utility group with assets across Hong Kong, the UK, Australia and other regions, this lens helps you see how the market prices relatively stable profit streams versus other listed businesses.
The current 7.2x multiple is materially lower than the Asian Electric Utilities industry average of 13.6x and also below the 15.7x peer average. This signals the stock is priced more conservatively than many regional and direct comparables. At the same time, the fair P/E estimate of 5.1x implies the market is assigning a richer tag than that regression based level could move toward if sentiment softened.
Explore the SWS fair ratio for Power Assets Holdings.
Result: Price-to-Earnings of 7.2x (ABOUT RIGHT)
Still, two clear risks sit in the background. Annual net income has fallen 34.6%, and revenue growth near 0% leaves little cushion if sentiment reverses.
Find out about the key risks to this Power Assets Holdings narrative.
Another view on Power Assets Holdings valuation
The P/E picture only tells part of the story for Power Assets Holdings. Our DCF model points the other way, with an estimated future cash flow value of HK$14.66 per share versus the current HK$60.15 price. On that measure, the stock screens as heavily overvalued. Which yardstick do you trust more for a regulated utility with long lived assets?
Look into how the SWS DCF model arrives at its fair value.
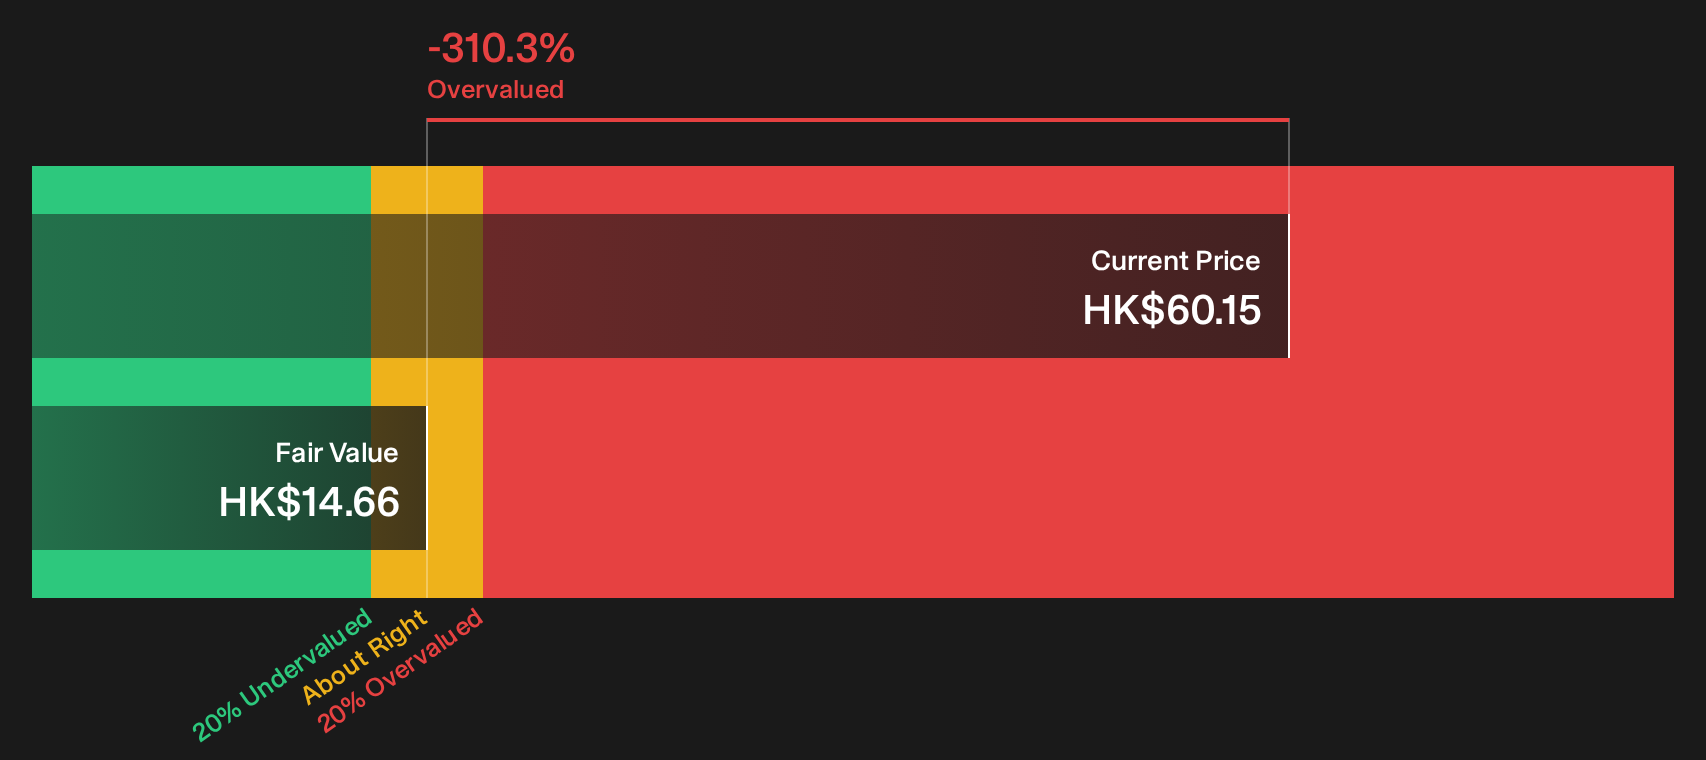
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Power Assets Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Power Assets Holdings often create the most interesting opportunities. Check the numbers yourself, weigh the trade offs, then review the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Power Assets Holdings?
If Power Assets Holdings has you thinking harder about value, do not stop here. Broader ideas often come from scanning structured stock lists.
Use the Simply Wall St screener to quickly compare other opportunities and avoid relying on a single ticker.
- Target resilient balance sheets by reviewing our list of solid balance sheet and fundamentals (195 results) that highlights companies pairing financial strength with fundamental support.
- Hunt for quality at a discount through the 195 high quality undervalued stocks and see which businesses the numbers suggest are priced below their fundamentals.
- Spot future standouts before the crowd by checking the 622 high quality undiscovered gems that surfaces under-followed stocks with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com