
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Orion Oyj (HLSE:ORNBV) Starts A Share Buyback, Does It Look Fully Valued?
Orion Oyj launches targeted share repurchase program
Orion Oyj (HLSE:ORNBV) has started buying back its own class B shares after a shareholder mandate, opening a fresh capital allocation signal that current and prospective investors may wish to examine closely.
Orion Oyj’s class B shares change hands at €79.4, with the stock giving up a little ground over the past week but still posting a 2.6% 1 month share price gain and a 25.4% year to date share price return, alongside a 5 year total shareholder return of 166.6% that points to strong long term momentum even before factoring in the fresh buyback signal.
Spot opportunities beyond Orion Oyj by comparing its buyback move with a curated set of companies in the list of solid balance sheet and fundamentals (195 results).Orion Oyj now trades slightly above the average analyst target yet screens at a sizeable discount to some fair value estimates. Is the fresh buyback a sign the market’s caution has gone too far, or not far enough?
Most Popular Narrative: 4% Overvalued
Analysts who follow Orion Oyj closely now anchor their fair value estimate around €76.67, which sits a little below the recent €79.4 share price and frames the new buyback as happening slightly above that narrative benchmark.
Base business growth of 22% in the first nine months of 2025, supported by a 71% increase in underlying Innovative Medicines sales and strong Generics and Consumer Health performance, suggests that if this momentum continues it could push revenue and operating profit higher than implied by a flat share price view.
See why 5 investors see Orion Oyj as 4% overvalued.
The most followed view uses a 6.11% discount rate and ties Orion Oyj’s fair value to forecasts that point to €2.6b of revenue and €747.9m of earnings by 2029, with a future P/E of 17.3x compared with a current multiple closer to 19.6x. That framework treats today’s quote as slightly ahead of the €76.67 fair value line, yet still within a band where long term revenue growth near 8.4% a year and a 28.5% profit margin can support the current market cap if those assumptions hold.
Result: Fair Value of €76.67 (OVERVALUED)
Still, Orion Oyj’s story could change quickly if oncology trials such as ODM 212’s Phase 2 readout or Nubeqa-related milestones land differently than consensus expects.
Find out about the key risks to this Orion Oyj narrative.
Another View on Orion Oyj’s Valuation
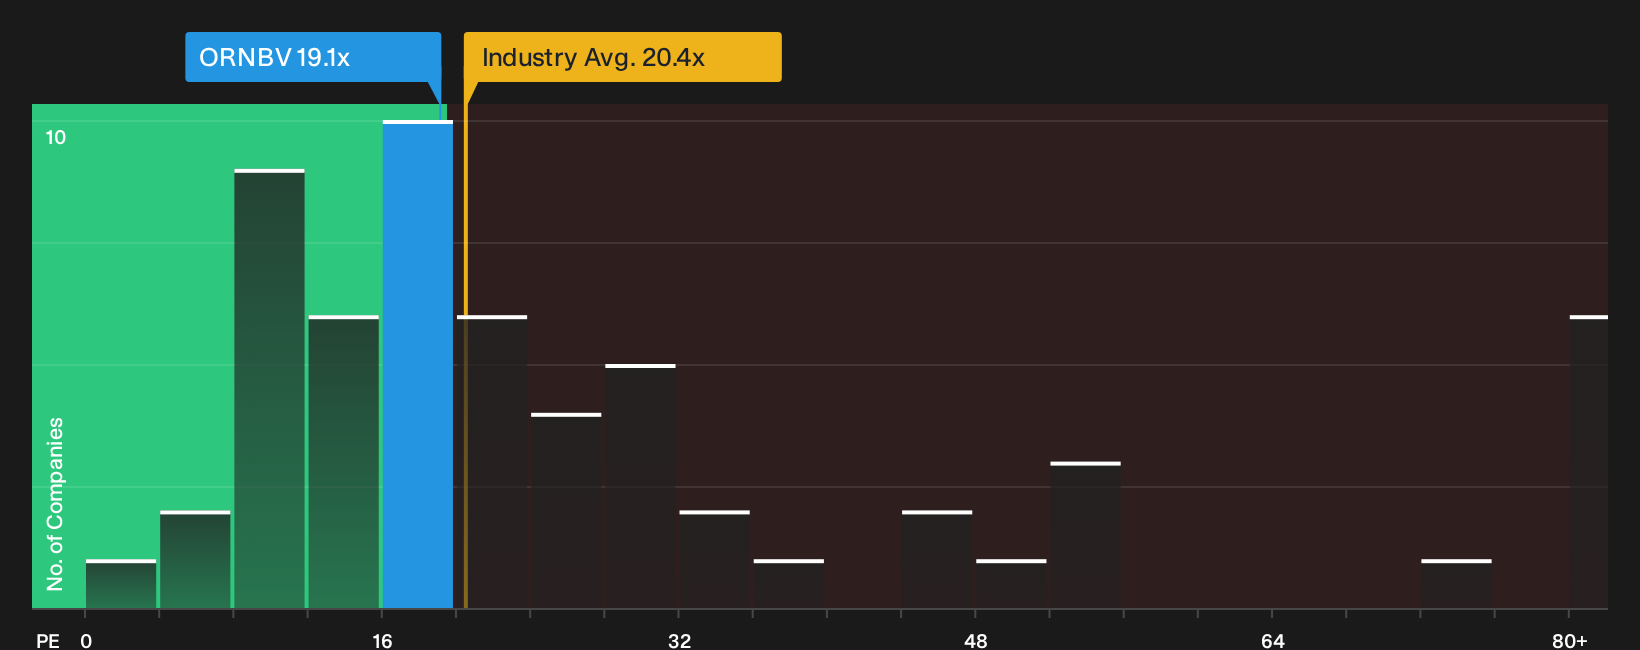
Analyst targets suggest Orion Oyj is a little ahead of fair value around €76.67, yet its P/E of 19.1x sits well below peers at 38.7x in Europe. That gap points to either a margin of safety or a sign the market is more cautious than the headline multiple implies.
For investors comparing Orion Oyj with similar pharmaceutical stocks, this earnings multiple trade off raises a simple question. Is the lower P/E a useful entry filter, or a warning that others see risks the ratio does not capture yet? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messages around Orion Oyj leave you unsure, that is a signal to look directly at the underlying numbers and context. Move quickly from headline impressions to your own assessment by reviewing its 4 key rewards.
Looking for more Orion Oyj investment ideas?
If Orion Oyj has your attention, do not stop here. Use the Simply Wall Street Screener to compare other companies, sharpen your watchlist, and pressure test your next move.
- Chase value opportunities by scanning for companies that combine quality fundamentals with appealing valuations using the 195 high quality undervalued stocks.
- Prioritise resilience first and hunt for businesses with stronger financial footing through the 102 resilient stocks with low risk scores.
- Target income potential by zeroing in on companies that offer higher yields with the 159 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com