
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Clean Harbors (CLH) And The Infrastructure Story As Valuation Still Looks Reasonable
Clean Harbors (CLH) has drawn fresh attention after recent trading left the stock down about 1% over the past month but up roughly 11% in the past 3 months.
Viewed over a longer stretch, Clean Harbors has been on a strong run. The year-to-date share price return is 30.71% and the 1-year total shareholder return is 35.17%, while the 3-year and 5-year total shareholder returns of 87.85% and 220.19% suggest earlier investors have already seen substantial compounding.
Scan beyond Clean Harbors and see how it compares to other hand picked industrials and services stocks in the list of solid balance sheet and fundamentals (22 results).
Clean Harbors has already delivered strong multiyear gains and a sharp run this year, yet the stock still trades below some estimated value marks. Is most of the upside already realized, or does the current valuation still leave room?
Most Popular Narrative: 9% Undervalued
Clean Harbors last closed at $318.20, while the most followed narrative on the stock suggests a fair value around $350. That gap is not huge, but it is meaningful enough for investors who care about paying roughly the right price for a long duration compounder story.
The story is not simply that Clean Harbors cleans up hazardous waste.
The deeper investment thesis is:
Modern society keeps producing hazardous waste, and somebody has to safely collect it, transport it, treat it and dispose of it. Clean Harbors owns one of the most difficult-to-replicate infrastructure networks required to do that.
See why 2 investors see Clean Harbors as 9% undervalued.
According to prajeeshprathap, that infrastructure focused narrative points to a fair value of $350 per share, which is about 9% above the recent price. The narrative uses a discount rate of 7.236%, along with assumptions for revenue expansion and a profit margin of 7.03%, to estimate long term cash generation and then discount it back to today. Taken together with the conclusion that Clean Harbors is trading below this assessment of worth, it frames the recent share price performance as part of a longer running compounding story rather than a short term spike.
Result: Fair Value of $350 (UNDERVALUED)
Still, the Clean Harbors narrative could be pressured if regulators slow approvals for new facilities or if weaker industrial activity reduces waste volumes and pricing power.
Find out about the key risks to this Clean Harbors narrative.
Another Look At Clean Harbors Using Earnings Multiples
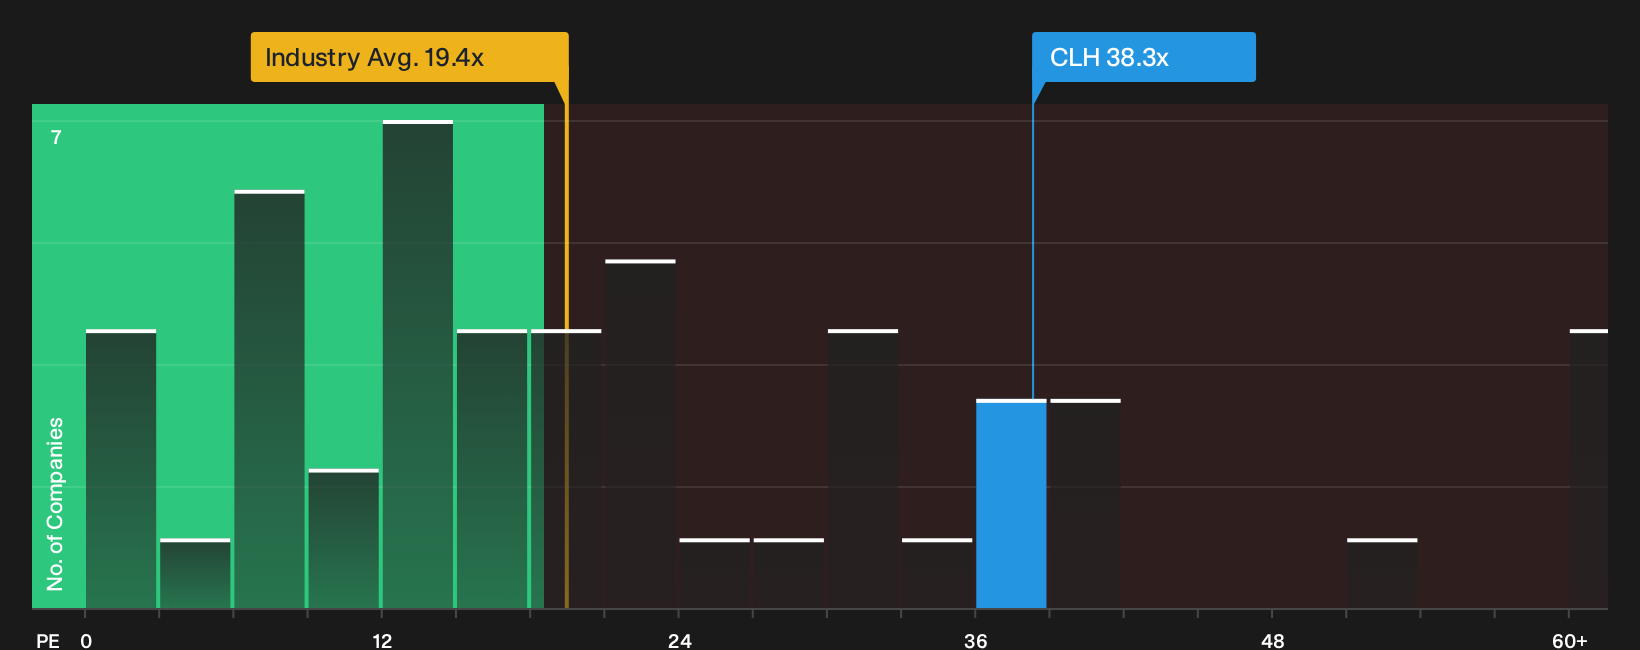
That 9% undervalued narrative for Clean Harbors meets a very different message once you line it up against the current P/E. The stock trades on 38.3x earnings, which is much richer than the US Commercial Services group at 19.8x and above the peer average of 28.4x.
Our fair ratio estimate of 21.8x is also far below the current multiple. That gap suggests the market is already paying a premium for the hazardous waste story, so any slip in execution or enthusiasm could compress the valuation. Is this a quality premium you are comfortable paying, or a multiple that leaves little room for disappointment?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Clean Harbors so far. If you want to move quickly and make your own call, balance both sides of the story by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Clean Harbors?
Do not stop with one opportunity. Use the Simply Wall Street Screener to line up fresh candidates, compare them side by side and keep your watchlist evolving.
- Target potential bargains by scanning for quality companies that look mispriced using the 34 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies with generous payouts through the 6 dividend fortresses.
- Dial down volatility by hunting for financially robust businesses in the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com