
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Upstart Holdings (UPST) Could Be 37% Below Fair Value On Cautious Earnings Sentiment
Upstart Holdings (UPST) has been back in focus after recent coverage highlighted a split screen for investors. Earnings and revenue are projected to grow, yet a Zacks Rank #4 (Sell) signals cautious sentiment.
Recent coverage around Upstart Holdings has landed against a weak tape for the stock, with the share price at $25.28 after a 1-day share price return of down 3.14% and a 30-day share price return of down 16.92%, while the 1-year total shareholder return has fallen 62.36% and points to fading momentum despite discussion of improving earnings power.
Compare Upstart Holdings' cautious sentiment and projected earnings with a curated set of potential opportunities in 34 high quality undervalued stocks that aim to pair growth with balance sheet strength.
For Upstart Holdings, a 62.36% one-year slide and projections for higher earnings tell very different stories. Is the recent selloff about weakening fundamentals, or is sentiment simply resetting the valuation bar?
Most Popular Narrative: 37% Undervalued
On the most followed narrative, Upstart Holdings screens as materially cheaper than an estimated fair value of about $40.13, compared with a last close of $25.28. That gap puts the focus on whether the lending platform can convert its underwriting model and product expansion into the kind of earnings power backing that estimate.
The implementation of Model 19, featuring the Payment Transition Model (PTM), has improved underwriting accuracy, which is likely to enhance loan approval rates and reduce default risks, positively impacting revenue and net margins.
Upstart's HELOC product growth, driven by conversion improvements, cross-selling, and state expansion, positions it well for future revenue growth and margins with the potential to leverage its strong relationships with banks and credit unions for cost-effective funding.
See why 141 investors see Upstart Holdings as 37% undervalued.
Result: Fair Value of $40.13 (UNDERVALUED)
Still, Upstart Holdings depends on its AI models holding up through credit cycles, and any funding constraints could quickly challenge the 37% undervalued narrative.
Find out about the key risks to this Upstart Holdings narrative.
Another View On Upstart Holdings: Expensive On Earnings
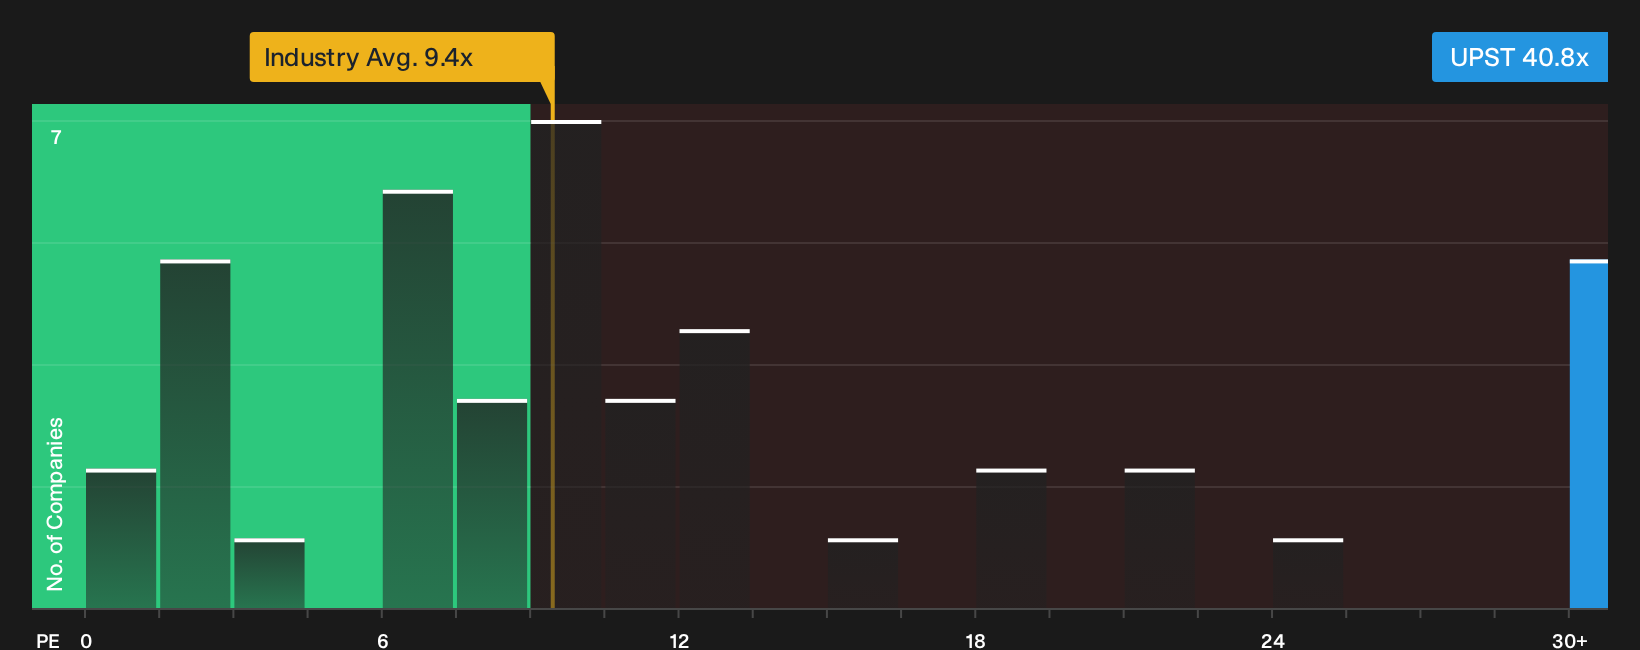
The fair value story for Upstart Holdings leans on future cash flows, yet the P/E tells a very different story. The stock trades on about 40.8x earnings, compared with roughly 9.4x for the US Consumer Finance sector and about 12.5x for peers, while the fair ratio sits near 42.3x.
That leaves Upstart Holdings priced well above the wider group on current earnings but close to its fair ratio. This hints at limited room for error. If sentiment turns or forecasts change, does this premium look like opportunity or valuation risk to you.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Upstart Holdings can feel like noise. Move fast, review the numbers and sentiment for yourself, then weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Upstart Holdings?
If Upstart Holdings has you thinking harder about risk, valuation, and timing, it may be useful to broaden your watchlist now with other potential setups before the market moves on.
- Target resilient cash flows and capital strength by scanning companies on the list of solid balance sheet and fundamentals (22 results).
- Look for potential mispriced quality where fundamentals and valuation both matter using the 16 high quality undiscovered gems.
- Prioritise stability and lower volatility profiles by focusing on the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com