
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Marqeta (MQ) Dropped, So What Is Behind The Latest Attention?
Marqeta (MQ) is in focus after mixed Q2 news, with a revenue beat to US$176 million and 17% year on year growth, but softer guidance that dragged on sentiment.
The softer outlook has fed into the share price, with Marqeta now at US$16.09 and a year-to-date share price return down 13.31%, while the 1-year total shareholder return has fallen 30.53%, despite a modestly positive 90-day share price return of 3.94% that hints at only tentative momentum.
See how Marqeta compares to other payment and fintech players currently under pressure by checking our curated list of 34 high quality undervalued stocks.
After that guidance hit and the share price reset, the key question is whether Marqeta still has meaningful upside ahead or whether most of the easy gains are already in the rear-view before you even look at valuation.
Most Popular Narrative: 22% Undervalued
On the most followed view of Marqeta, a fair value of $20.74 against the $16.09 close implies a sizeable valuation gap that hinges on how the payments platform scales globally and monetises its technology.
The completed TransactPay acquisition gives Marqeta full program management and EMI capabilities in Europe, enabling entry into larger enterprise opportunities, uniformity of service across North America and Europe, and easier multi-market expansion for clients. This unlocks new revenue streams, increases take rates, and improves earnings scalability.
See why 13 investors see Marqeta as 22% undervalued.
Result: Fair Value of $20.74 (UNDERVALUED)
Still, the entire Marqeta narrative leans heavily on a few large customers in a crowded card issuing market that could pressure pricing if competition intensifies.
Find out about the key risks to this Marqeta narrative.
Another View: Marqeta Looks Expensive On Sales
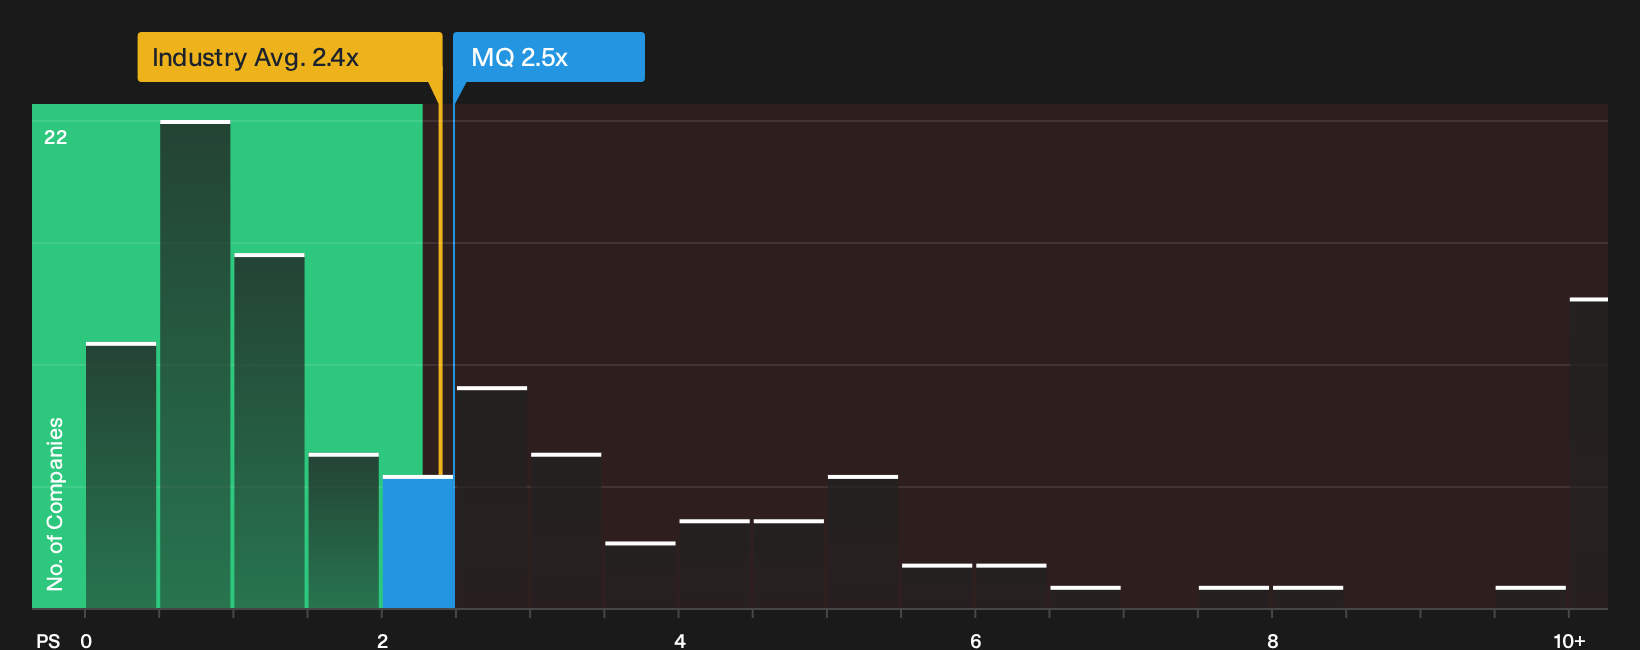
Marqeta might screen as 22% undervalued on that fair value estimate, but its P/S of 2.5x is higher than both peers at 0.9x and the US Diversified Financial average at 2.4x. The fair ratio sits at 2.3x, so anyone buying here is paying up. How comfortable are you with that premium?
To see how that premium lines up with the underlying numbers and sector peers in practice, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Marqeta is clearly split, with both concern and optimism in the mix. Move quickly to inspect the data, weigh the risk and reward tradeoff for yourself, and then ground your stance in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Marqeta?
If Marqeta has caught your attention, broaden your watchlist with other focused ideas that could sharpen your overall portfolio and highlight fresh opportunities.
- Explore potential yield by scanning companies with resilient payouts through the 6 dividend fortresses.
- Hunt for quality at a discount by reviewing the 16 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- Focus on stability by filtering for lower-risk profiles using the 11 resilient stocks with low risk scores before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com