
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
KPMG: China's smart wear market will reach 105.3 billion yuan in 2025, with a compound annual growth rate of 11%
The Zhitong Finance App learned that KPMG released the “2026 China Smart Wearables Market Insight Report”. According to the report, China's smart wear market has maintained rapid growth, from 69.5 billion yuan in 2021 to 105.3 billion yuan in 2025. The compound annual growth rate during the period reached 11%, close to the global level of 12.2%. Wristband devices are the most mature and largest core category. In the first quarter of 2026, the Chinese wristband market shipped 18.14 million units, an increase of 3.5% over the previous year, accounting for 38.6% of global wristband market shipments, continuing to maintain the position of the world's largest wristband device market.
Figure: China's smart wearable device market size and forecast, 100 million yuan
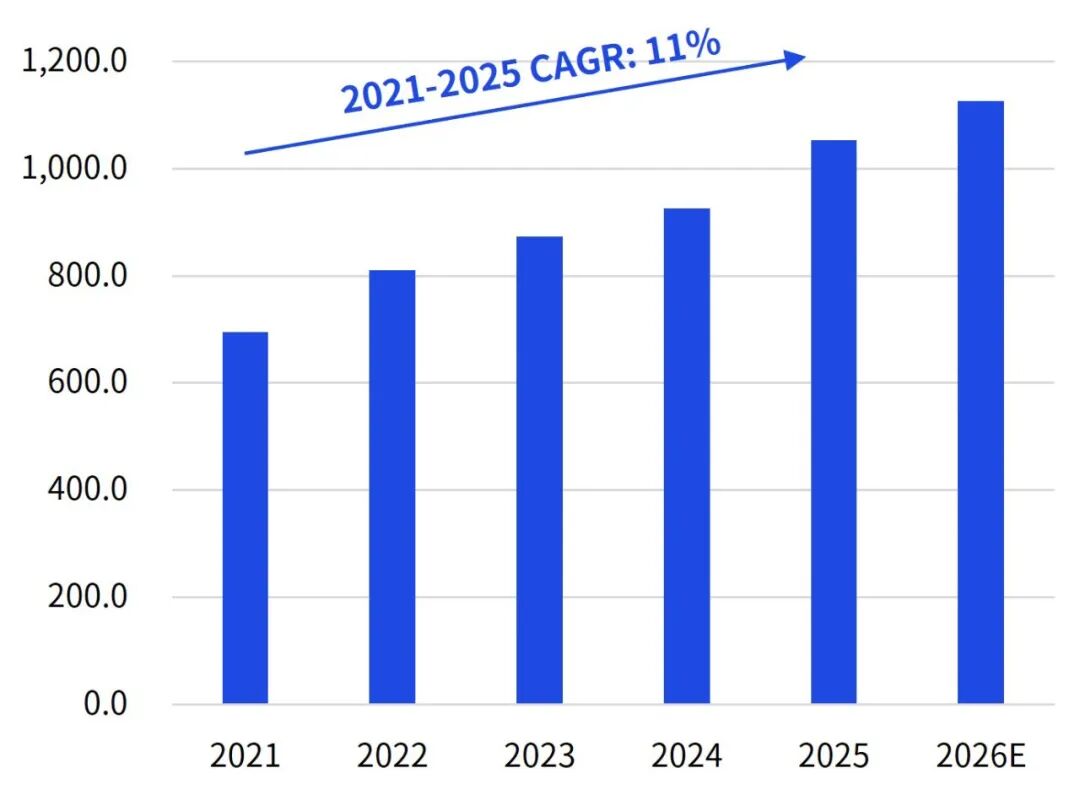
Data source: China Business Industry Research Institute2, KPMG analysis
The global smart wearable device market grew from 503.6 billion yuan in 2021 to 797.7 billion yuan in 2025, with a compound annual growth rate of 12.2%. North America is dominated by 39% of the market share, supporting the popularity of consumer-grade and medical-grade scenarios with a concentration of leading technology companies, high disposable income for residents, and advanced healthcare systems.
Figure: Global smart wearable device market size and forecast, 100 million yuan
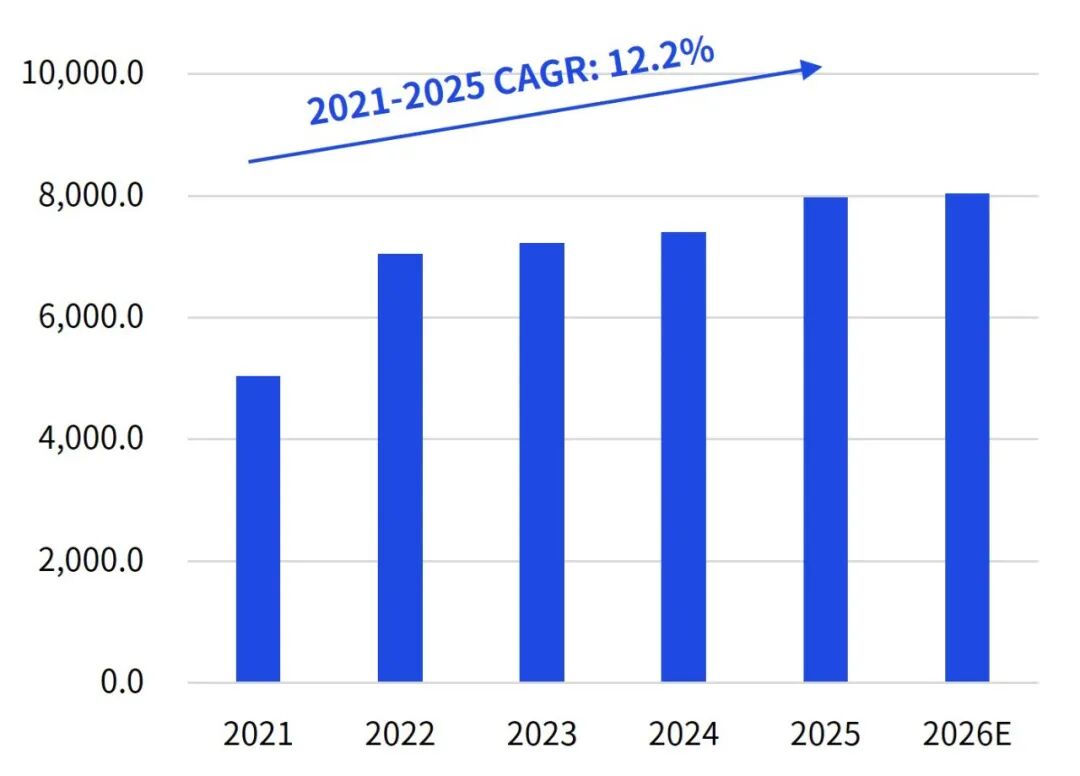
Data source: China Business Industry Research Institute2, KPMG analysis
China incorporates smart wearables into its national strategy and differentiates the layout of key cities. In 2025, the “Special Action Plan to Boost Consumption” incorporated smart wear into the country's strategy to boost domestic demand for the first time. Beijing focuses on “smart wearables+AI smart devices”, Shanghai invigorates the “smart wear+silver hair economy”, Guangzhou relies on the display industry to build characteristic industrial parks, and Shenzhen cultivates “popular terminals” such as AI glasses.
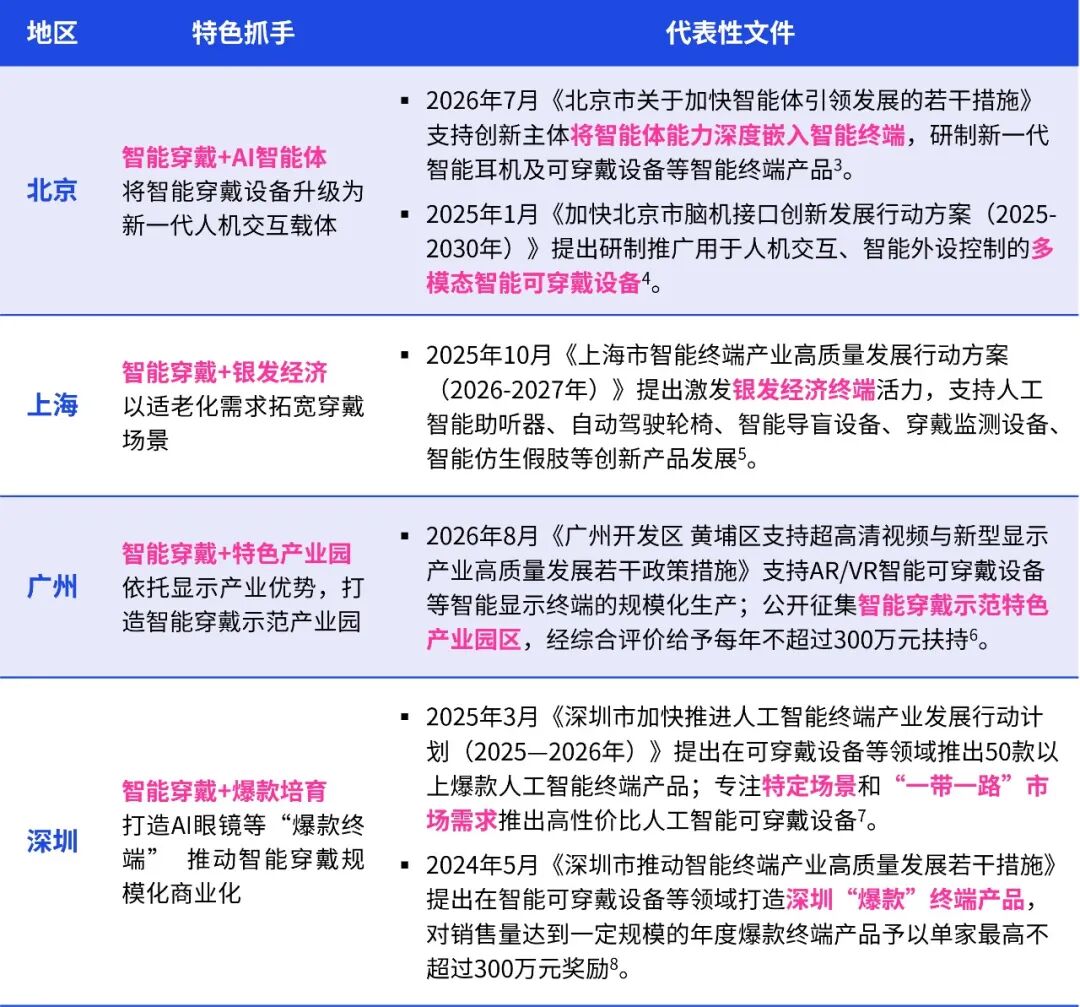
Analysis of China's smart wearable capital market
Investment and financing reached a record high in 2025, and continued to heat up in 2026. According to investment data, in 2025, there were 88 investment and financing incidents in China's smart wear industry. The total amount of disclosed financing reached 9.3 billion yuan, a record high, far exceeding the amount of financing in the previous three years. In 2026, the popularity of smart wear investment reached a new high. In the first half of 2026, the number of smart wearable financing cases reached 83, and the disclosed financing amount also exceeded the full year level of 2022, 2023 and 2024. The semi-annual financing amount was about 92.53% of the full year of 2025, reaching RMB 8.623 billion.
Figure: Financing amount and number of incidents for China's smart wear industry in 2020-2026, 100 million yuan, pen
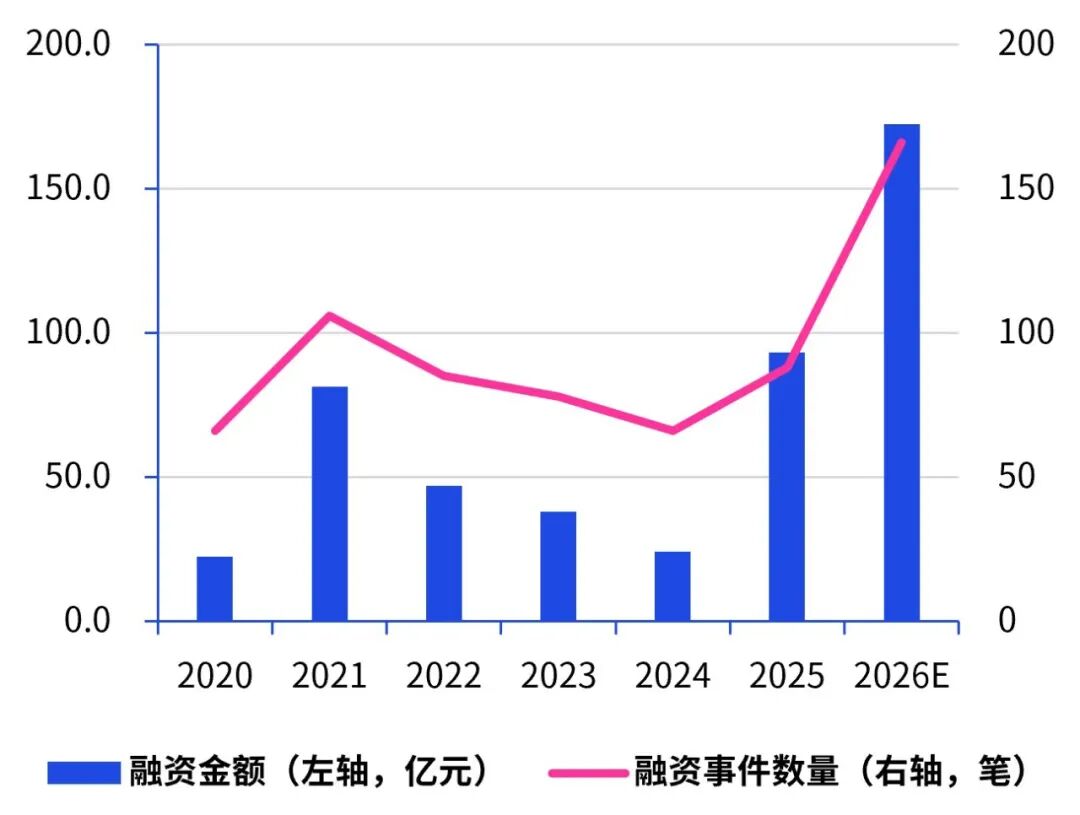
Data source: Investment data, KPMG analysis
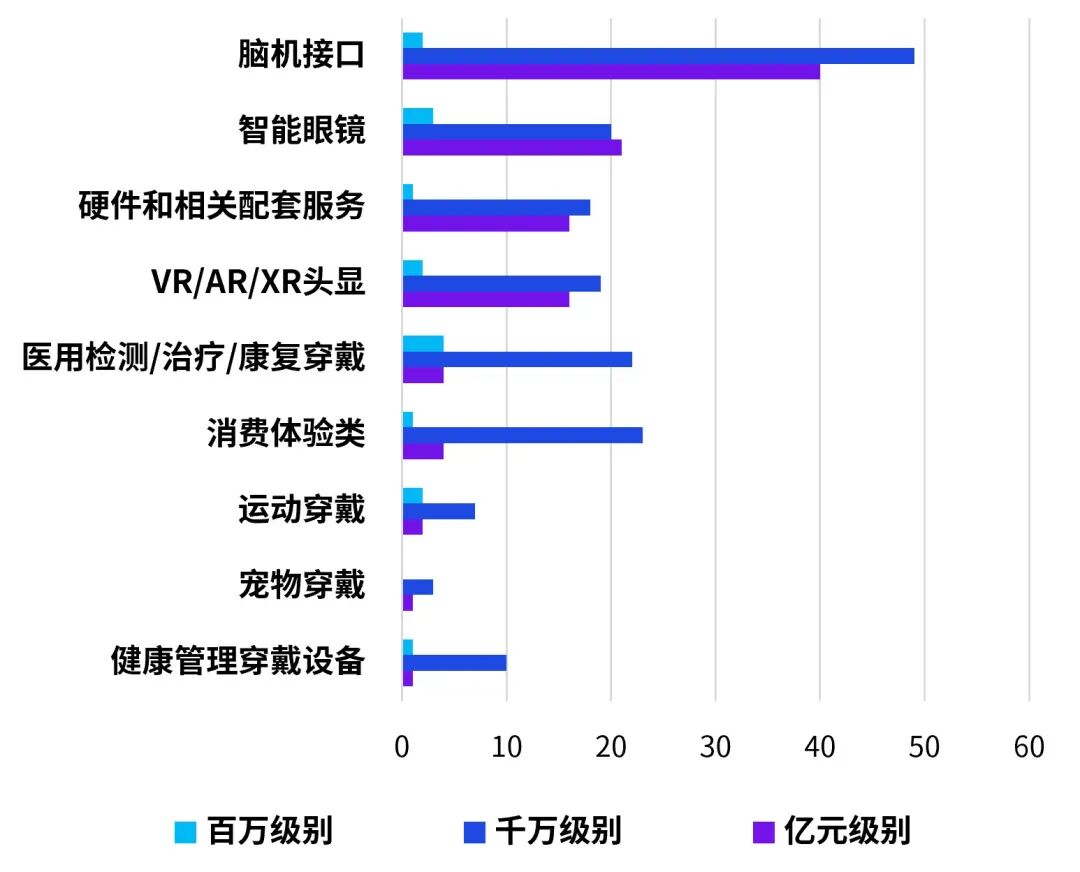
Brain-computer interfaces and smart glasses are leading the financing trend. Looking at the segment segment, the amount of financing at the 10 million level and 100 million yuan level in the fields of brain-computer interfaces, smart glasses, VR/AR/XR headsets, and hardware and related supporting services is almost flat, and is the main force attracting investment, while financing projects in the four major fields of consumer experience, medical testing/treatment/rehabilitation, health management, and sportswear are mainly concentrated at the 10 million level.
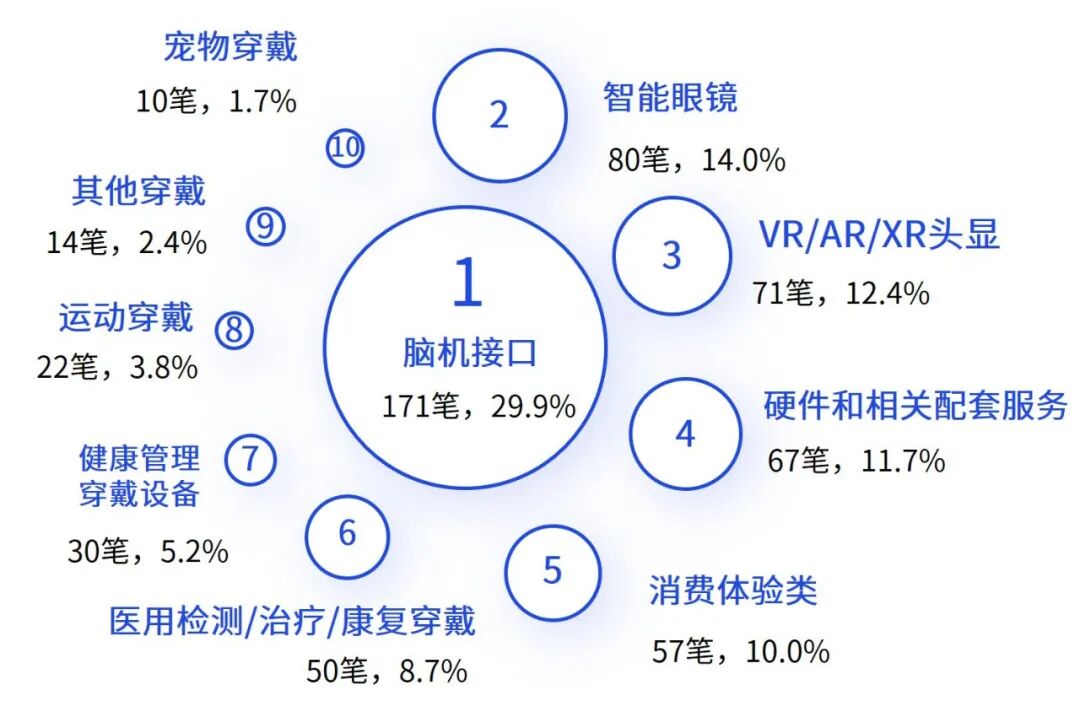
Judging from the number of financing incidents, the most popular smart wearable circuit is the brain-computer interface. The track had 171 financing events in 2020-2026H1, accounting for about 30%; followed by smart glasses, with 80 financing incidents, accounting for about 14%; VR/AR/XR headlines followed, with 71 financing incidents. Judging from the proportion of financing incidents, the share of brain-computer interfaces and smart glasses began in 2020, showing an overall steady growth trend, leading the smart wearable industry financing trend.
Figure: 2020-2026H1 financing levels for various tracks in China's smart wearable industry, pen
Data source: Investment data, KPMG analysis
Figure: Number and proportion of financing incidents for each track in 2020-2026H1, pen,%
Data source: Investment data, KPMG analysis
Looking forward to the future, the field of smart wear presents ten major trends
Trend 1
Localization: The advantages of supply chain innovation are highlighted, and new domestic forces are about to take the world by storm.
Currently, China's global smart wearable device supply chain is undergoing a transformation from cost dividends as the core to innovation-driven, making China an important force supporting the growth of the global smart wearable industry. Currently, the upstream sector is showing a development trend of accelerated localization of core components and continuous optimization of the software ecosystem. Midstream is an important hub in the industrial chain. It integrates the three major sectors of design and development, manufacturing, and brand operation, showing the development characteristics of specialized division of manufacturing, increased added value of products, and improved comprehensive brand operation capabilities. Relying on a stable and innovative supply chain, downstream Chinese smart wearable device manufacturers are speeding up overseas, and their international competitiveness is outstanding.
Trend 2
Dual generation resonance detonated the trillion-dollar blue ocean, and Gen Z and the Yinfa family jointly built a new growth pole for smart wearables.
The “Gen Z” group is the main force in digital consumption and is a key force driving the growth of the smart wearable device market. At the same time, the trend of aging in China and the high incidence of chronic diseases among the elderly will further spur demand for smart wearable devices for the elderly with core functions such as health monitoring, fall prevention and warning, accurate positioning, chronic disease management, and safety protection.
Trend 3
Data assets: From records to assets, health data has become a new hot topic in the digital economy era.
The number of smart wearable app users continues to rise, which not only reflects the public's rigid demand for health data services, but also accumulates massive amounts of health data for the industry. Smart wearable apps have reached 150 million monthly active users. Continuous health data is becoming a core asset for insurance pricing, clinical research, and personalized health services, spawning multiple value-added services such as “monitoring-feedback-reward”.
Trend 4
AI is reshaping the interactive logic of smart wearables, advancing from smart tools to digital partners.
Human-computer interaction methods continue to evolve, promoting the gradual formation of AI terminals in wearable devices. AI terminals for wearable devices have undergone qualitative changes in the four dimensions of interaction, service, application, and connectivity, showing the characteristics of cognitive collaboration in the interactive mode; services can predict and predict according to scenarios; application architectures are driven by intention; and seamless interconnection between devices is achieved.
Trend 5
Segmentation: Multiple factors drive the expansion of the AI glasses market, and ecological collaboration and integration have become a winning point for enterprises.
Supply and demand resonate with policy. The data shows that China's smart glasses market grew sharply from 450 million yuan in 2022 to 11.21 billion yuan in 2025, with a compound growth rate of close to 200.0%, or 192.1%. This scale will continue to grow. It is expected to exceed 100 billion yuan in 2029 to reach 119.11 billion yuan9.
Trend 6
Segmentation: The advantages of smart rings are highlighted, breaking through the smallest wearable health terminals.
A smart ring is a wearable smart terminal that integrates a miniature sensor, a low-power processor, and an artificial intelligence algorithm. It is a composite wearable device that mainly focuses on lightweight health monitoring and covers intelligent interaction and productivity applications. With a weight of only 2-4 grams, an ultra-thin design of about 2.5 mm, and IP68 waterproof capability, the smart ring can be worn for 24 hours without feeling sensitive. In particular, it solves the pain points of traditional watches being heavy to wear at night, easy to press on the wrist, and the screen light interferes with sleep.
Trend 7
Segmentation: The non-intrusive brain-computer technology industry chain has been improved, and the first year of “ideological interaction” on the consumer side has begun.
In 2026, “brain-computer interface” was first included in the government work report. It is one of the future industries that China will focus on cultivating during the “15th Five-Year Plan” period. Currently, the brain-computer interface (BCI) industry is mainly in the medical and health care field. Demand for applications such as motor function reconstruction, neurological rehabilitation, and adjuvant treatment of brain diseases continues to be released, driving rapid growth in the scale of the industry. In 2025, the market size of brain-computer interface-related products in China is about 5.1 billion yuan, of which the medical field is about 3.49 billion yuan. According to the technical path division, non-invasive BCI is widely used in fields such as medical diagnosis to consumer electronics because it does not require surgery and has outstanding safety and ease of use, with a market share of up to 78% 10.
Trend 8
Diversified scenarios: Health monitoring is being upgraded in specialization, shifting from a health toy to a wrist clinic.
China's wearable health monitoring devices are at the stage of leapfrogging from consumer electronics to professional medical aids, showing a continuous upgrade path of more accurate monitoring, non-sensitive form, and closed-loop functional intervention. Moving from a “health toy” to a “wrist clinic,” the triple dividends of aging and chronic disease management needs and policies drive growth, and medical-grade certification has become a core barrier.
Trend 9
Diversified scenarios: In the new era of sports and health, smart wear has advanced from optional accessories to the core fitness standard.
In 2025, the global sports and fitness wearable device market will reach 43.313 billion yuan11, of which the Chinese market is about 13.4 billion yuan12. With the increase in public health awareness, AI/multi-modal sensing upgrades, and the deepening of professional sports scenarios, the CAGR is expected to be around 14% over the next 7 years. The commercial value of accurate scenario-based monitoring continues to be highlighted as AI-driven devices move from data recording to actionable insights.
Trend 10
Diversification of scenarios: Smart wearable technology spillover, reconstructing military and industrial human-robot interaction models.
In 2024, the global military wearables market will reach US$4.17 billion. It is expected to reach $5.53 billion by 2032 13. In the process of industrial digitalization, informatization, and networking transformation and upgrading, industrial wearable devices are being promoted and applied more and more widely. In 2025, the Chinese market size will reach 27.436 billion yuan14. Smart wearables are expanding from consumer goods to specialized fields such as military situation awareness, industrial safety protection, and efficiency improvement.