
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Watsco (WSO) Undervalued On Its Granite Group Deal?
Granite Group deal puts Watsco’s plumbing push in focus
Watsco (WSO) has moved to acquire The Granite Group, a distributor with about $500 million in annual plumbing and HVAC sales across seven Northeast states, reinforcing its buy and build approach.
Watsco’s share price has been under pressure, with the stock down 21.26% over the past 90 days and 12.86% year to date. The 1 year total shareholder return has declined 20.82% even as management pursues acquisitions like Granite Group and prepares for investor visibility events such as the upcoming Morgan Stanley Laguna Conference.
Spot 34 high quality undervalued stocks that, like Watsco, are using acquisitions and scale plays to try to reset the market’s expectations.Bulls see Watsco using Granite Group scale to justify a richer multiple. Bears point to the share price slide and acquisition risk. With the numbers now on the table, which side does valuation lean toward?
Most Popular Narrative: 26% Undervalued
Compared with Watsco’s last close of $302.66, the most followed narrative anchors on a fair value of $410.60. This frames the recent share price slide as a valuation gap rather than a broken business model.
Watsco maintains a strong balance sheet with $430 million in cash, no debt, and over $3 billion in equity, allowing them to strategically respond to market conditions and invest in growth opportunities, which could lead to enhanced long-term revenue and earnings.
See why 10 investors see Watsco as 26% undervalued.
Result: Fair Value of $410.60 (UNDERVALUED)
Still, tariff uncertainty and the A2L product transition could put pressure on Watsco’s pricing power and profitability if costs rise faster than end demand.
Find out about the key risks to this Watsco narrative.
Another View: What Watsco’s P/E Is Telling Investors
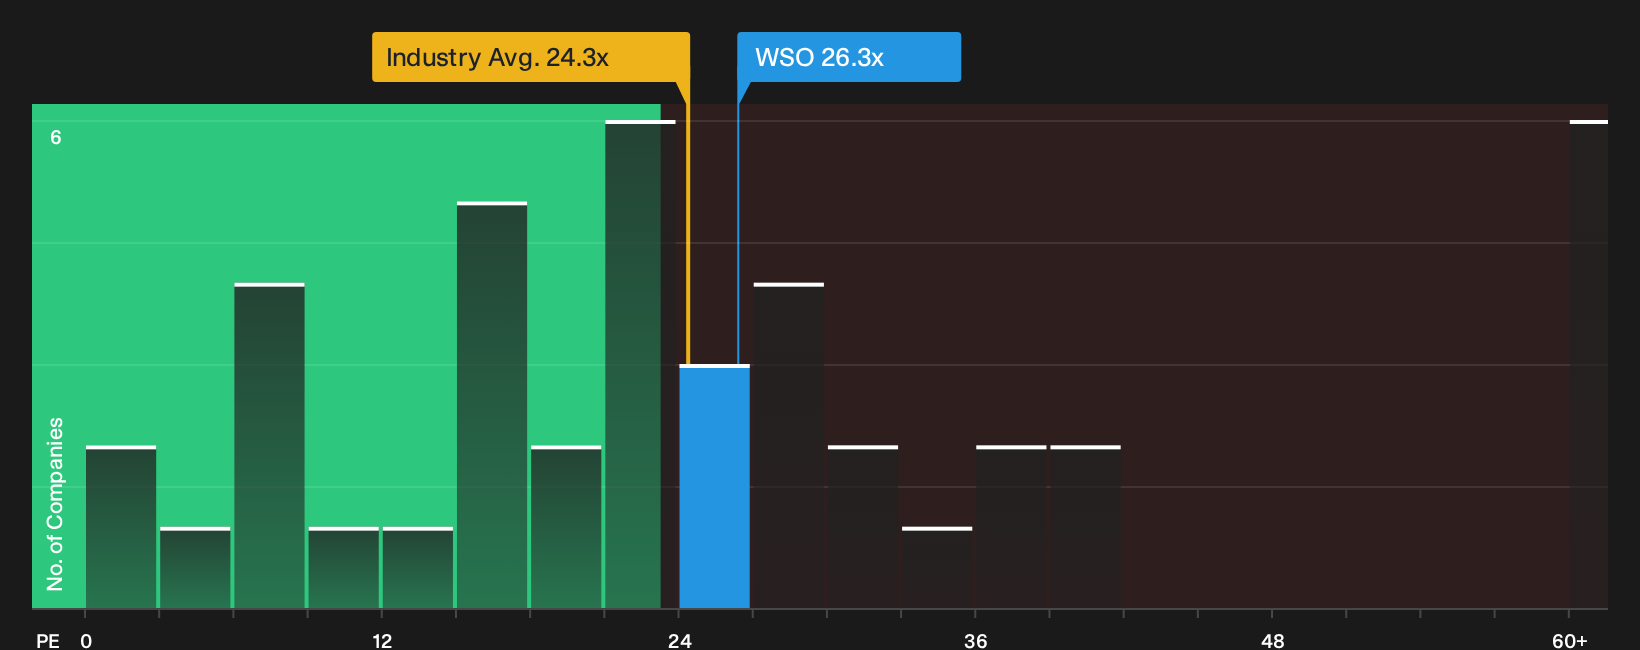
While the SWS DCF model points to Watsco as deeply undervalued, the simple earnings multiple tells a cooler story. Watsco trades on a P/E of 26.3x, above peers at 24x and above its own fair ratio of 25.7x. That premium suggests less margin for error if the bullish narrative softens.
Investors who want to see how this earnings based view compares with the full valuation picture can review the detailed numbers in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Investor sentiment on Watsco appears mixed after these developments. Act quickly, review the underlying metrics, and compare the 3 key rewards and 1 important warning sign with your own expectations for the business.
Looking for more investment ideas beyond Watsco?
If Watsco has you thinking harder about valuation, do not stop here. Put that curiosity to work and line up a few fresh candidates worth investigating.
- Target turnaround potential by scanning 2 elite penny stocks with strong financials that already pair tiny share prices with stronger balance sheets and cleaner financials than many expect.
- Prioritize value first and hunt for 34 high quality undervalued stocks where solid cash generation and healthy fundamentals line up with prices that still look out of sync with the underlying business.
- Lean into resilience by reviewing the 11 resilient stocks with low risk scores that combine sturdier financial profiles with lower risk scores, so you are not scrambling after the next sell off.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com