
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Insmed (INSM) Fully Priced After Its 296% Revenue Surge?
Insmed has seen its stock reshape over the past few years, and the question now is whether the current price is supported by what the business is generating in sales. With the share price moving against a backdrop of shifting returns and fresh product news, investors are increasingly asking how much revenue power they are really paying for.
- Over the past three years, Insmed has delivered a share price gain of roughly 3.5x. This puts a lot of weight on whether its current sales base and future revenue potential can carry that move.
- Recent updates around BRINSUPRI and the broader respiratory portfolio point to management leaning hard into revenue growth from new treatments. This can reshape how investors think about the right sales multiple to apply to this stock.
- Your read on Insmed is one view; the desks covering it have another. See what analysts think Insmed's shares could be worth.
The issue now is whether Insmed's current market value is justified by the sales the company is producing and the revenue investors expect it to deliver over time.
If you want to pressure test this same sales based valuation question beyond Insmed, it helps to compare with companies in 34 high quality undervalued stocks.
Does Insmed Look Pricey on Sales?
P/S fits Insmed because the business is still loss making and investors are mainly paying for revenue traction and pipeline expectations rather than current profits.
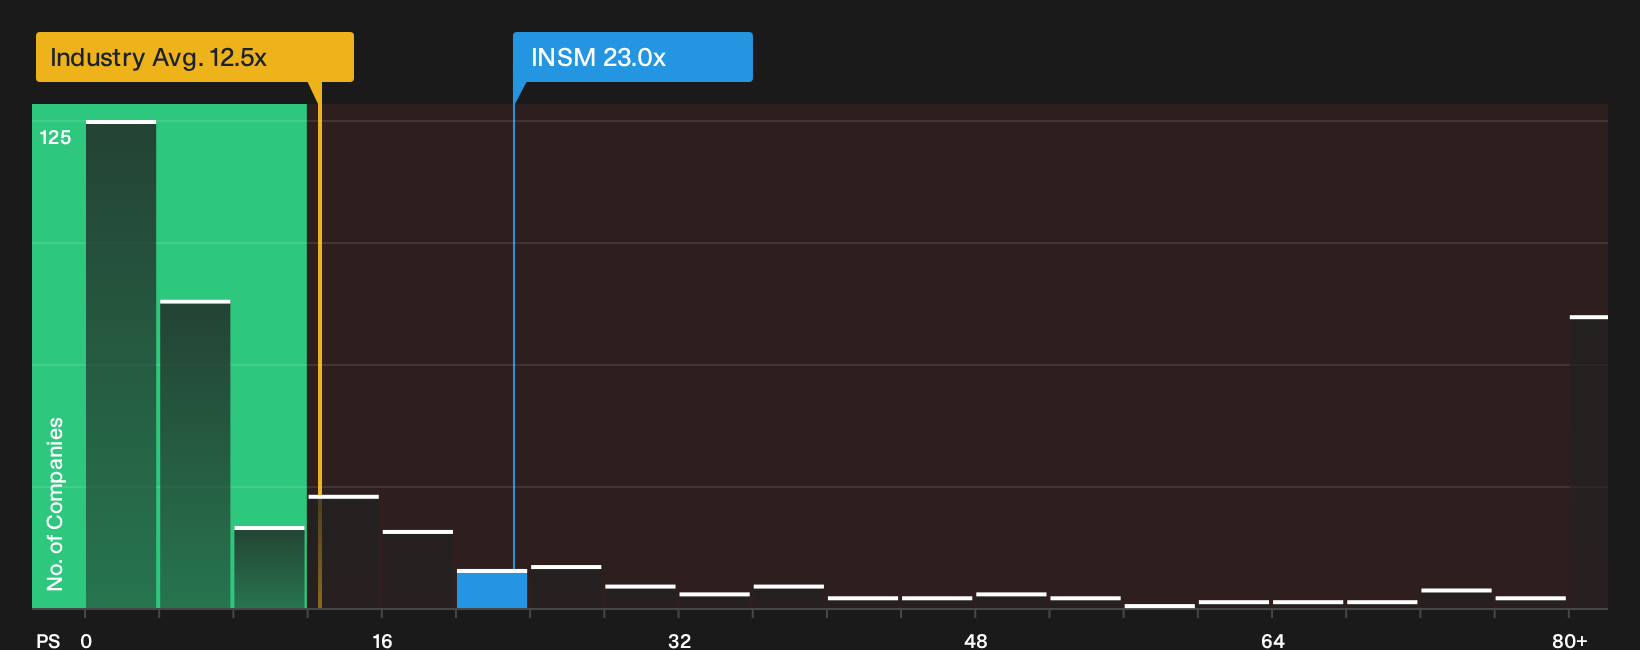
On this metric, Insmed trades on a P/S of about 23.0x, which is well above the biotech industry average of roughly 12.5x and also higher than the peer group on roughly 11.2x. The valuation model suggests a tailored P/S level that reflects Insmed's specific growth profile, margins, size and risk, and the current 23.0x sits above that reference point, so the stock screens as overvalued on this framework. Because the recent BRINSUPRI driven revenue surge and higher 2026 sales guidance are already public, this gap implies that a lot of that good news is already reflected in the share price. Explore the numbers behind Insmed's P/S valuation.
The Insmed Narrative: What Would Justify Today's Price?
Narratives pick up where Insmed's valuation puzzle leaves off and spell out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully more expensive or cheaper than today, based on scenarios shared on Simply Wall St's Community page. Instead of a single ratio or model output, they describe the future that number relies on so you can observe over time whether reality aligns with those built-in assumptions.
One of the top community narratives on Insmed: 39% undervalued
"The anticipated U.S. launch of brensocatib in bronchiectasis in the third quarter of 2025 is a major catalyst, expected to significantly increase revenue…"
Discover why this Narrative puts Insmed at 39% undervalued.
For Insmed, the price tag is only one piece of the investment story
Before you decide how Insmed fits in your portfolio, it helps to ask who is actually steering the business, how their pay is structured and whether those incentives line up with your outcome as a shareholder. See who runs Insmed and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com