
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Ambarella (AMBA) Undervalued On Its Expanded Edge AI Developer Zone Push?
Ambarella (AMBA) has just widened its bet on edge AI, expanding its Developer Zone into a cloud-hosted environment that ties together Google Cloud, ZEDEDA, Ultralytics and new enterprise-focused distribution and services partners.
Ambarella’s latest product push lands in a tricky tape, with the share price down 21.59% over the past 30 days and 14.41% year to date, while the 1 year total shareholder return has declined 18.71%. However, the 3 year total shareholder return remains positive at 13.96%, suggesting near term momentum has faded even as longer term holders have still come out ahead overall.
Spot emerging edge AI opportunities around Ambarella by scanning our curated 59 AI infrastructure stocks that are building the chips, systems and platforms behind next-generation physical AI.For Ambarella, the sharp pullback sits awkwardly next to expanding partnerships, a growing Developer Zone and improving loss figures. Is this repricing mostly about sentiment, or does it better reflect where the valuation now sits?
Most Popular Narrative: 28% Undervalued
Ambarella's most followed narrative pegs fair value at $89.36 versus the last close of $64.33, implying a sizable gap that rests on edge AI demand, long dated auto programs and margin expansion playing out as modeled.
Sharply increasing demand for AI-powered edge devices, including portable video, robotics (notably aerial drones), and edge infrastructure, has led to a rapid expansion of Ambarella's addressable markets, as evidenced by record edge AI revenue and multiple recent, diversified design wins. This is catalyzing strong, sustained revenue growth and positions Ambarella to benefit further as additional vertical applications for edge AI proliferate.
See why 37 investors see Ambarella as 28% undervalued.
Result: Fair Value of $89.36 (UNDERVALUED)
Still, the narrative around Ambarella can weaken if heavy IoT exposure and customer concentration reduce demand, or if rising R&D spending squeezes margins for a longer period than expected.
Find out about the key risks to this Ambarella narrative.
Another View On Ambarella’s Valuation
While the narrative and analyst target put Ambarella at a fair value of $89.36, the current P/S ratio of 6.8x sends a different signal. That multiple sits above both peers at 4.2x and a fair ratio of 5.4x, which points to valuation risk if sentiment weakens further.
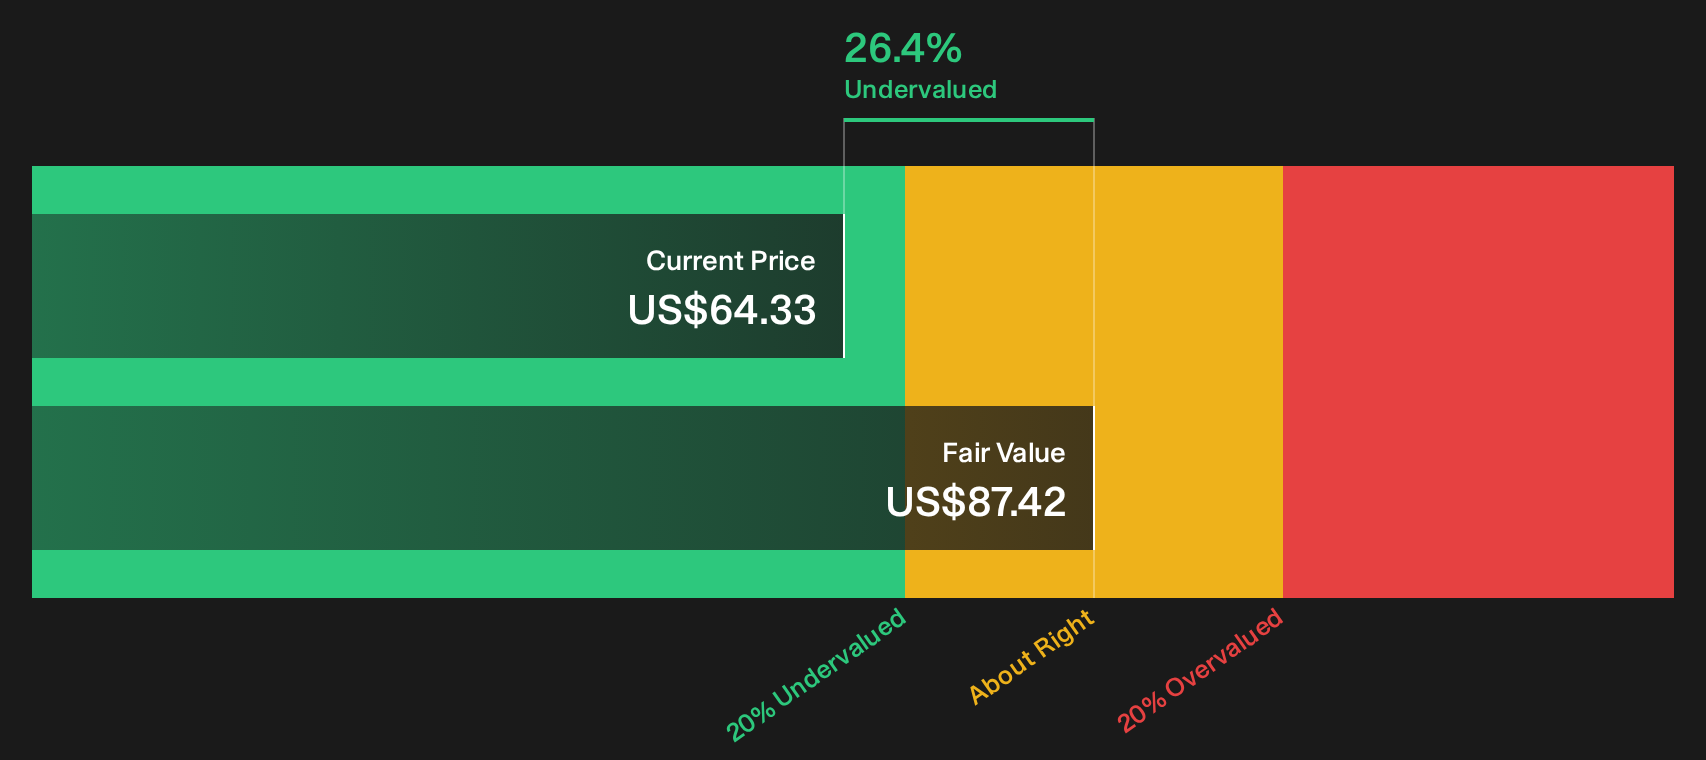
Our DCF model reaches a higher figure than the market price, with future cash flows pointing to $87.42 per share, so the SWS DCF model currently frames Ambarella as undervalued. The question is which signal you trust more when growth is still on paper rather than in the income statement.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views on Ambarella so far. If you want to move quickly and weigh the trade-off between concern and optimism for yourself, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Ambarella?
If Ambarella has your attention but you want a wider watchlist, use the Simply Wall St Screener to surface fresh opportunities before they move without you.
- Target potential mispricing by scanning a curated set of 34 high quality undervalued stocks that combine quality fundamentals with discounted valuations.
- Prioritise resilience by reviewing a 11 resilient stocks with low risk scores that screens for businesses with sturdier earnings profiles and lower risk scores.
- Hunt for future leaders by checking a 16 high quality undiscovered gems where strong balance sheets and solid cash flows have not yet attracted broad attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com