
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Defensive Dividend Stocks Investors May Revisit If The Fed Stays Higher For Longer
Rate hike odds near 92% and inflation stuck at 3.4% put the Federal Reserve back in the driver’s seat, and that can reshape which dividend stocks feel safe and which feel exposed. Investors who wait for the dust to settle often miss the quieter shifts that really matter. This article walks through three US large-cap defensive dividend stocks closely tied to this Fed story and explains how each could respond if borrowing costs rise again.
The stocks covered below are just a starter pack, and the full screen surfaced 13 more large-cap defensive dividend companies with equally compelling narratives that are not unpacked in this article. To identify, compare, and analyze the highest-conviction ideas that fit this Fed-sensitive dividend theme, head straight to the US Large-Cap Defensive Dividend Stocks screener.
PepsiCo (PEP)
Overview: PepsiCo is a global consumer staples business that sells branded snacks and beverages through supermarkets, convenience stores, foodservice channels, and e-commerce.
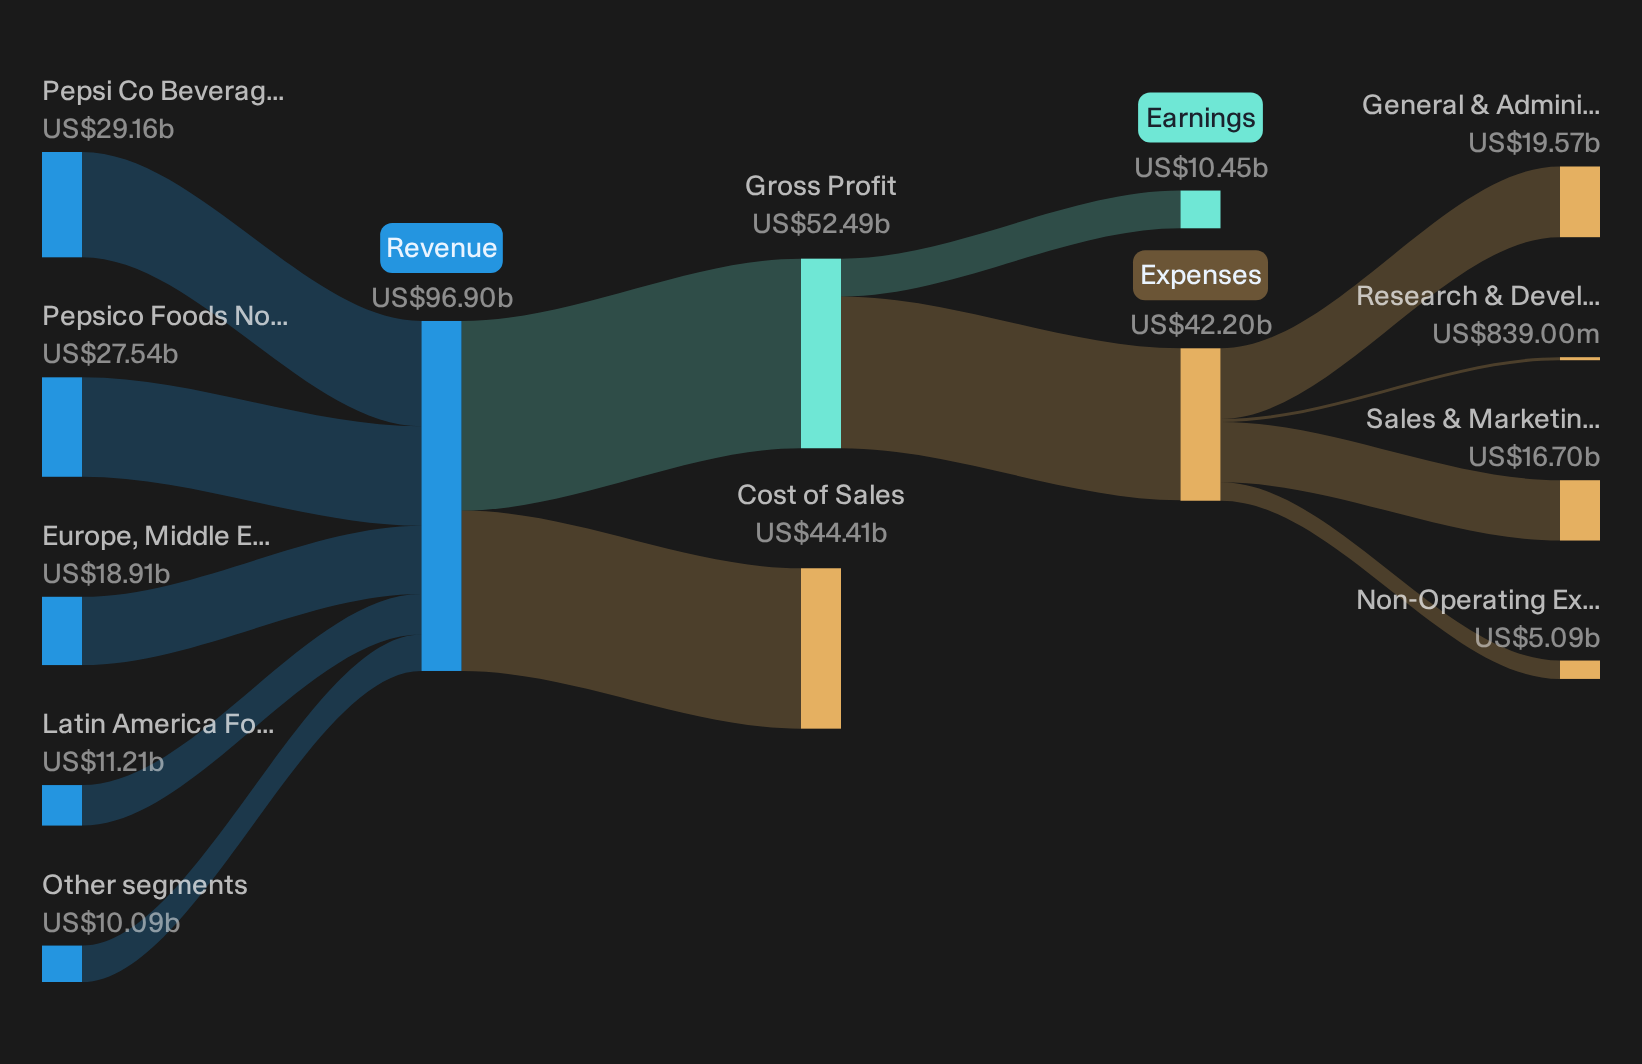
Operations: PepsiCo generates about US$27.5b from PepsiCo Foods North America, US$29.2b from PepsiCo Beverages North America, and over US$41b from international segments.
Market Cap: US$186.1b
PepsiCo fits the defensive dividend theme because households keep buying its snacks and drinks through economic cycles, which helps support steady income for shareholders even when rate expectations shift.
"The company is pushing into functional and health-focused drinks with the acquisition of Poppi (prebiotic soda), ownership of Bubly (sparkling water), and a partnership with Celsius (including Rockstar energy drinks)."
What really matters next for PepsiCo is how one quiet cost and efficiency pressure plays out against that evolving product mix.
That quiet pressure is exactly what could reshape how PepsiCo’s mix, margins, and dividend feel if the Fed tightens again, so read the full narrative for PepsiCo to see how those forces are already accelerating beneath the surface.
Coca-Cola FEMSA. de (KOF)
Overview: Coca-Cola FEMSA is a major Latin American Coca-Cola bottler that produces and distributes branded soft drinks, water, and other beverages across retail and foodservice channels, giving the defensive dividend screen exposure to everyday consumer spending in emerging markets.
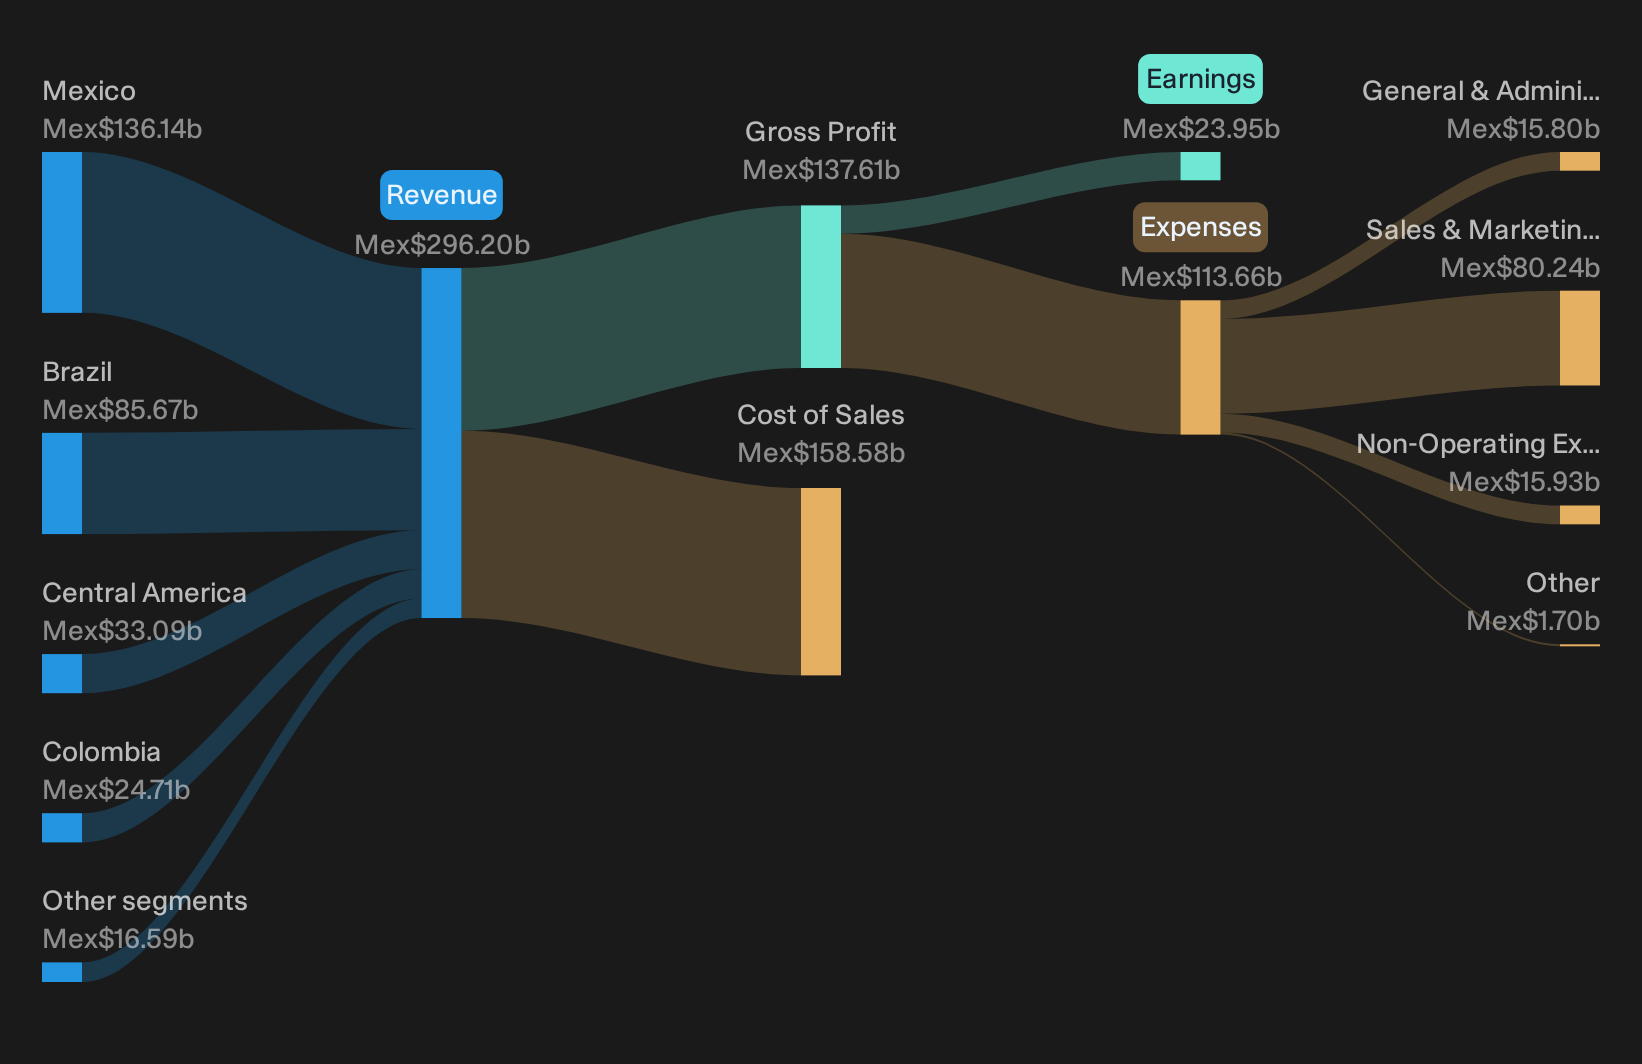
Operations: Coca-Cola FEMSA generates about MX$296.2b from non alcoholic beverages, mainly across Mexico (MX$136.1b) and Brazil (MX$85.7b), with additional sales across Central and South America.
Market Cap: US$23.5b
Coca-Cola FEMSA fits the large cap defensive dividend theme as a consumer staples stock whose earnings and payouts are tied to repeat beverage purchases rather than rate sensitive borrowing. This can help anchor income when markets focus on the Federal Reserve and tightening financial conditions.
"Expansion into health-focused and premium beverages, combined with strong capital discipline, positions the company for margin expansion and higher returns to shareholders."
The real swing factor is how one less visible shift in its route to market model changes the balance between pricing power and volume resilience.
That hidden shift is exactly where the Coca-Cola FEMSA story gets interesting, so read the full narrative for Coca-Cola FEMSA. de to see how its pricing power and volumes could be quietly decoupling.
Stryker (SYK)
Overview: Stryker is a large medical technology company that supplies surgical equipment, orthopedic implants, and stroke and trauma devices to hospitals worldwide.
Operations: Stryker generates about US$9.7b from Orthopaedics and US$16.1b from MedSurg and Neurotechnology, primarily serving United States healthcare customers.
Market Cap: US$108.1b
Stryker fits the US Large Cap Defensive Dividend Stocks theme because procedure driven healthcare demand and recurring device usage give its dividend a more resilient backdrop when higher rates pressure cyclical sectors.
"The ongoing industry shift to outpatient and minimally invasive procedures, where Stryker is a leading supplier of ASC infrastructure and advanced surgical solutions, positions the company to benefit from increased procedure volumes and deeper customer penetration, bolstering both revenue and operating leverage."
What really moves the needle from here is how one unresolved operational constraint affects the balance between that resilient demand and future margins.
This operational constraint is central to what happens next, so read the full narrative for Stryker to see whether it is quietly capping or accelerating Stryker’s upside.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, new momentum, and stocks still flying under the radar for now can get caught fast once the crowd piles in, act now.
- Target resilient cash generators with robust payouts by scanning a curated pool of income ideas through the 6 dividend fortresses.
- Explore the build out of next generation computing by filtering a focused universe of enablers using the 59 AI infrastructure stocks.
- Review opportunities related to electrification by zeroing in on miners and producers via the 29 top copper producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com