
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Axcelis Technologies (ACLS) Undervalued Following Its Korea Manufacturing Expansion?
Axcelis Technologies expands manufacturing footprint in Korea
Axcelis Technologies (ACLS) has announced a US$35 million investment in a new ion implantation equipment manufacturing facility in Pyeongtaek, Korea, a move that puts fresh attention on the stock.
Despite Axcelis Technologies committing fresh capital to its manufacturing base and raising its profile at industry events such as IIT 2026, the share price has fallen 25.1% over the past month and 40.1% over the past quarter. Even so, the year-to-date share price return is 22.0% and the 5-year total shareholder return sits at 119.5%. This points to long-term holders still being well ahead, despite fading recent momentum as the market reassesses both growth prospects and risk around future demand for its tools.
Spot opportunities emerging around Axcelis Technologies by scanning a curated set of 59 AI infrastructure stocks that are tied to the same long-term demand for chip manufacturing capacity.Axcelis Technologies has a stock that has fallen hard while analyst and intrinsic value estimates point much higher. Where does fair value really sit in that gap, and what do the recent moves imply?
Most Popular Narrative: 35% Undervalued
Axcelis Technologies last closed at $105.04, while the most followed narrative anchors fair value at $161.00. The debate now hinges on whether the underlying growth and margin story can live up to that gap.
Adoption of silicon carbide (SiC) power devices in electric vehicles and industrial applications remains early stage, with penetration rates and SiC content per vehicle expected to rise globally and across hybrids; Axcelis's leadership in high-energy ion implantation positions it to benefit from this ramp, supporting future revenue and gross margin expansion as SiC demand multiplies.
See why 76 investors see Axcelis Technologies as 35% undervalued.
Result: Fair Value of $161 (UNDERVALUED)
Still, Axcelis Technologies carries real swing factors, including heavy China exposure and the risk that slower silicon carbide adoption could limit demand for its highest value tools.
Find out about the key risks to this Axcelis Technologies narrative.
Another View on Axcelis Technologies’ valuation
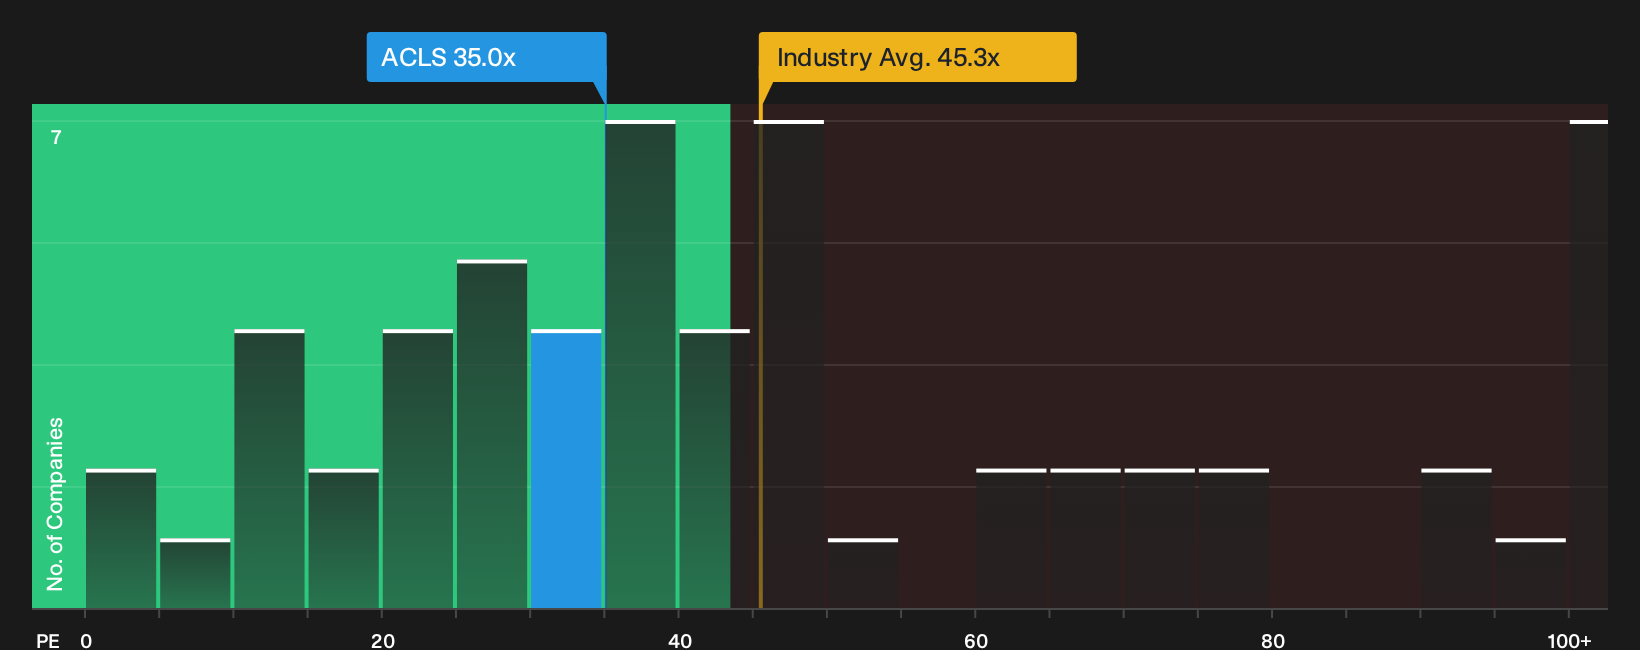
On simple P/E math, Axcelis Technologies trades around 35x earnings, while the fair ratio estimate sits closer to 32.2x. The broader US Semiconductor group averages about 44.5x, and peers sit near 47.3x, so the stock screens cheaper than the sector but a touch rich versus that fair ratio. Is the market paying up for quality or just stretching the rubber band?
See what the numbers say about this price and find out in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Axcelis Technologies is split, with some investors focused on the upside and others wary of the downside, so move quickly and test the data yourself against your own expectations. For a balanced view on both sides of the argument, start with the 2 key rewards and 2 important warning signs.
Looking for more Axcelis Technologies sized ideas?
Do not stop with Axcelis Technologies. Use this moment to widen your opportunity set and pressure test your thesis against other high potential stocks on your radar.
- Target fresh upside potential by scanning a curated set of 16 high quality undiscovered gems that may not yet be crowded with institutional money.
- Protect your downside first and build a shortlist from 11 resilient stocks with low risk scores that focus on resilience when conditions turn against you.
- Anchor your watchlist in financial strength by filtering through the list of solid balance sheet and fundamentals (22 results) so you are not caught off guard by hidden leverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com