
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kirby (KEX) Heads To Laguna Conference, Is The Stock Fully Priced?
Conference appearance puts Kirby in focus
Kirby (KEX) heads into Morgan Stanley's 14th Annual Laguna Conference on 15 September 2026, with investors watching how management frames its marine transportation and services operations at this high profile industry gathering.
Recent share price moves have been steady rather than dramatic, with the stock almost flat over the past quarter while still logging a share price return of 24.18% year to date and a 1 year total shareholder return of 64.29%, which indicates strong underlying momentum.
Compare Kirby's momentum with other transport and infrastructure plays by scanning our hand picked 38 power grid technology and infrastructure stocks that may also be catching investor attention around conference season.
Kirby trades near recent highs while still carrying a sizeable gap to both analyst targets and intrinsic estimates. The next step is to determine where fair value arguably sits within that range.
Most Popular Narrative: 16.5% Undervalued
Kirby closed at $138.96, while the most followed valuation storyline pegs fair value at about $166.33, leaving a sizeable gap that hinges on how durable its marine and services earnings power proves to be.
Supply constraints and industry-wide aging of the barge fleet are restraining new capacity growth. This is positioning Kirby to benefit from limited vessel availability, capacity consolidation, and rising charter rates over time, which should support steady revenue growth and expanding net margins.
See why 13 investors see Kirby as 16% undervalued.
Result: Fair Value of $166.33 (UNDERVALUED)
Still, Kirby's heavy reliance on the US petrochemical market, along with ongoing labor and maintenance cost pressures, could quickly challenge that undervaluation story if conditions worsen.
Find out about the key risks to this Kirby narrative.
Another View On Kirby's Valuation
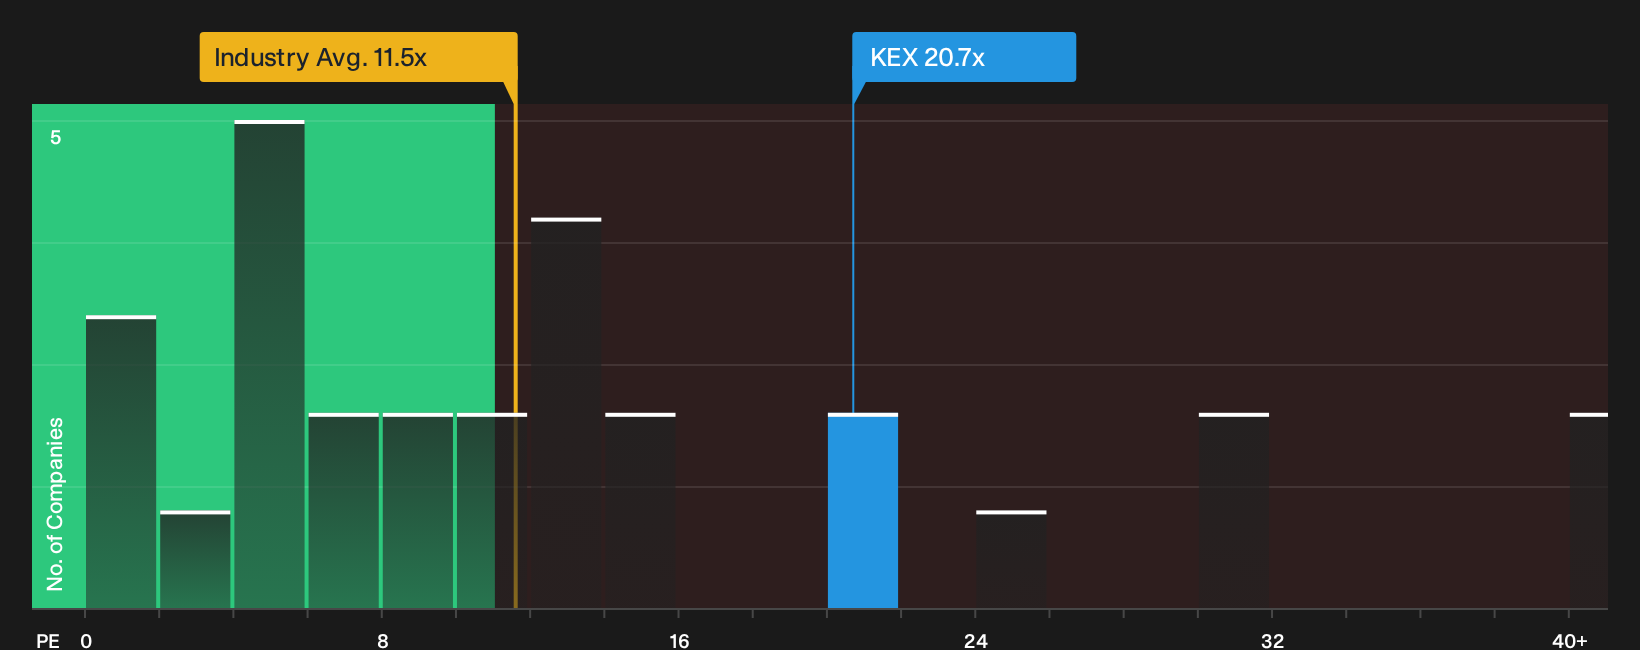
Those fair value figures look generous, yet Kirby's current P/E of 20.7x is higher than both the US Shipping industry at 10.8x and its peer group at 14.7x. It also sits above an estimated fair ratio of 18.4x, which points to less margin for error if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
All this debate around Kirby's value only matters if you test the numbers yourself and decide where you stand. Move quickly to review the potential upside and understand the 3 key rewards.
Looking for more investment ideas beyond Kirby?
If Kirby's story has you thinking more broadly, do not stop here. Use the screener to surface fresh opportunities before they move out of reach.
- Target resilient businesses with healthier balance sheets by scanning the list of solid balance sheet and fundamentals (22 results) that can handle tougher conditions without forcing rushed decisions.
- Zero in on potential mispricings by reviewing the 34 high quality undervalued stocks that combine quality fundamentals with prices that still look restrained.
- Strengthen your income stream by assessing the 6 dividend fortresses that focus on higher yields backed by more robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com