
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
WA (TSE:7683) Stock Faces Margin Crunch As Earnings Power Fades
The market has treated WA like a pure growth story, yet the latest half year showed how fragile that story looks when profit tightens. The stock closed at ¥1,414 today after a modestly positive run in recent weeks. However, the new H1 2027 report put the spotlight squarely on earnings power. Net income excluding extra items came in at ¥43.11 million and basic EPS was ¥2.26, numbers that sit uncomfortably beside a trailing P/E of 109.2x. For a specialty retailer priced this richly, margin pressure is not a side issue; it is the headline.
Is WA a rare case where a premium P/E near 109x still stacks up, or is the ¥1,414 share price simply too far ahead of earnings reality? Compare the current market optimism against the detailed cash flow and multiples work in the valuation analysis for WA
H1 2027 Earnings Summary
- Revenue (H1 2027 vs. H1 2026): ¥11,080.49 million vs. ¥11,747 million (down 5.7%)
- Net Income Excl. Extra Items (H1 2027 vs. H1 2026): ¥43.11 million vs. ¥484 million (down 91.1%)
- Basic EPS (H1 2027 vs. H1 2026): ¥2.26 vs. ¥25.37 (down 91.1%)
- Trailing Net Profit Margin (Last 12 Months vs. Prior Year): 1.1% vs. 4.4% (compression of 3.3 percentage points)
Prefer clean charts instead of another wall of WA earnings tables and ratios. See the full visual picture of WA’s valuation in the company report for WA.
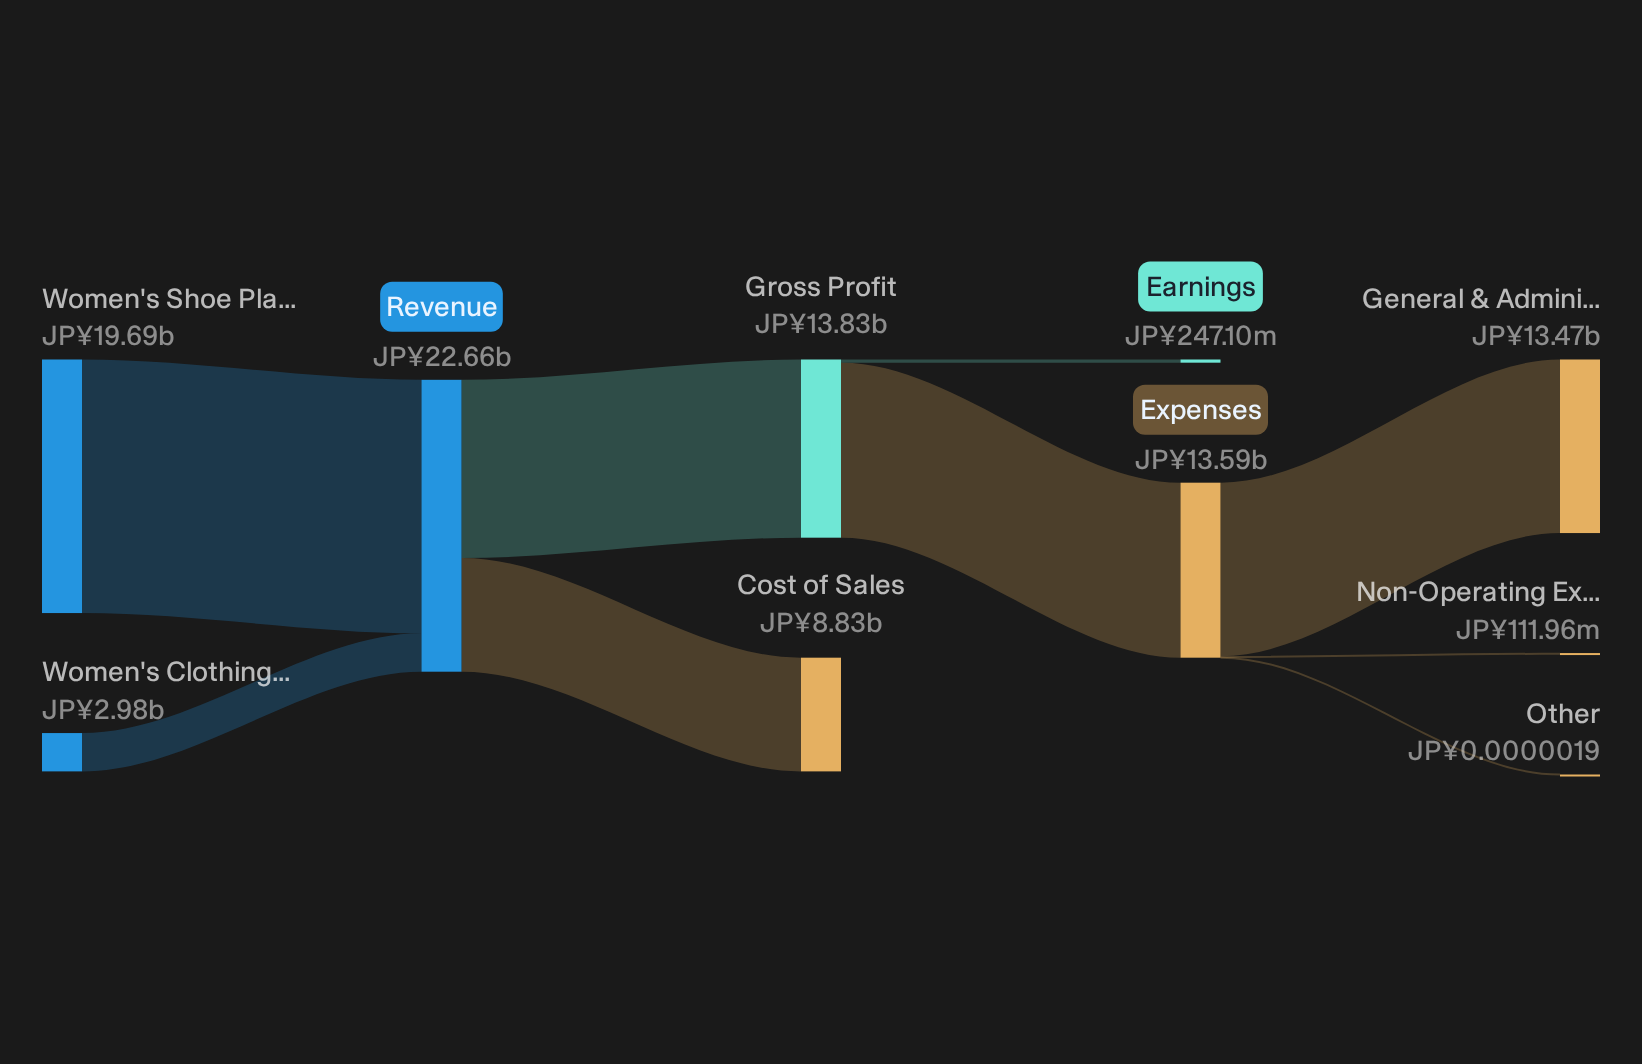
WA bull story meets earnings reality
Any bullish angle on WA has to work hard against these figures. Revenue moved from ¥11,747 million to ¥11,080.49 million, so the top line is not racing ahead to support profits. Net income excluding extra items dropped from ¥484 million to ¥43.11 million and basic EPS went from ¥25.37 to ¥2.26. Short term share returns are slightly positive, yet the latest half shows a retailer that is not currently translating brand strength into earnings momentum.
Bearish risks sharpen around profit compression
The bear case around fashion retail pressure finds support in WA’s profit squeeze. Net income excluding extra items fell 91.1% year on year and basic EPS moved in the same direction. Trailing net profit margin narrowed from 4.4% to 1.1%, which is thin cushioning for a discretionary retailer facing competition and fashion risk. Revenue softness alongside weaker profitability indicates that the immediate risks are concentrated on the earnings side, rather than the balance sheet or sentiment, within this H1 2027 period.
Review WA’s margin slump in context, and scan our full risk analysis for WA which shows 1 important warning sign to see whether this compression signals deeper structural vulnerabilities.Stay Ahead Of Your Next Move
WA’s rich P/E and sharp margin squeeze make timing and entry price key, so register for free with Simply Wall St and add it to your Watchlist to track share moves against fair value before you commit fresh capital. After you own it, keep control of the bigger picture with the Portfolio Command Center that mutes the noise and highlights only the updates that matter for your holdings. For longer term investors, the Community helps you tap into other viewpoints so you can pressure test your own thesis. Spot emerging catalysts and potential risks early, stay prepared, and give yourself a better chance of reacting before the wider market does.
Seeking Alternatives Beyond WA Right Now
Market attention moves fast, and fresh ideas can gain breakout momentum before most investors notice. Scan these curated stock sets while the edge is under the radar for now.
- Identify income-focused companies with established cash flows and yield characteristics by reviewing our carefully filtered 16 dividend fortresses.
- Track infrastructure themes that are positioned to participate in AI-related demand and capital spending using the focused 60 AI infrastructure stocks.
- Look for companies with sturdier balance sheets that may be better positioned if sentiment changes by working through the curated list of solid balance sheet and fundamentals stocks (20 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com