
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
B2Gold (TSX:BTO) Stock May Be Cheap Despite Fekola And Goose Progress
B2Gold has delivered a powerful multi year run for shareholders, which naturally raises a basic question for anyone looking at the ticker today. Is the current share price still grounded in what the business is earning, or has sentiment moved ahead of the underlying profits?
- Over the past 5 years, B2Gold has returned 91.6%, putting more weight on whether the current valuation can be explained by its earnings profile.
- Recent progress across key gold projects and solid revenue from production can shape expectations for future profit levels and the timing of cash flows that feed into any earnings based valuation.
- There is a second opinion on B2Gold worth weighing. See what analysts think B2Gold's shares could be worth.
The issue now is whether B2Gold's present share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings based question you are asking of B2Gold across a broader set of gold producers, take a look at the 35 elite gold producer stocks.
Is B2Gold Still Cheap on Earnings?
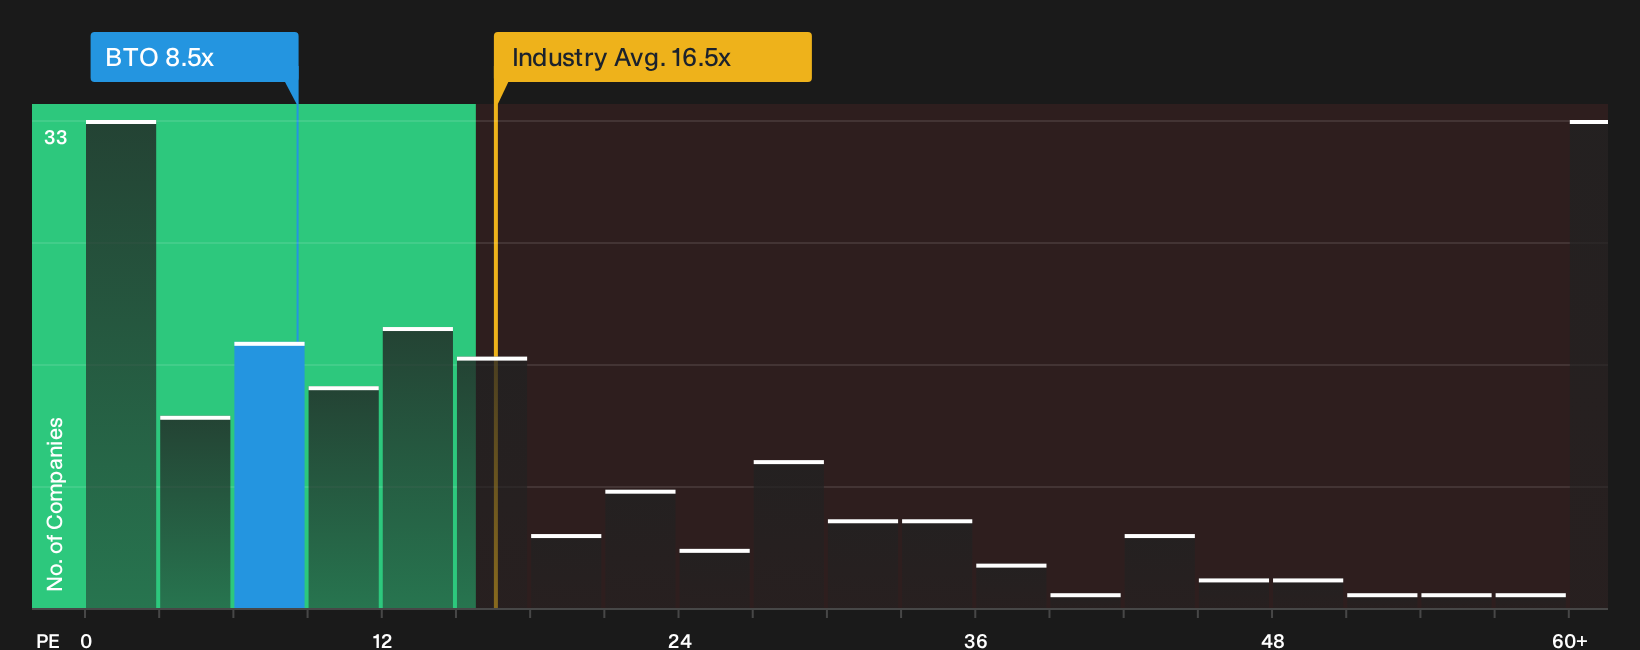
The P/E ratio is a useful metric for B2Gold because earnings are a key anchor for a mature gold producer that already has producing assets and defined projects. On this basis, the stock trades at about 8.5x earnings, which is well below the Metals and Mining industry average of roughly 16.5x and also below the peer group on about 14.9x.
Because the P/E that investors might expect for B2Gold, given its economics and risk profile, sits higher than the current multiple, the shares appear undervalued on this framework. Recent progress at the Fekola Complex and the Goose Project has lifted sentiment, yet the P/E still prices B2Gold at a discount to both the sector and close competitors. This suggests the market is embedding a more cautious outlook than those benchmarks indicate. Explore the numbers behind B2Gold's P/E valuation.
The B2Gold Narrative: What Would Justify Today's Price?
Narratives on B2Gold pick up where the P/E puzzle leaves off, explaining which paths for future growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than it is today. Each scenario links a fair value estimate to a specific mix of potential catalysts and risks around B2Gold's projects and operations, so you can track over time which version of events is actually unfolding on Simply Wall St's Community page.
Community views on B2Gold split between those who see underappreciated project upside and those who focus on structural risks and a tighter future.
Bull case: 35% undervalued
"B2Gold's disciplined capital allocation, evidenced by the accelerated completion of major growth CapEx and a strong net cash position, provides optionality for opportunistic acquisitions or rapid deployment of capital into new high-return projects..."
Discover why this Narrative puts B2Gold at 35% undervalued.
Bear case: 12% overvalued
"B2Gold's heavy reliance on operations in geopolitically complex jurisdictions, especially in West Africa, exposes the company to chronic risks of regulatory disruption, resource nationalism, and resource-based taxation..."
Explore why this Narrative puts B2Gold at 12% overvalued.
B2Gold’s valuation still leaves one crucial piece of the puzzle unresolved
The figures around B2Gold only tell part of the story, because the people setting priorities and how they are rewarded can tilt long term outcomes in very different directions. See who runs B2Gold and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com