
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Merck (MRK) Expands Keytruda Trial Reach, Is 4% Undervalued Enough?
Merck (MRK) just expanded its oncology footprint by agreeing to supply Keytruda for Perspective Therapeutics’ trial that combines targeted alpha therapy [212Pb]PSV359 with immunotherapy in certain lung and colorectal cancers.
Merck’s latest oncology tie-up comes after a string of presentations at major healthcare conferences and a recent dividend announcement. The shares now trade at US$143.79 with a 30-day share price return of 5.85% and a 90-day share price return of 24.56%.
Scan beyond Merck and see how other oncology focused businesses with potential breakout momentum line up in our curated 34 high quality undervalued stocks.
Merck’s strong recent run could reflect growing conviction in its oncology and pipeline story, or simply a hotter mood around big pharma. It is time to see which story the current valuation actually tells.
Most Popular Narrative: 4% Undervalued
Merck’s most followed narrative pegs fair value at $150.42, just above the recent $143.79 close. This frames the current oncology excitement through a cash flow and discount rate lens rather than just headlines.
With its acquisition and licensing strategy, Merck has nearly tripled its late-phase pipeline since 2021, which is expected to have a potential commercial opportunity of over $50 billion by the mid-2030s, driving earnings growth. The ongoing strong launches of key new products, such as WINREVAIR and CAPVAXIVE, are positively impacting revenues and are expected to support further growth in the coming years.
See why 407 investors see Merck as 4% undervalued.
Result: Fair Value of $150.42 (UNDERVALUED)
Still, the Merck story can change quickly if Keytruda’s loss of exclusivity hits harder than expected or if pricing and tariff pressures squeeze profitability.
Find out about the key risks to this Merck narrative.
Another View: Merck’s Valuation Looks Rich On P/E
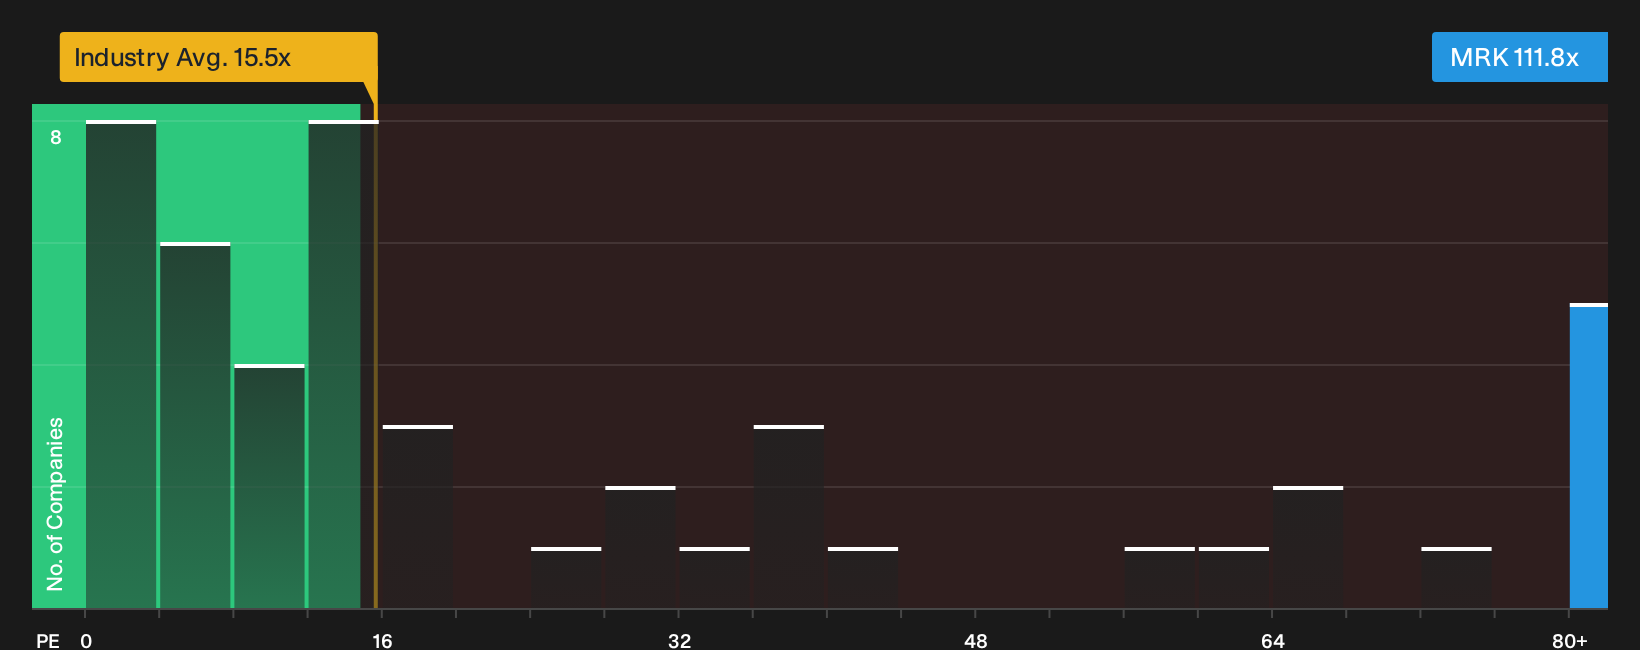
The earlier story paints Merck as 4% undervalued using cash flow forecasts. A simple P/E cross-check tells a very different story. The shares trade at around 111.8x earnings, compared with 15.5x for the US pharmaceuticals industry, 29.7x for peers, and a fair ratio estimate of 48.5x. That gap points to real valuation risk if sentiment cools.
See what the numbers say about this price in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Merck’s price and prospects are exactly why you should look at the full picture yourself, then decide where you land using our breakdown of 2 key rewards and 5 important warning signs.
Looking for more Merck investment ideas?
If you want fresh opportunities beyond Merck, use the Simply Wall St Screener to quickly surface ideas that match how you like to invest.
- Target fresh potential by scanning a 16 high quality undiscovered gems that couples strong fundamentals with relatively low market attention.
- Prioritise resilience with a list of solid balance sheet and fundamentals (22 results) so you can focus on businesses that pair financial strength with dependable fundamentals.
- Dial down risk by filtering a 11 resilient stocks with low risk scores that highlights companies with more measured volatility and sturdier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com