
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Global Insider Buying Highlights 3 Undervalued Small Caps
As global markets face heightened volatility due to geopolitical tensions and rising oil prices, small-cap stocks have experienced notable pressure, with indices like the Russell 2000 seeing significant declines. In this challenging environment, identifying undervalued opportunities becomes crucial for investors seeking potential growth; insider buying can serve as a valuable indicator of confidence in a company's future prospects.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 5.0x | 2.2x | 33.90% | ★★★★★★ |
| China Aircraft Leasing Group Holdings | 7.3x | 1.0x | 36.16% | ★★★★★☆ |
| Saniona | 7.8x | 3.4x | 27.41% | ★★★★☆☆ |
| Linc | 12.6x | 13.1x | 31.78% | ★★★★☆☆ |
| Sagicor Financial | 7.0x | 0.5x | -80.46% | ★★★★☆☆ |
| Yellow Pages | 8.2x | 0.8x | 29.49% | ★★★☆☆☆ |
| Diversified Royalty | 25.6x | 10.2x | 45.34% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 22.57% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -211.78% | ★★★☆☆☆ |
| Hong Fok | 23.4x | 6.8x | 30.61% | ★★★☆☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
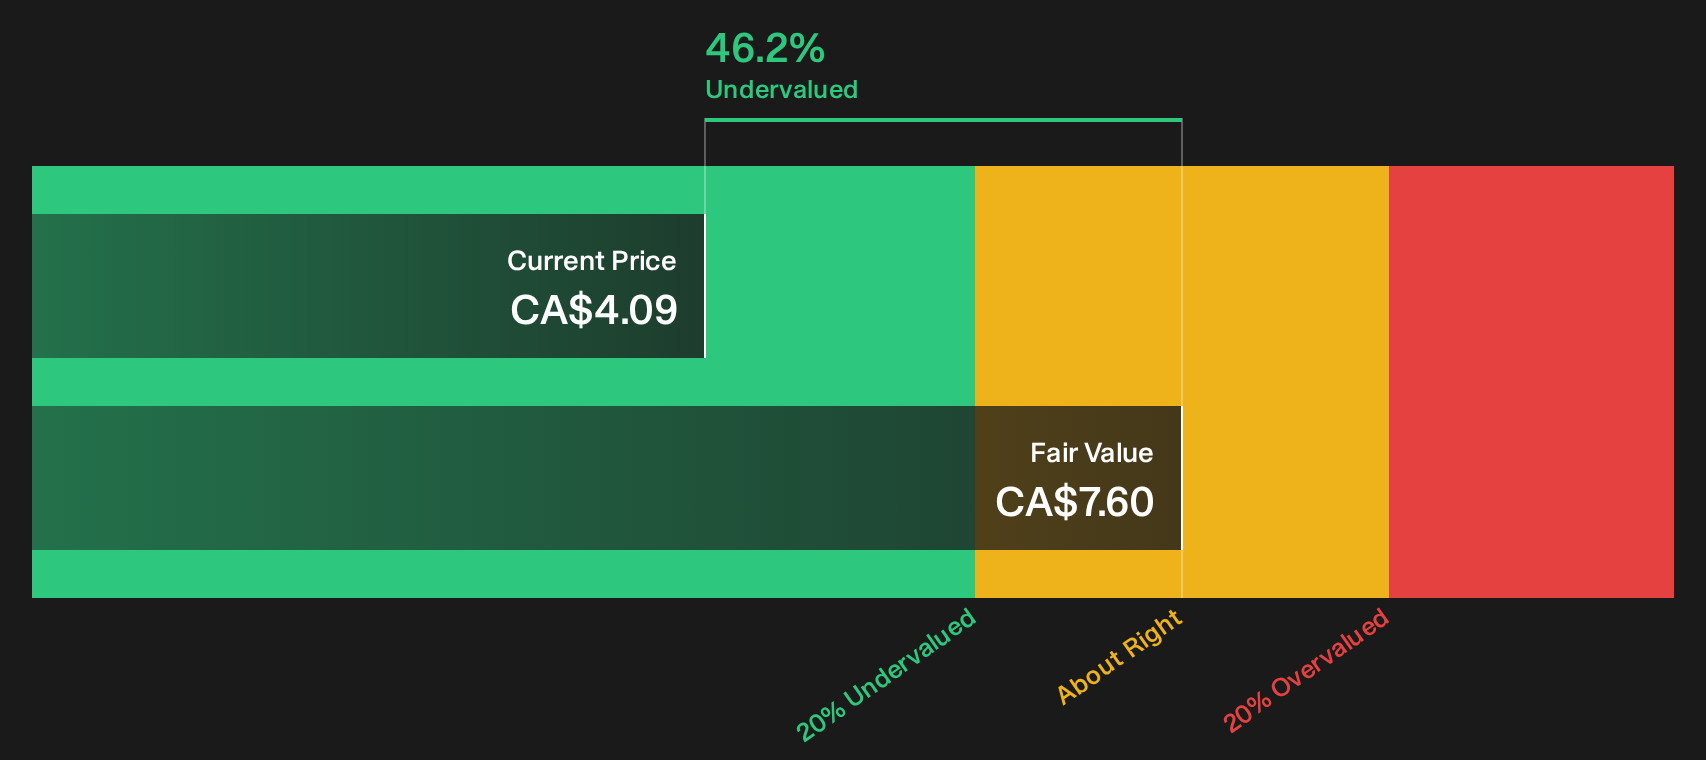
Diversified Royalty (TSX:DIV)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Diversified Royalty is a multi-royalty corporation that acquires top-line royalties from well-managed businesses and has a market cap of approximately CA$0.43 billion.
Operations: The company's revenue model shows a consistent increase in revenue over the periods, reaching CA$76.47 million by June 30, 2026. The gross profit margin reached 100% in several recent periods, indicating no cost of goods sold reported. Operating expenses have varied but were recorded at CA$11.09 million as of June 30, 2026. Net income margin showed fluctuations with a notable value of approximately 39.71% during the same period.
PE: 25.6x
Diversified Royalty, a company with a focus on royalty streams, recently reported Q2 2026 revenue of C$21.68 million, an increase from last year but with net income dropping to C$3.14 million. Despite this dip in earnings, insider confidence is evident as Johnny Ciampi purchased 100,000 shares for nearly C$399,000 between July and September 2026. The firm continues to pay consistent dividends of C$0.02375 per share monthly while managing higher-risk external funding sources without customer deposits.
Journey Energy (TSX:JOY)
Simply Wall St Value Rating: ★★★☆☆☆
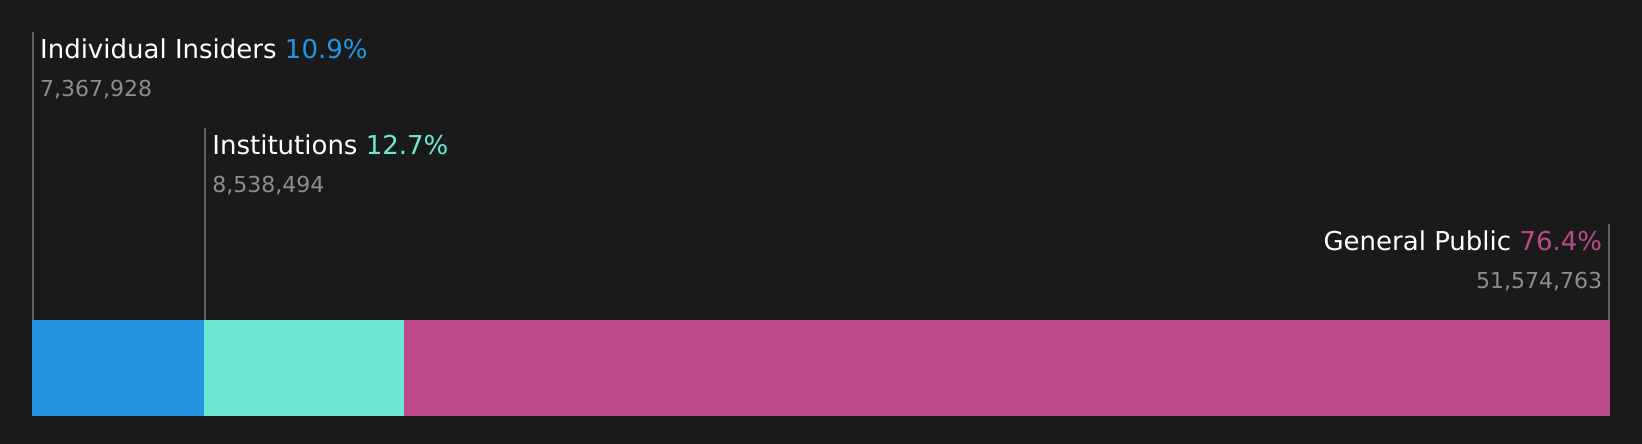
Overview: Journey Energy is a Canadian oil and gas exploration and production company with a market cap of approximately CA$0.47 billion, focusing on the development and acquisition of oil-weighted properties in Western Canada.
Operations: Journey Energy's revenue primarily comes from its operations, with cost of goods sold (COGS) being a significant expense. Over recent periods, the company has experienced fluctuations in its gross profit margin, reaching as high as 61.50% and as low as 33.04%. Notable operating expenses include general and administrative costs which have varied between CA$3.74 million to CA$14.68 million over the observed periods. The net income margin has also shown variability, indicating shifts in profitability across different quarters.
PE: 15.1x
Journey Energy, a small player in the energy sector, demonstrates potential as an undervalued investment. Recent earnings show significant growth with Q2 revenue hitting C$55.38 million, up from C$42.63 million last year, and net income reaching C$18.51 million compared to C$4.07 million previously. Despite no share repurchases recently, insider confidence is evident through consistent stock purchases over the past months. With earnings forecasted to grow nearly 29% annually, Journey's future appears promising amidst its industry challenges.
- Click to explore a detailed breakdown of our findings in Journey Energy's valuation report.
Assess Journey Energy's past performance with our detailed historical performance reports.
Vital Infrastructure Property Trust (TSX:VITL.UN)
Simply Wall St Value Rating: ★★★★★☆
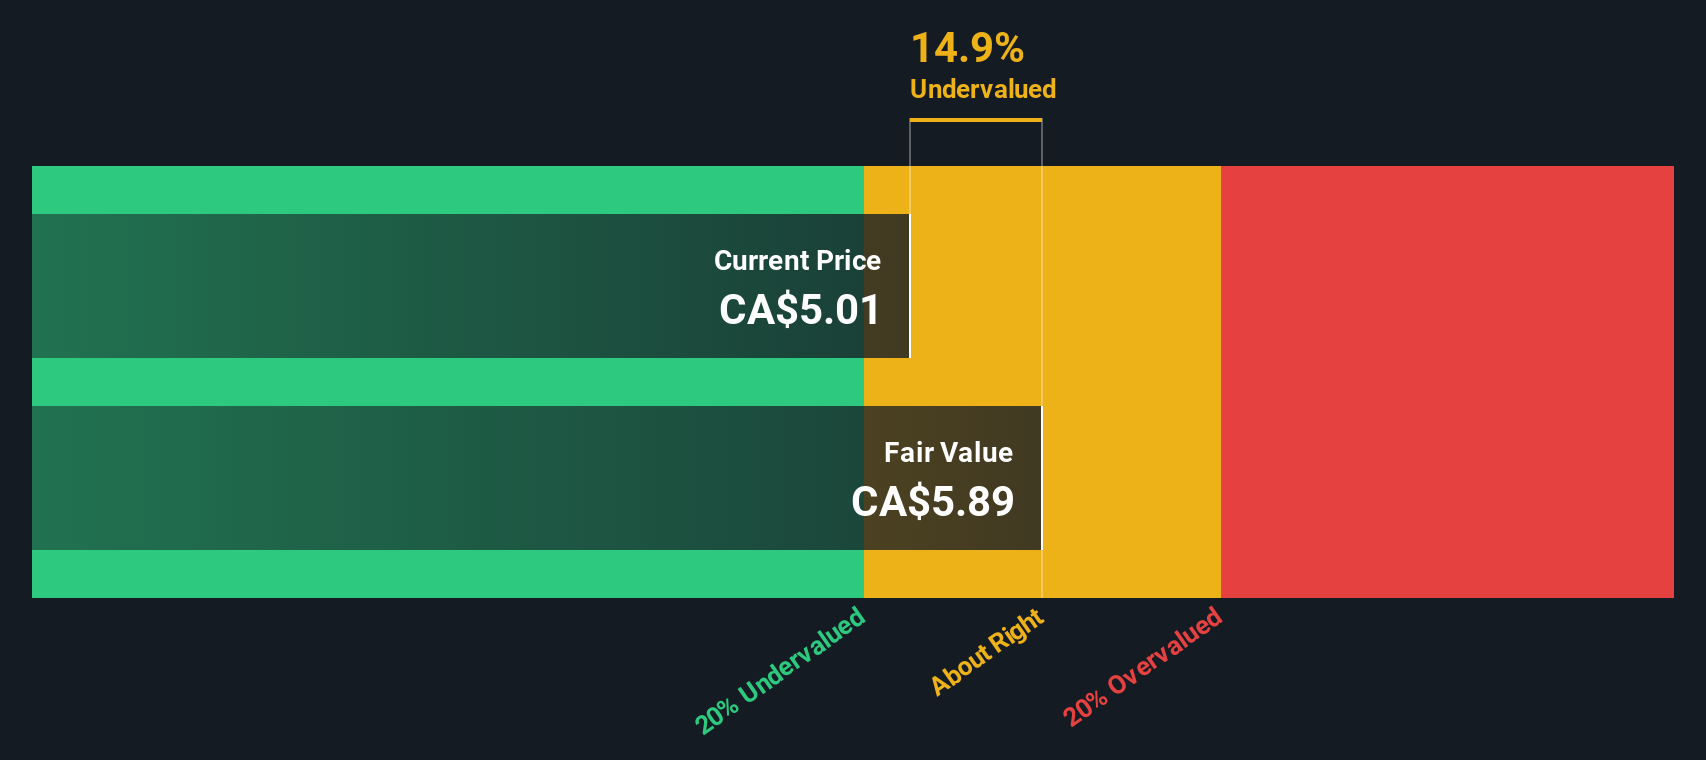
Overview: Vital Infrastructure Property Trust focuses on healthcare real estate, with operations centered around managing and investing in properties within this sector, and it has a market cap of CA$1.24 billion.
Operations: The primary revenue stream is derived from the Healthcare Real Estate Sector, with a recent revenue figure of CA$391.14 million. The gross profit margin has shown variability, with a recent value of 75.19%. Operating expenses and non-operating expenses have significantly impacted net income, resulting in a net loss in the most recent period.
PE: -16.0x
Vital Infrastructure Property Trust recently secured a $500 million unsecured credit facility, enhancing its financial flexibility and liquidity. This move aligns with their strategic focus on acquisitions, like the East New York Health Hub for US$89.9 million, which is expected to boost Funds From Operations per unit. Despite a drop in Q2 sales to CAD 66.09 million from CAD 99 million last year and net income falling significantly, insider confidence remains evident with ongoing dividend affirmations of CAD 0.03 per share monthly through September 2026.
Where To Now?
- Click through to start exploring the rest of the 112 Undervalued Global Small Caps With Insider Buying now.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com