
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Undiscovered Gems In Global Markets September 2026
As global markets navigate a turbulent landscape characterized by rising oil prices and inflation concerns, small-cap stocks have faced notable challenges, with indices like the Russell 2000 experiencing significant declines. Despite these headwinds, the search for undiscovered gems remains compelling; investors often seek companies that demonstrate resilience and potential for growth even amid broader market volatility.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| GROUPE SFPI | 18.02% | 4.25% | -29.76% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
ITAB Group (OM:ITAB)
Simply Wall St Value Rating: ★★★★☆☆
Overview: ITAB Group AB (publ) specializes in developing, manufacturing, selling, and installing store concepts for retail chain stores with a market capitalization of approximately SEK4.42 billion.
Operations: The company generates revenue primarily from its Furniture & Fixtures segment, amounting to SEK12.84 billion.
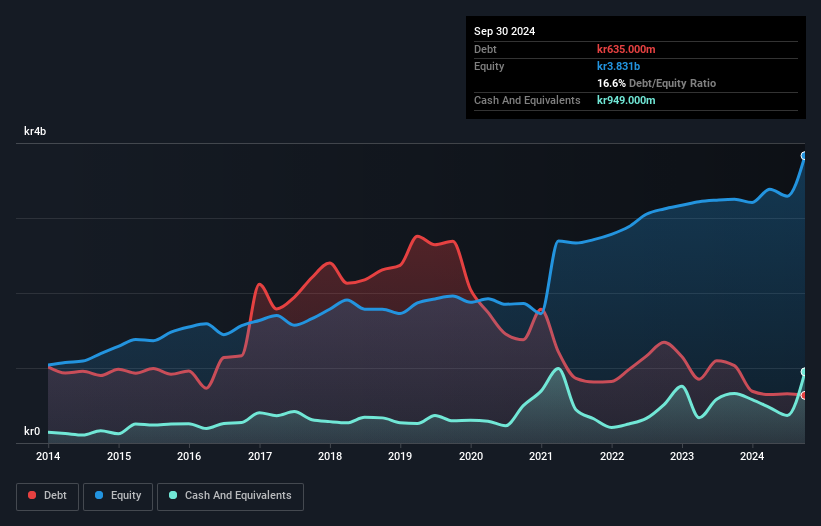
ITAB Group, a small cap player in the commercial services sector, has been making waves with strategic moves like acquiring HMY to broaden its retail solutions. Despite its net debt to equity ratio of 53.2% being high, ITAB's interest payments are comfortably covered by EBIT at 4.9x. The company's earnings have grown 17.1% annually over five years and are projected to grow by 42.88% per year moving forward, though recent earnings growth of 18.1% lagged behind industry peers at 22%. Trading significantly below fair value estimates suggests potential upside for investors considering ITAB's evolving business model and market expansion efforts.
Delijia Transmission Technology (Jiangsu)Ltd (SHSE:603092)
Simply Wall St Value Rating: ★★★★★☆
Overview: Delijia Transmission Technology (Jiangsu) Ltd operates in the transmission technology sector and has a market capitalization of CN¥17.75 billion.
Operations: Delijia Transmission Technology (Jiangsu) Ltd generates revenue primarily from its transmission technology products. The company's financial performance is highlighted by a net profit margin of 12.5%, indicating efficient cost management relative to its revenue streams.
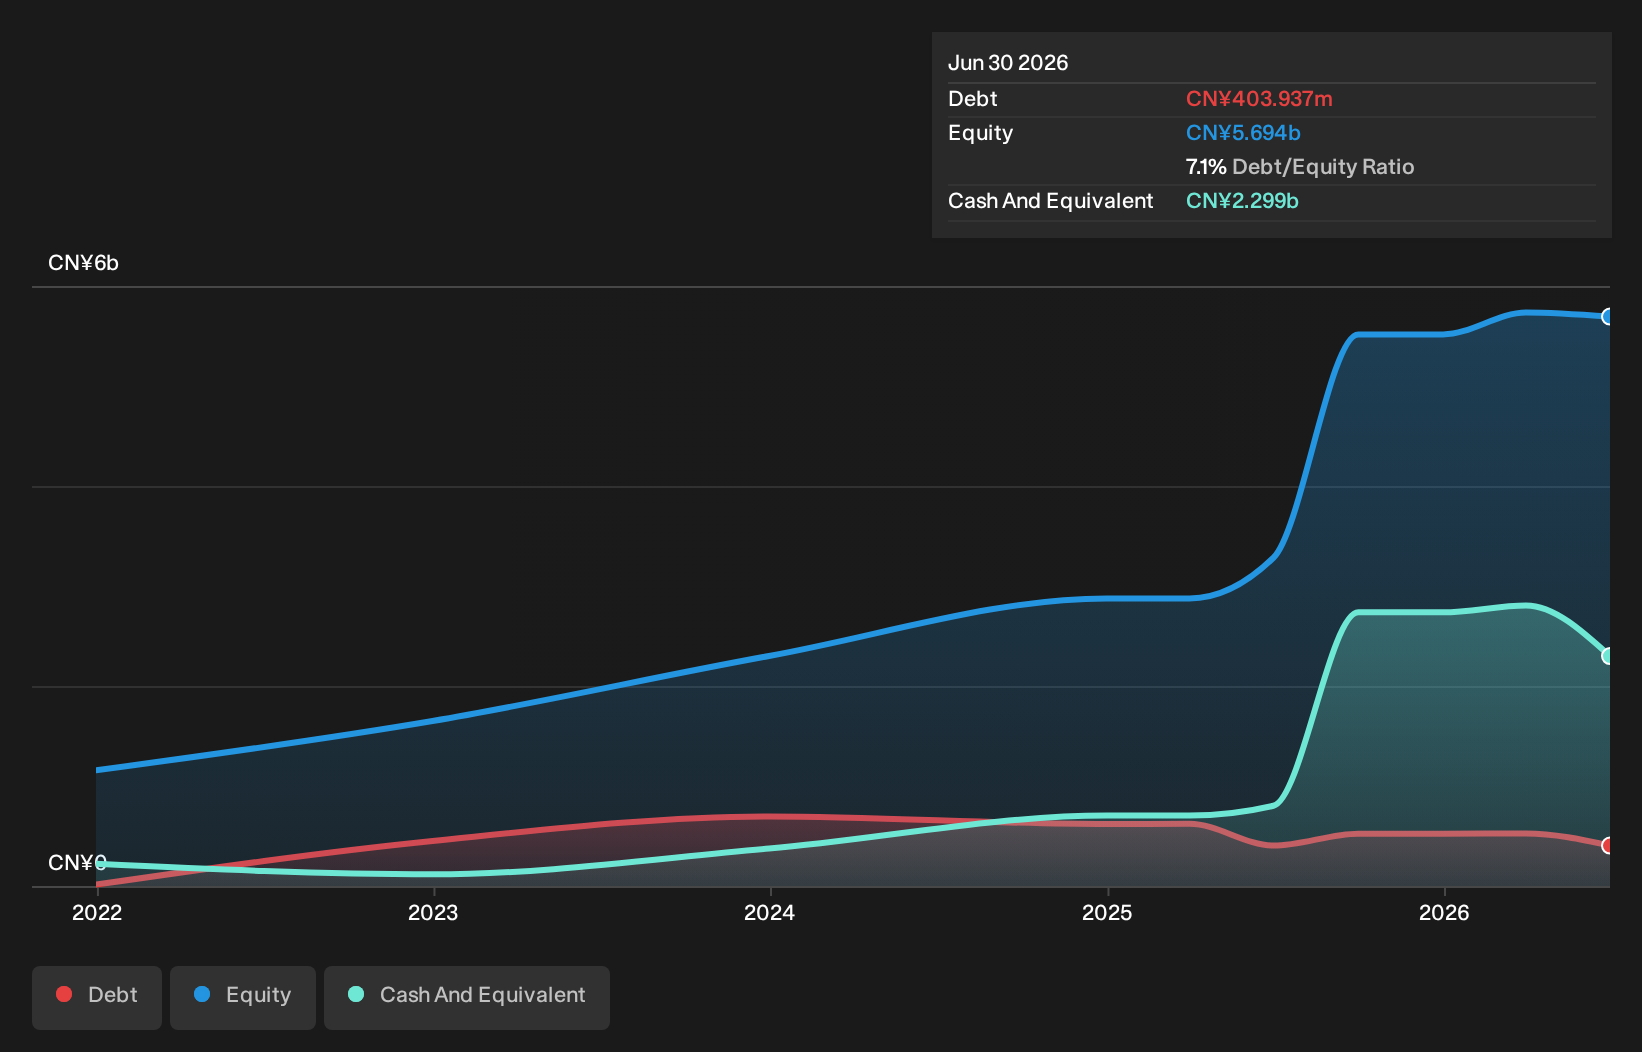
Delijia Transmission Technology, a nimble player in the transmission tech sector, has shown commendable performance with its recent half-year sales reaching CNY 2.56 billion, up from CNY 2.47 billion last year. Revenue climbed to CNY 2.60 billion compared to the prior year's CNY 2.48 billion, while net income saw an uptick to CNY 411.75 million from CNY 393.72 million previously reported. Despite a slight dip in basic earnings per share from continuing operations at CNY 1.03 compared to last year's figure of CNY 1.09, Delijia's growth trajectory remains promising within its industry context.
- Dive into the specifics of Delijia Transmission Technology (Jiangsu)Ltd here with our thorough health report.
Understand Delijia Transmission Technology (Jiangsu)Ltd's track record by examining our Past report.
Cybozu (TSE:4776)
Simply Wall St Value Rating: ★★★★★★
Overview: Cybozu, Inc. focuses on developing, selling, and operating groupware in Japan with a market capitalization of ¥139.27 billion.
Operations: Revenue from software development and sales amounts to ¥40.31 billion.
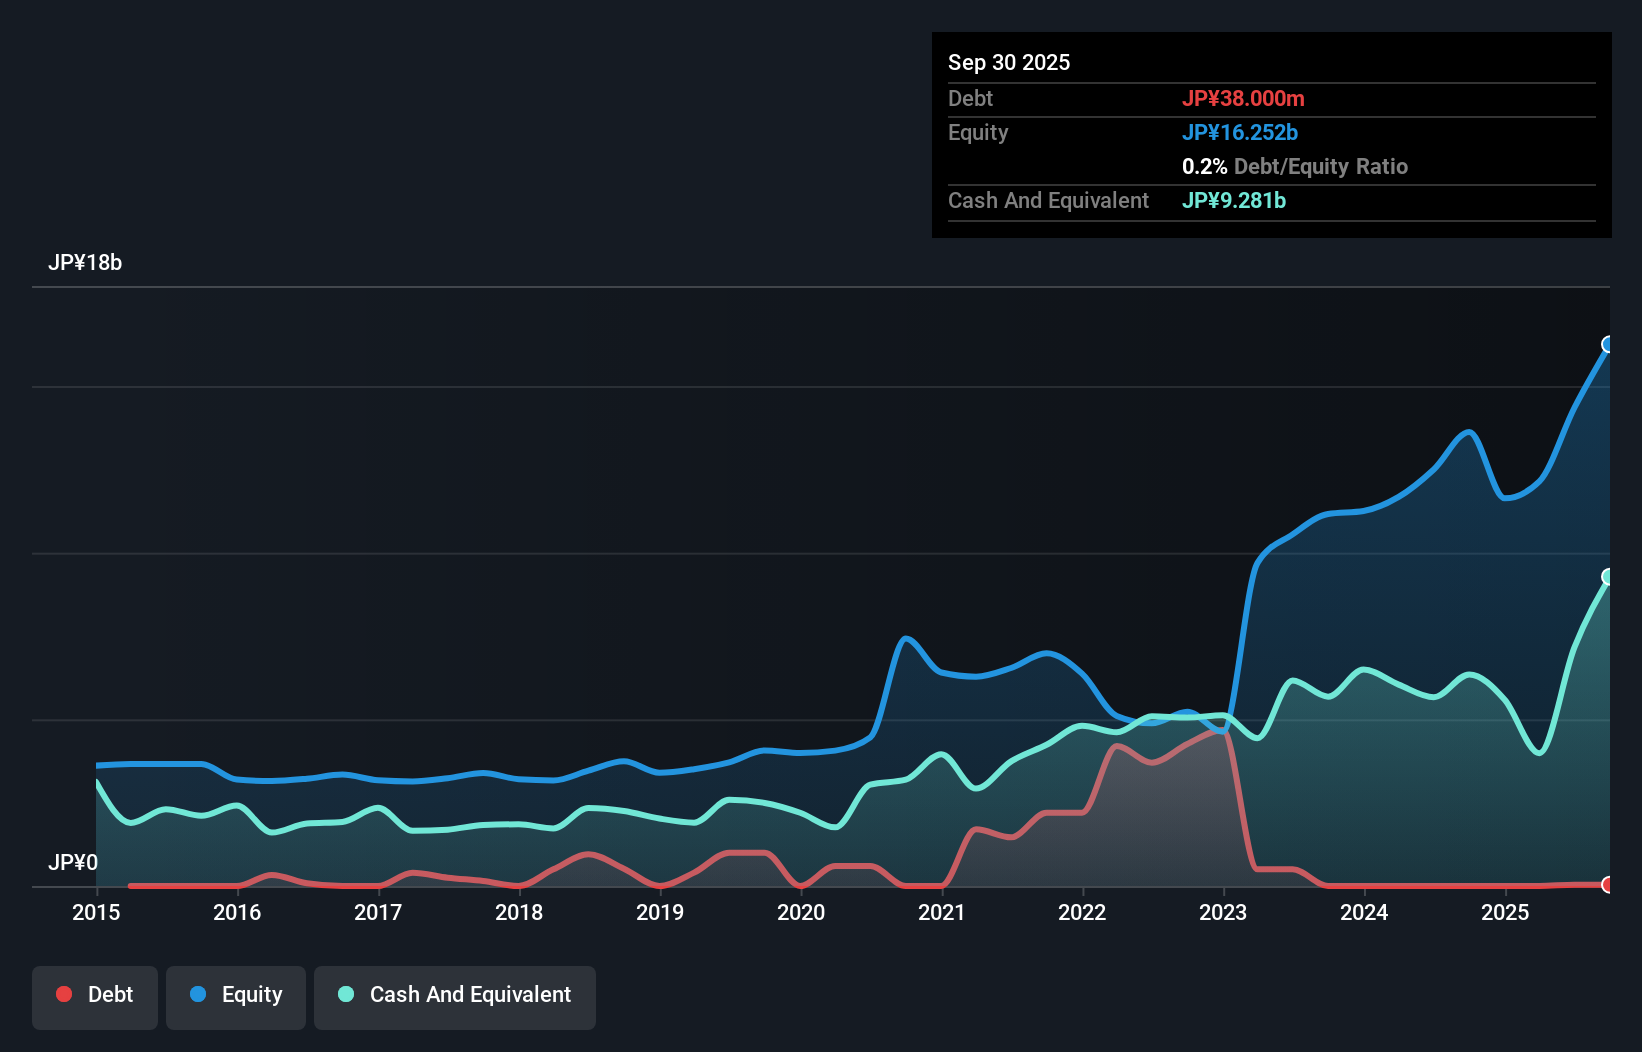
Cybozu, a notable player in the software industry, has demonstrated robust performance with earnings growing 44.1% over the past year, surpassing the industry average of 12.7%. The company is trading at an attractive value, estimated to be 38.7% below its fair value. Recent sales figures show promising growth; for July 2026 alone, sales reached ¥3.52 billion compared to ¥3.10 billion last year, while year-to-date sales hit ¥24.30 billion against ¥21 billion previously reported. Additionally, Cybozu executed a share buyback plan repurchasing approximately 2.68% of shares for ¥3 billion by July 2026 end.
- Click here to discover the nuances of Cybozu with our detailed analytical health report.
Evaluate Cybozu's historical performance by accessing our past performance report.
Taking Advantage
- Investigate our full lineup of 165 Global Undiscovered Gems With Strong Fundamentals right here.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com