
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should 6G Forum Expansion Require Action From Verizon (VZ) Investors?
- Verizon Communications has expanded its 6G Innovation Forum, adding nine major partners across cloud, silicon, testing, security and devices, and reported live ISAC trials for crowd sensing and drone tracking plus an AI Sports Companion running on its edge network.
- The focus on network native sensing and AI at the edge points to Verizon Communications aiming to monetize future 6G architectures through differentiated services rather than just connectivity.
- This article examines how Verizon Communications' 6G Innovation Forum expansion and ISAC field trials could influence the company’s investment narrative.
Scan how Verizon Communications fits into the broader build-out of wireless and AI infrastructure by comparing it with hand-picked 60 AI infrastructure stocks today.
Verizon Communications Investment Narrative Recap
To own Verizon Communications, you need to believe that heavy investment in 5G, broadband, and early 6G work will translate into steady service revenue while the balance sheet digests a large debt load. In the near term, the focus remains on keeping postpaid churn low and limiting promotional intensity so margins do not erode.
The expanded 6G Innovation Forum and ISAC field trials are important for positioning but do not materially change that near-term equation yet. The biggest operational risk remains high capital intensity paired with a saturated US wireless market, which keeps execution on broadband growth and cost control at the forefront.
The Corning agreement for high-density fiber, announced on 8 September 2026, fits into the same long-term story as Verizon Communications' 6G work. Management is locking in optical capacity through 2032 to support both fixed broadband passings and the long-haul backbone needed for data-heavy AI and future wireless use cases.
On the catalyst side, that fiber supply supports the effort to reach 40 to 50 million broadband passings and underpins enterprise solutions that depend on robust connectivity. The trade-off is that capital commitments remain elevated, which matters for a company already carrying over US$100b of debt and relying on consistent free cash flow to fund dividends and network builds.
Verizon Communications' current analyst narrative points to forecast revenue of US$147.7b and earnings of US$22.4b by 2029, built on an assumed 2.0% yearly revenue growth rate and an earnings increase of about US$5.1b from US$17.3b today.
Uncover why Verizon Communications' fair value is essentially aligned with its current price.
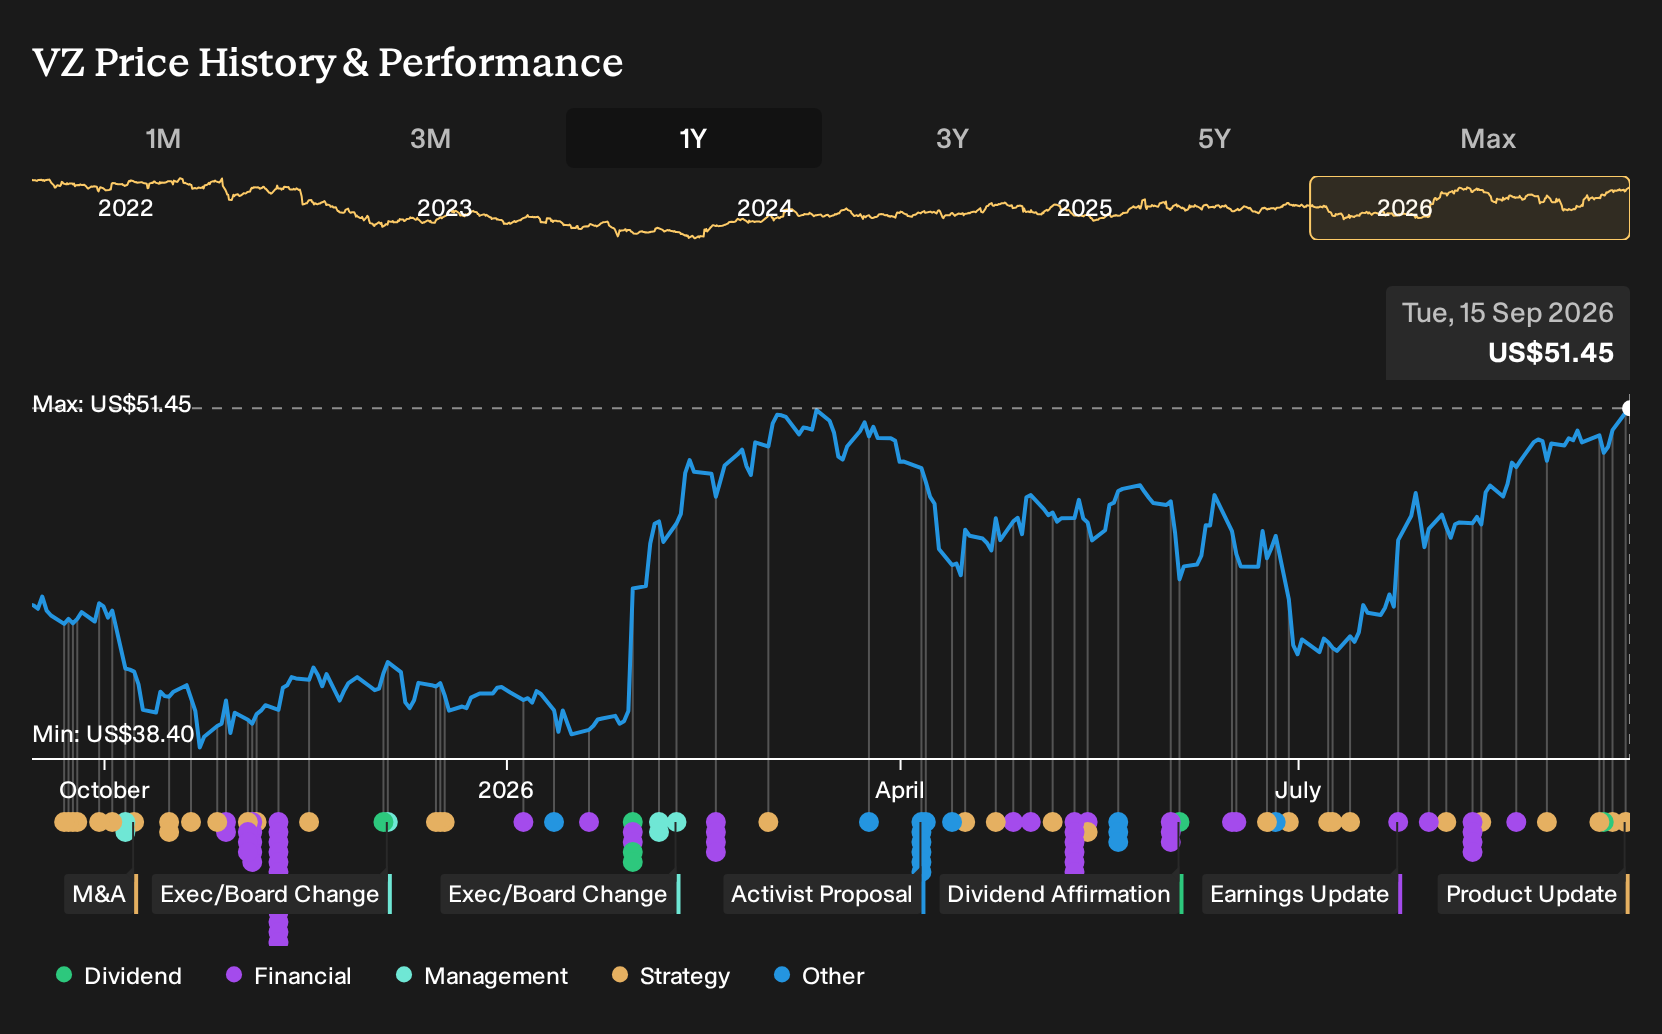
Exploring Other Perspectives
Some of the most optimistic analysts focus on Verizon Communications squeezing more out of convergence and AI than the baseline case. They were already penciling in revenue of about US$151.2b and earnings of US$25.7b by 2029. If the 6G Innovation Forum and ISAC trials reshape expectations, those projections could shift again, so compare several viewpoints before deciding what you believe.
Explore 8 other Verizon Communications fair value estimates, including one that suggests as much as 243% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Verizon Communications research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Verizon Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Verizon Communications' overall financial health at a glance.
Looking for more investment ideas beyond Verizon Communications?
Once you have a view on Verizon Communications, it can help to widen the lens and compare it with other stocks that match your risk tolerance, income needs, and time horizon using the Simply Wall St Screener.
- If you want income to play a bigger role in your portfolio, check out a focused set of income plays through 6 dividend fortresses that might suit a yield-first approach.
- If capital preservation matters just as much as return potential, start with a curated universe of steadier businesses by reviewing the 11 resilient stocks with low risk scores that pass a tighter risk filter.
- If you prefer strong balance sheets as your foundation, compare Verizon Communications with a list of solid balance sheet and fundamentals (22 results) and see which ones align with your comfort level on debt and financial resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com