
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Venture Global (VG) Stock May Be About Right After Its 117% Run
Venture Global has turned heads in 2026, with the stock moving sharply and putting fresh focus on whether its recent share price lines up with the earnings that support it. With that much momentum behind the ticker, the key issue for you is how much of the story is already reflected in the current valuation.
- Venture Global is up 117.2% year to date, which puts a lot of weight on the question of whether its earnings profile can carry a move of that size.
- News that Qatar Energy is in talks with Venture Global on multi-year LNG supply deals, alongside a new US$3b revolving credit facility, can influence expectations for how the business converts future projects into earnings and how much financing cost it needs to carry along the way.
- The analysts covering Venture Global have run their own numbers. See what analysts think Venture Global's shares could be worth.
The issue now is whether Venture Global's current share price can be squared with its earnings when measured against the Fair Ratio benchmark.
If you want to test the same earnings question that hangs over Venture Global against a wider set of LNG and energy players, scan through the 38 power grid technology and infrastructure stocks
Where Does Venture Global Sit on Earnings?
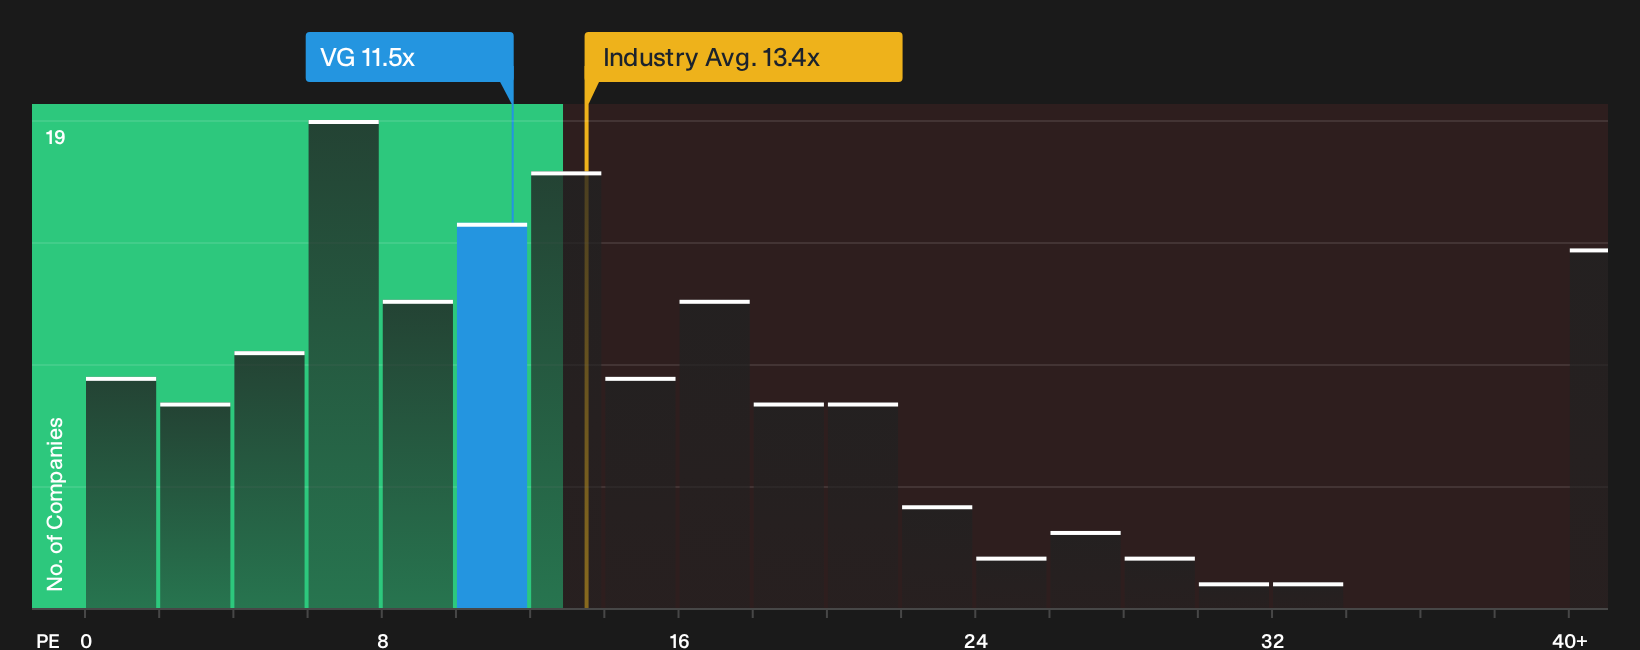
The P/E ratio is a useful lens for Venture Global because earnings are the core concern when a stock has already made a big move. Venture Global currently trades on a P/E of 11.5x, which is slightly below the Fair Ratio benchmark that reflects what you might expect given its growth profile, margins, size and risk. That puts the valuation a touch under this tailored reference point rather than at an obvious extreme.
Compared with a wider Oil and Gas group on roughly 13.4x, the stock is also priced under the sector average, and well below the peer cluster sitting around 29.6x. Because Qatar Energy is exploring multi year LNG supply deals with Venture Global, the market has a concrete potential volume driver in view, yet the P/E still prices the shares below those peer levels. The combination of a P/E just under the Fair Ratio and a discount to the broader group suggests investors are being compensated for thinking carefully about project execution, future contract visibility and balance sheet risk before deciding whether the current tag makes sense. Explore the numbers behind Venture Global's P/E valuation.
The Venture Global Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Venture Global pick up where the valuation puzzle leaves off by setting out the growth, margin and earnings paths that would need to hold for the shares to be worth meaningfully more or less than today. Each scenario on the Community page links a fair value to a specific mix of potential catalysts and risks for Venture Global so you can track which version of the story seems to be unfolding over time.
The community is split on Venture Global, with one camp seeing more runway in the LNG build out and another focused on contract risk and cash demands.
Bull case: 8% undervalued
"Industry leading construction speed, modular design and data driven operational optimization at Calcasieu Pass, Plaquemines and CP2 are lowering delivered unit costs..."
Discover why this Narrative puts Venture Global at 8% undervalued.
Bear case: 9% overvalued
"Despite entering long-term supply agreements that secure stable future revenues, the growing portion of cargos sold under non-20-year or short-term contracts could expose earnings to greater commodity price volatility..."
Explore why this Narrative puts Venture Global at 9% overvalued.
One more Venture Global puzzle that could move the story
Venture Global’s valuation only tells part of the story, because the real leverage often sits with the people calling the shots and the way their pay packets are wired. See who runs Venture Global and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com