
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Calumet (CLMT) Getting Too Pricey After Its 7x Run?
Calumet has been on a striking multi year run, and after a very large five year return, many investors are asking whether the current share price still lines up with the sales the business is generating. With the stock now at US$57.55 as of the latest close, the core issue is how much revenue power that tag really reflects.
- Over the past five years, Calumet has delivered a total shareholder return of about 7x, which puts a lot of weight on whether its sales can carry that kind of market value.
- The recent upsizing of the US$600 million senior secured revolving credit facility and the final US$34 million draw under the U.S. Department of Energy loan may support funding for Montana Renewables and could influence how investors think about future revenue scale and timing relative to the current price.
- There is a second opinion on Calumet worth weighing. See what analysts think Calumet's shares could be worth.
The issue now is whether Calumet's current valuation is justified by its sales base and how much revenue investors are effectively paying for at today's share price.
If you are weighing whether Calumet's recent five year surge is already pricing in too much sales power, it can help to compare against a focused set of 34 high quality undervalued stocks.
Does Calumet Look Pricey on Sales?
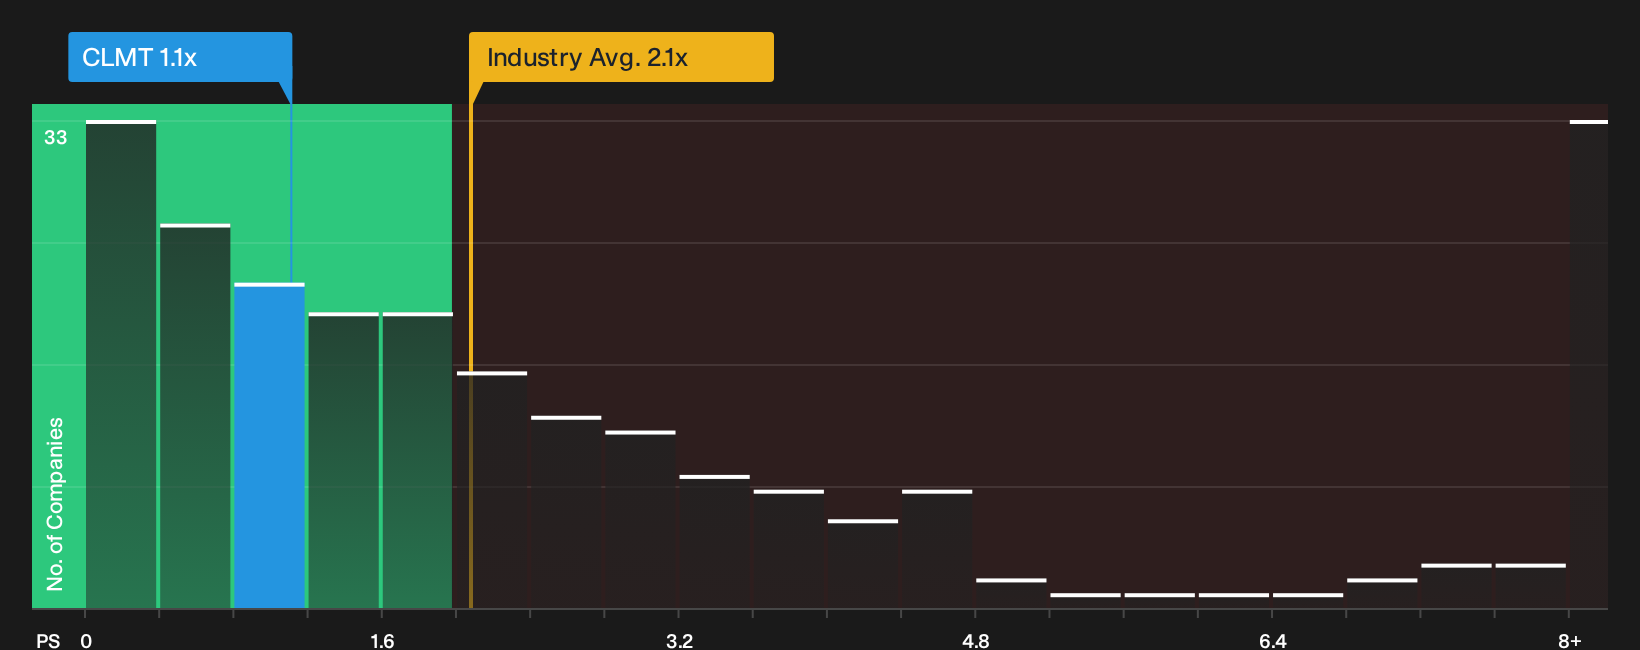
P/S fits Calumet because investors are essentially paying for future revenue capacity more than steady accounting earnings right now. On that measure, the stock trades at roughly 1.1x trailing sales, which is below the broader oil and gas industry average of about 2.1x and above a peer group closer to 0.4x.
Because that 1.1x P/S sits above the level suggested by a fair value framework that factors in Calumet's risk profile and economics, the multiple still screens as overvalued on this lens even after that discount to the wider sector. Because the recent upsizing of the US$600 million credit facility and the final US$34 million DOE loan draw sharpen the focus on Montana Renewables and potential top line scale, the current P/S asks you to pay up relative to more directly comparable stocks on similar revenue today. Explore the numbers behind Calumet's P/S valuation.
The Calumet Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where that P/S puzzle leaves off by spelling out which paths for Calumet's revenue, margins and earnings would need to play out for the current share price to look materially higher or lower over time. Each one links its number to a clear view on how growth, profitability and risk could evolve, giving you something concrete to revisit on the Community page as new information comes through.
Community views on Calumet are split between one group that sees more upside in the renewables roll out and another that focuses on balance sheet and policy risk.
Bull case: roughly fairly valued
"With the normalization of the Production Tax Credit market and the ability to regularly monetize tax credits, coupled with imminent regulatory volume increases..."
Discover why this Narrative puts Calumet at roughly fairly valued.
Bear case: 8% overvalued
"Heavy dependence on regulatory support, commodity exposure, and high leverage exposes Calumet to volatile margins, cash flow unpredictability, and constrained growth flexibility..."
Explore why this Narrative puts Calumet at 8% overvalued.
Before acting on Calumet’s valuation, there is one more angle to check
Price tags and revenue power only tell part of the story, because the people steering Calumet and the way their pay is structured can tilt risk and reward in very different directions. See who runs Calumet and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com