
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Corteva (CTVA) Just Gave Investors Something To Think About
Corteva (CTVA) just agreed to share in a US$455 million settlement tied to PFAS-related claims in North Carolina, a long-running legal overhang that now shifts into a defined, multi decade payment schedule.
Corteva shares trade at US$83.39, with an 8.75% 1 month share price return and a 23.07% year to date share price return, while total shareholder return over five years sits at 112.43%. This points to momentum building as investors digest the PFAS settlement, the planned Vylor spin off and the new Globachem joint venture.
Scan how Corteva's legal overhang and spin off story compares with other agriculture and materials stocks on our hand picked list of 11 resilient stocks with low risk scores.
For Corteva, the bullish story leans on clearer PFAS obligations and the upcoming Vylor spin, while skeptics focus on lingering legal risk and execution. Which side does the current valuation actually support next?
Most Popular Narrative: 10% Undervalued
Corteva's most followed narrative pegs fair value at $92.40, above the recent $83.39 close. This puts the current PFAS and spin off story against a modest valuation gap that hinges on execution in Seeds and Crop Protection.
Advancements in Corteva's innovation pipeline, including premium trait launches (Vorceed, PowerCore), expansion of biological products, and gene editing, enable premium pricing, secure market share, and improve product mix, translating into higher gross margins and earnings growth.
See why 27 investors see Corteva as 10% undervalued.
Result: Fair Value of $92.40 (UNDERVALUED)
Still, the bullish Corteva narrative can unravel quickly if PFAS liabilities flare up again or if the Vylor separation introduces more execution risk than clarity.
Find out about the key risks to this Corteva narrative.
Another View: What Corteva's P/E Is Really Saying
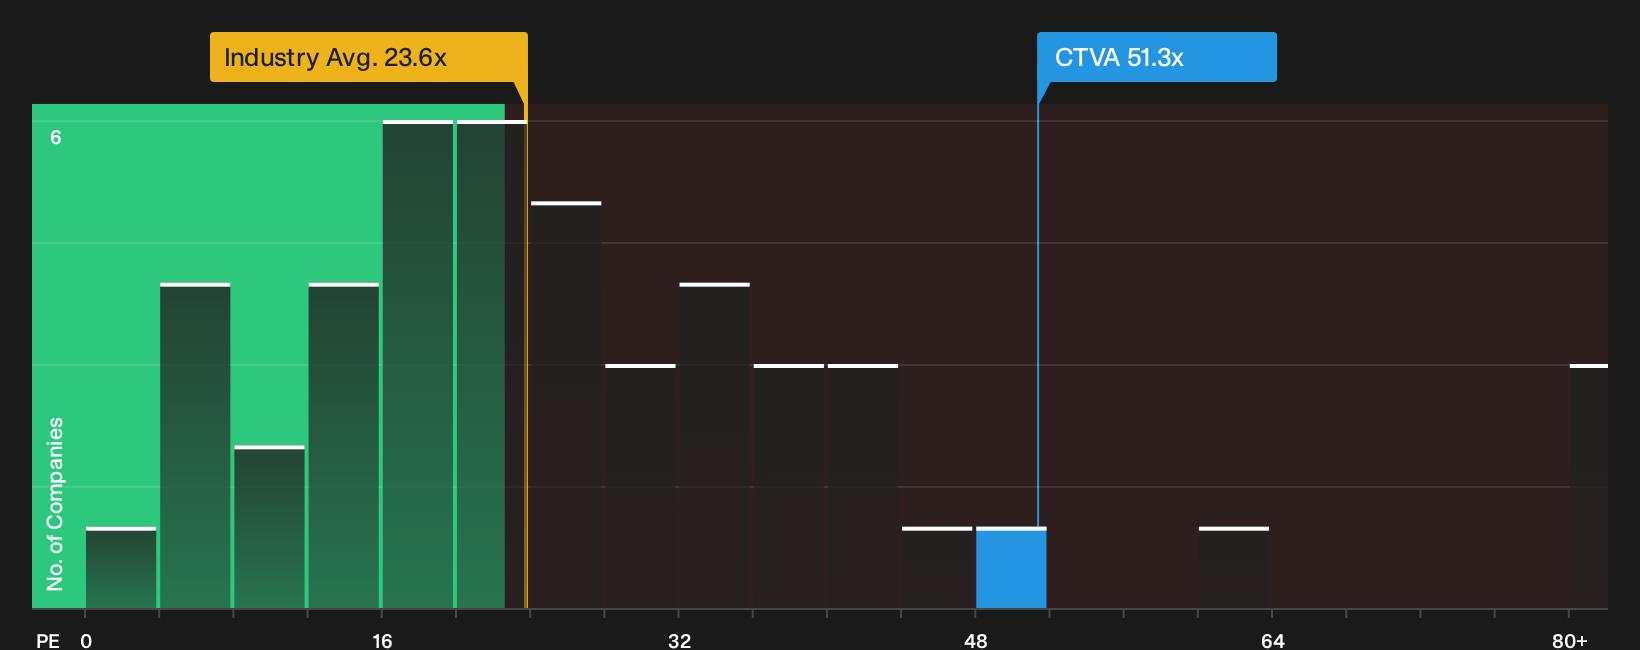
The DCF work paints Corteva as undervalued, yet the current P/E of 51.3x tells a very different story. That multiple is more than double the US Chemicals industry at 23.6x, well above peers at 15.8x, and far above a fair ratio of 26.4x that the market could move toward.
If sentiment or earnings assumptions reset toward that fair ratio, the gap between 51.3x and 26.4x becomes a real valuation risk rather than a theoretical one. The question for anyone looking at Corteva is simple: Which signal feels more fragile, the upbeat cash flow model or the rich earnings multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals on Corteva leave you split, do not wait for consensus to form. You can interrogate the numbers yourself today and weigh the trade off between legal risk and growth potential. To see how that tension shows up in the data, including both the upside and the red flags investors are watching, review the 2 key rewards and 1 important warning sign
Looking for more Corteva sized investment ideas?
Do not stop at Corteva if you want a fuller watchlist. Use targeted screeners to uncover other opportunities that fit your risk appetite and return goals.
- Target potential mispricings by scanning a curated mix of quality companies on the 34 high quality undervalued stocks.
- Build your income stream with businesses that offer higher yields and consistent payout histories through the 6 dividend fortresses.
- Strengthen portfolio resilience by zeroing in on companies with healthier finances using the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com