
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Record Output Just Shift Canadian Natural Resources Stock Investment Narrative?
- Canadian Natural Resources reported record Q2 2026 production of 1.7 million barrels of oil equivalent per day, raised its production guidance, and continued capital returns through dividends and share buybacks while lowering net debt.
- The combination of stronger output driven by drilling and acquisitions, higher guidance, and ongoing balance sheet improvement highlights how Canadian Natural Resources is using its scale to support cash generation in a volatile commodity backdrop.
- We will now look at how Canadian Natural Resources' higher production guidance could reshape the investment narrative investors use to judge it.
Compare Canadian Natural Resources’ production driven story with other large commodity players by scanning our hand picked list of solid balance sheet and fundamentals (7 results), which may also appeal to cash flow focused investors.
Canadian Natural Resources Investment Narrative Recap
To own Canadian Natural Resources, you need to believe the company can keep turning its long-life oil sands and broader asset base into consistent cash, even if commodity prices swing and industry demand changes over time. The record Q2 2026 output and higher guidance sharpen that thesis by showing the portfolio can support higher volumes without blowing out the current capital budget.
The near term swing factor is operational delivery on that elevated production guidance while keeping costs and downtime in check. The biggest risk right now sits in the same place as the reward. Heavy exposure to oil sands leaves Canadian Natural Resources sensitive to future regulatory changes, carbon costs, and any pressure on Canadian pipeline and export capacity.
The raised 2026 production guidance is the announcement that matters most for this story. Management has already pointed to an 18% year on year lift in Q2 volumes to 1.7 million barrels of oil equivalent per day, helped by acquisitions and prior capital spending. That step up now needs to translate into reliable throughput and disciplined maintenance in the second half.
For catalysts, higher production against a largely fixed cost base can support free cash generation. Canadian Natural Resources has been using this for dividends, buybacks, and debt reduction. Execution risk sits around integrating acquired assets cleanly and operating large oil sands projects under evolving environmental and policy rules in Canada. Any surprise on those fronts can quickly matter more than headline volume growth.
What The Analyst Forecasts Assume For Canadian Natural Resources
Canadian Natural Resources' current analyst narrative points to forecast revenue of CA$40.1b and projected earnings of CA$8.6b by 2029. To line up with that view, analysts are assuming revenue growth of 1.3% per year and an earnings decrease of CA$1.1b from CA$9.7b today.
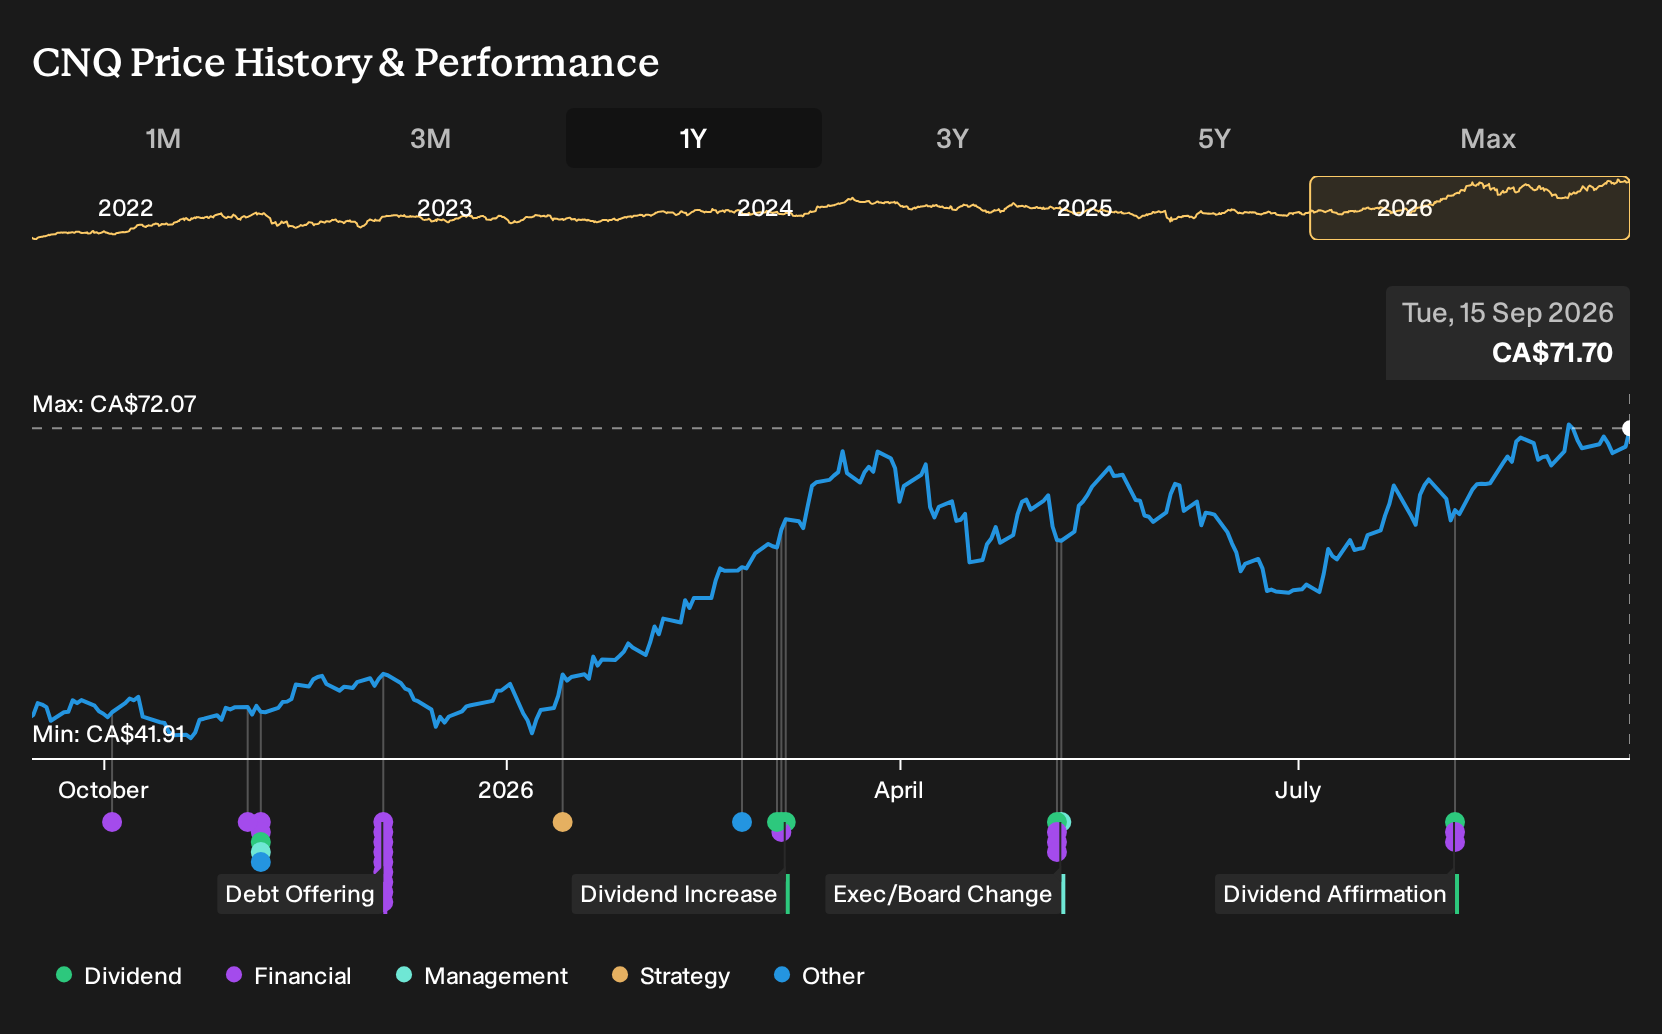
Uncover why Canadian Natural Resources' fair value is essentially in line with its current price.
Exploring Other Perspectives
One alternate storyline for Canadian Natural Resources leans heavily on tighter carbon rules. The most pessimistic analysts were already assuming revenue would decline 5.2% a year and earnings would slide from about CA$11.8b to CA$5.5b by 2029. The fresh production news could challenge that view, so treat it as a prompt to compare several narratives.
Explore 3 other Canadian Natural Resources fair value estimates, including one that suggests it could be worth just CA$71.20.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Canadian Natural Resources research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Canadian Natural Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian Natural Resources' overall financial health at a glance.
Looking for more Canadian Natural Resources style ideas?
If Canadian Natural Resources has sharpened your focus on balance sheets, cash generation, and capital returns, it can help to line that up against a wider watchlist built from similar filters.
- For potential mispriced opportunities with robust fundamentals, start by scanning the 3 high quality undervalued stocks that meet a combination of quality and value checks.
- If predictable cash payouts matter to your plan, review the income focused options in the 2 dividend fortresses that match your yield and stability preferences.
- For investors who care most about resilience, filter for companies with healthier finances and cleaner leverage profiles using the 1 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com