
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Danieli & C. Officine Meccaniche (BIT:DAN) Wins Tanzania Mill Deal As Valuation Questions Return
Danieli & C. Officine Meccaniche (BIT:DAN) is back in focus after group unit Danieli Technologies won a contract to supply a new rebar and wire rod mill at Tanzania’s Kilimanjaro Industrial Park.
The contract arrives after a choppy few months for Danieli & C. Officine Meccaniche, with the share price down about 13% over 30 days and 26% over 90 days, yet still up year to date and supported by a 1-year total shareholder return of roughly 43%, which points to longer term momentum despite recent weakness.
Scan other steel and capital-goods opportunities moving on contract wins and infrastructure demand by checking the hand-picked list of solid balance sheet and fundamentals (195 results) that may echo Danieli & C. Officine Meccaniche's profile.
Danieli & C. Officine Meccaniche now trades at about a 13% discount to one intrinsic estimate and roughly 40% below analyst targets. Is that mispricing after the recent pullback, or a fair reflection of risk?
Preferred P/E of 17.8x: Is it justified?
On current numbers, Danieli & C. Officine Meccaniche screens as cheap against several valuation yardsticks, even after a strong 1-year share price run. The stock closed at €56.15, while analysts collectively point to a target near €78.33 and one intrinsic estimate sits at €64.71, which leaves a sizeable gap between market price and various reference values.
The preferred yardstick here is the P/E ratio, because Danieli & C. Officine Meccaniche is a mature, earnings-generating industrial group where profits tend to be a key focus for investors. The shares trade on a P/E of 17.8x, compared with an estimated fair P/E of 20.8x. The business has grown earnings by 17.4% per year over the past 5 years, although the most recent year saw earnings decline 16.1%, which introduces a clear note of caution.
Even with that recent setback, the current valuation sits below both peers and the fair ratio. Management is expected to lift earnings by about 11.7% per year, analysts forecast revenue growth of 5.5% per year, and return on equity is projected at 9.7% in three years. Taken together, these figures indicate that the P/E could plausibly move closer to the estimated 20.8x level if those forecasts hold.
Price comparisons are also unambiguous. The stock trades on 17.8x earnings against a peer average of 32x and a European machinery sector average of 20.1x. It is still sitting 13.2% below one fair value estimate and around 39.5% under the consensus target price, which shows the market is currently attaching a clear discount to this earnings profile.
Explore the SWS fair ratio for Danieli & C. Officine Meccaniche.
Result: Price-to-earnings of 17.8x (UNDERVALUED)
Still, Danieli & C. Officine Meccaniche depends heavily on cyclical steel investment, and any setback on major contracts could quickly test that apparent valuation gap.
Find out about the key risks to this Danieli & C. Officine Meccaniche narrative.
Another view on Danieli & C. Officine Meccaniche
The SWS DCF model points to a fair value near €64.71 for Danieli & C. Officine Meccaniche, with the current €56.15 price sitting about 13% below that estimate. That still signals undervaluation, but DCFs lean heavily on long term cash flow assumptions. How comfortable are you with those inputs holding up?
Look into how the SWS DCF model arrives at its fair value.
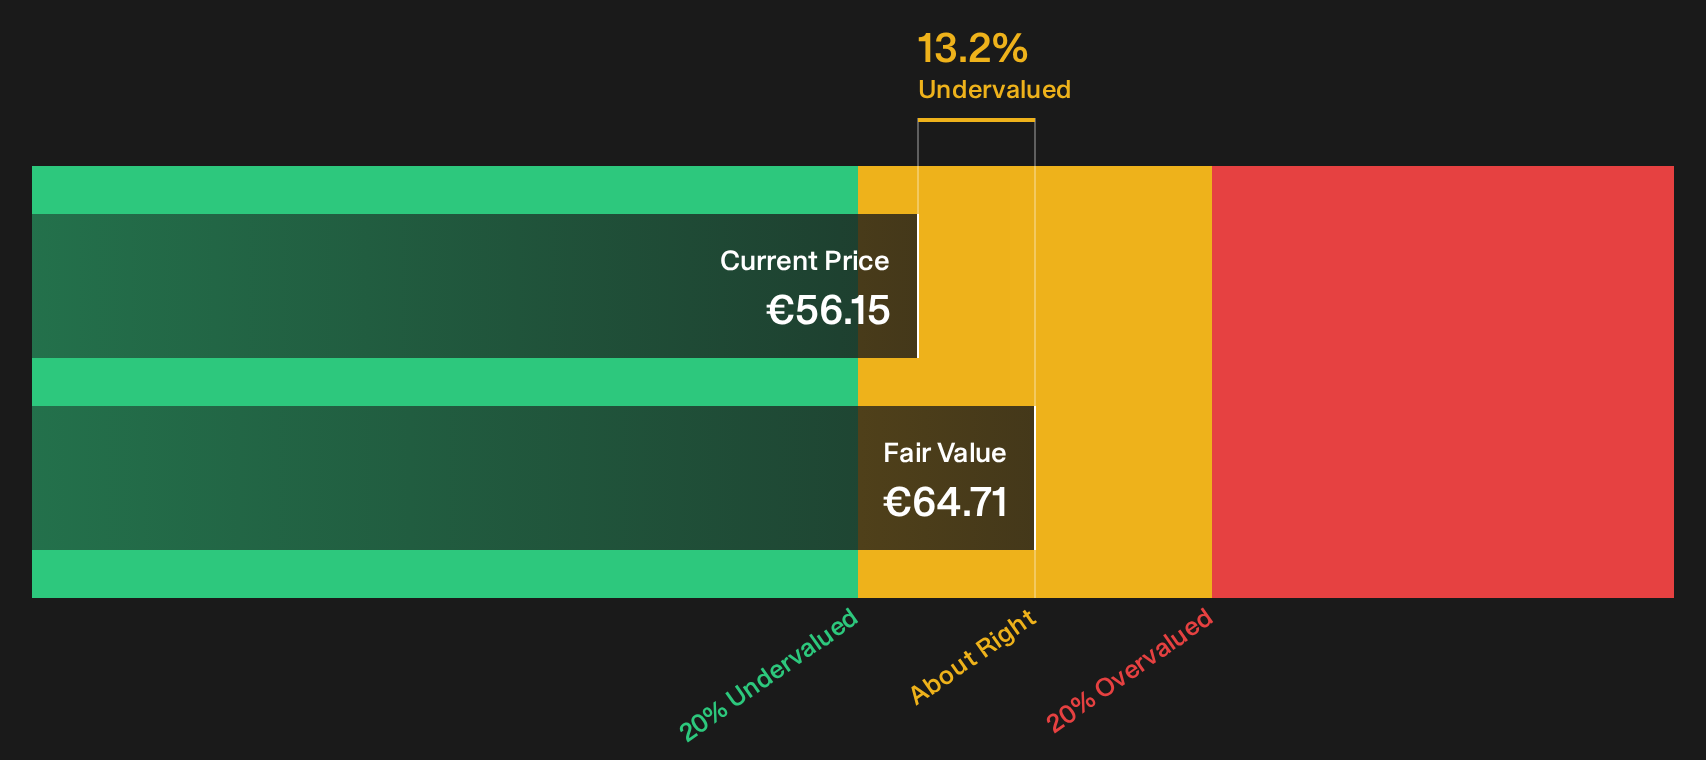
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Danieli & C. Officine Meccaniche for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Opinions on Danieli & C. Officine Meccaniche will differ. Move quickly, review the full picture, and weigh the 4 key rewards against the risks you see.
Looking for more investment ideas beyond Danieli & C. Officine Meccaniche?
If you only stop at Danieli & C. Officine Meccaniche, you could miss other setups where price, quality, and risk all line up in your favour.
- Hunt for quality at a discount by scanning the 194 high quality undervalued stocks that line up strong fundamentals with prices that trail their underlying strength.
- Lock in potential income streams by reviewing the 161 dividend fortresses that pair higher yields with balance sheets built to support regular payouts.
- Tilt your watchlist toward resilience by checking the 102 resilient stocks with low risk scores that keep volatility in check while still offering meaningful upside potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com