
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tyra Biosciences (TYRA) Stock May Stay Pricey Following Mixed Trial Data
Tyra Biosciences has seen a sharp reset in sentiment after mixed bladder cancer trial data, and the stock is still sitting on a very strong 1 year gain. That combination puts a simple but important question on the table for investors who follow Tyra Biosciences, whether the current price can be squared with what its balance sheet and book value actually support.
- Over the past 12 months, Tyra Biosciences has returned about 105.7%, which raises the issue of how much of that move is backed by its underlying net assets.
- Mixed Phase 2 results for oral dabogratinib and plans for further development, alongside a large equity and warrant offering of roughly US$400b, may affect how investors weigh future funding needs against the value already on Tyra Biosciences' books.
- Your read on Tyra Biosciences is one view; the desks covering it have another. See what analysts think Tyra Biosciences's shares could be worth.
The issue now is whether Tyra Biosciences' recent share price level is justified when set against its book value and how that compares with the industry average.
If you want to stress test this same book value question beyond Tyra Biosciences, line it up against other companies using the 34 high quality undervalued stocks
Does Tyra Biosciences Look Pricey on Book Value?
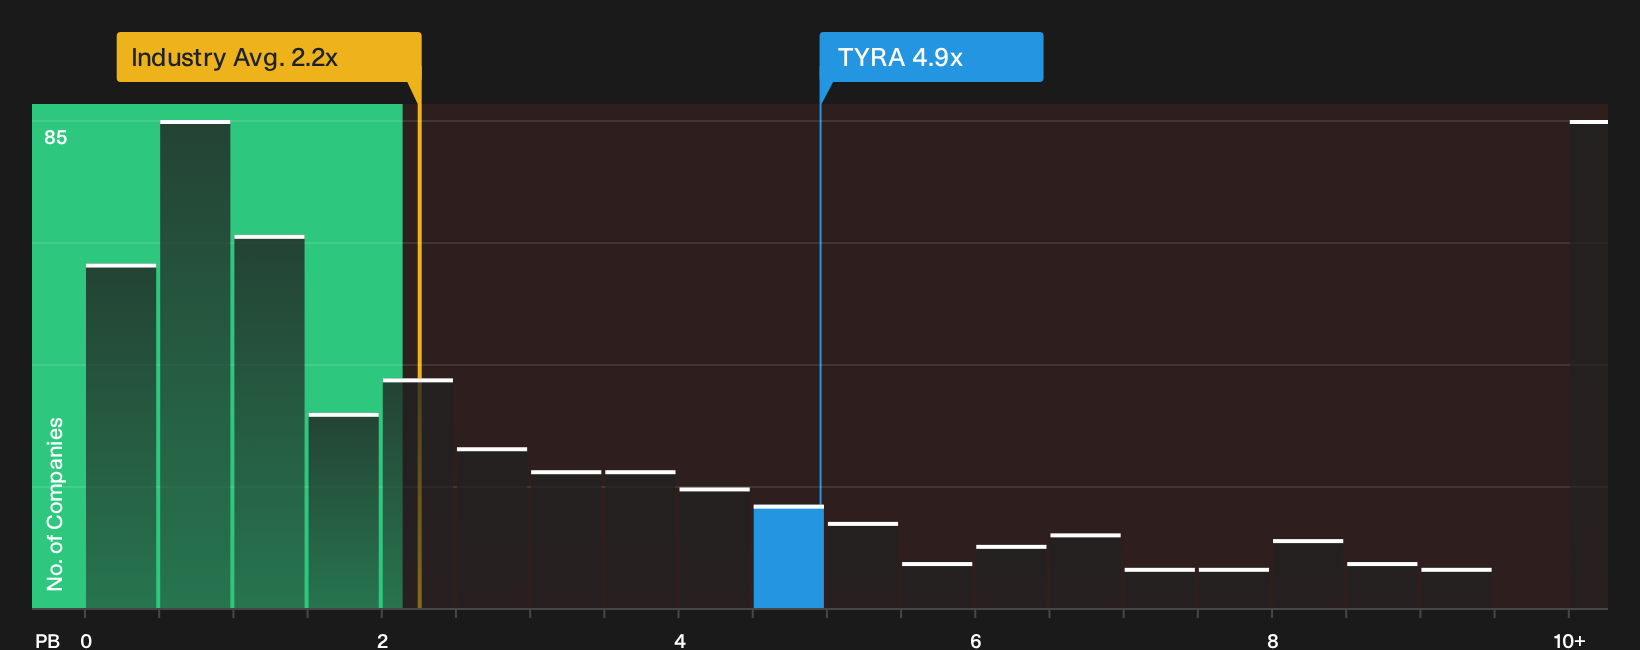
P/B fits Tyra Biosciences because investors are mainly weighing its research pipeline against the net assets backing the business. The current P/B of roughly 4.9x sits above the broader Biotechs industry average of about 2.2x and a little below the peer group near 5.7x, so the share price reflects a richer valuation than the typical sector player on this yardstick.
Because the bladder cancer data left some investors disappointed, the recent pullback has not fully erased the premium, which still screens as overvalued relative to the industry. For anyone assessing Tyra Biosciences today, that means the stock price already assigns a relatively high value to its balance sheet and future execution compared with many other Biotechs on a simple P/B view. Explore the numbers behind Tyra Biosciences's P/B valuation.
The Tyra Biosciences Narrative: What Would Justify Today's Price?
Narratives on Tyra Biosciences sit on Simply Wall St's Community page and turn the valuation gap above into concrete what-if scenarios, spelling out which paths for growth, profitability and earnings would need to play out for the shares to be worth materially more or less than today. Each one links a specific set of potential catalysts and risks to its own view of fair value, so you can track over time which story is gaining the most evidence.
A written, number driven view on Tyra Biosciences forces you to spell out exactly what assumptions you are making about dabogratinib's mixed bladder cancer data and the roughly US$400m equity and warrant raise, and then check those expectations against the actual trial and funding milestones as they arrive. That kind of explicit framework helps you keep track of whether the share price is moving because those assumptions are being confirmed or challenged over time.
Share your own Narrative for Tyra Biosciences and set out the assumptions behind your valuation.
One more piece of the Tyra Biosciences puzzle before you move on
Before acting on where Tyra Biosciences trades against its assets, it helps to see how professional analysts map the next few years for this business and whether that rough sketch lines up with your own view. Explore where analysts expect Tyra Biosciences to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com