
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Dividend Payout Require Action From Extra Space Storage Stock Investors?
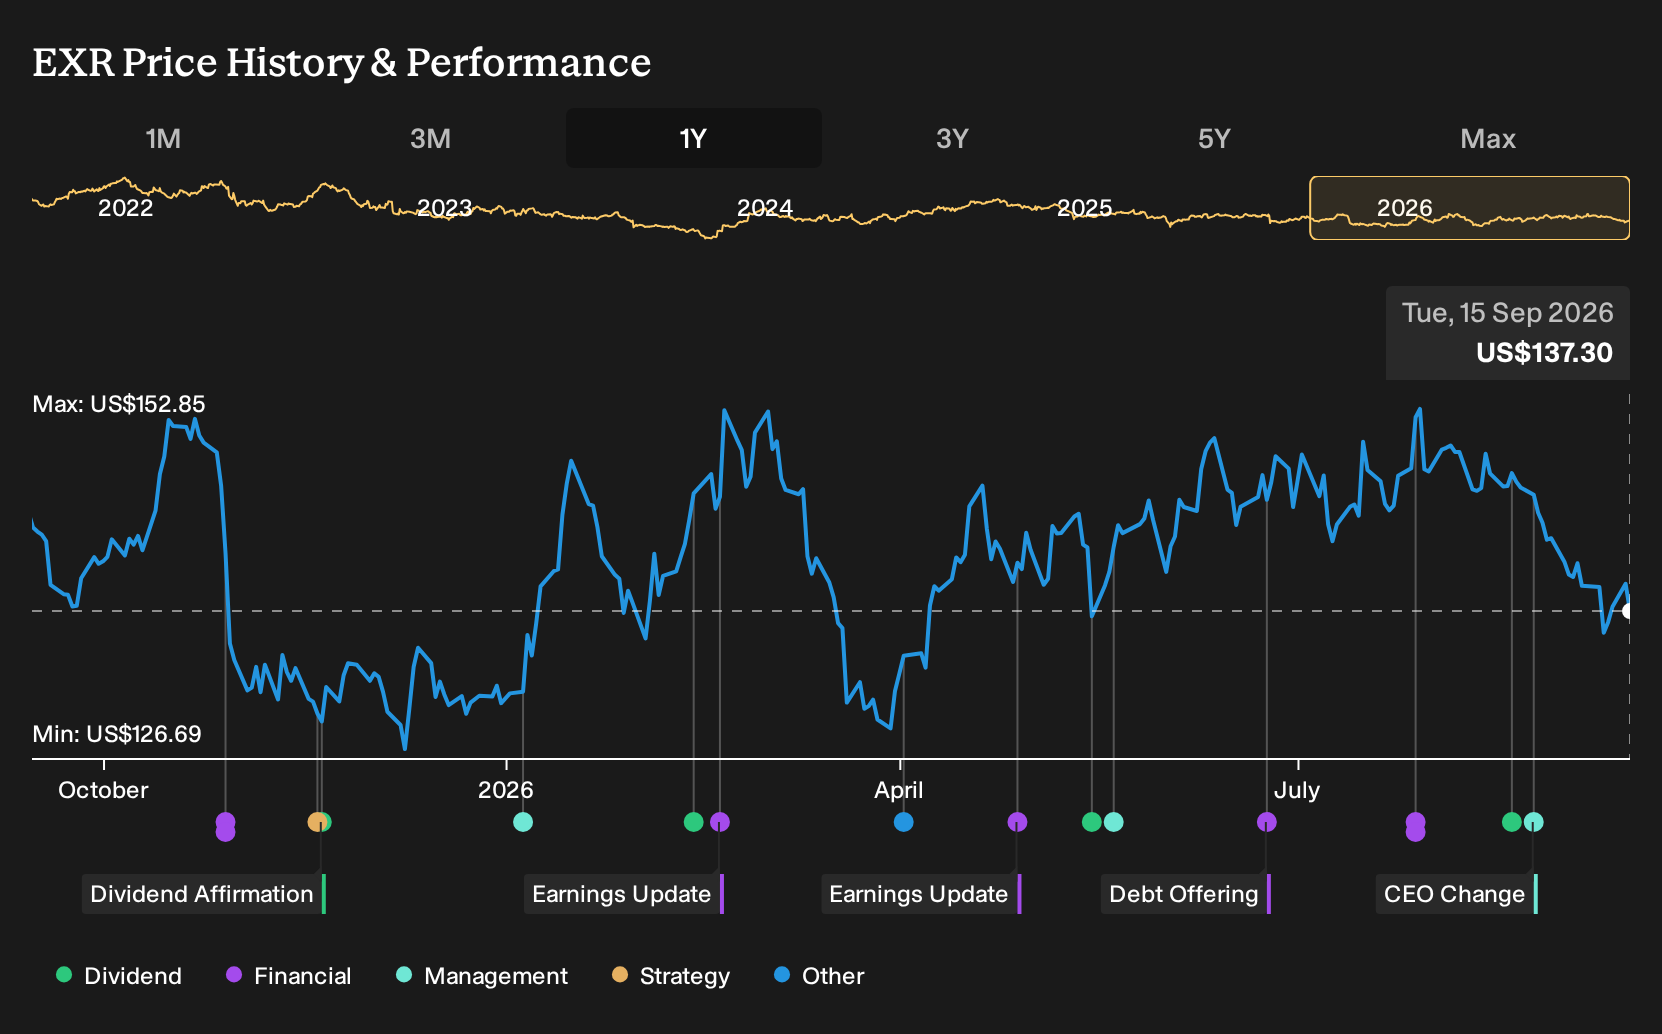
- Extra Space Storage recently paid a total dividend of $1.62 per share after the September 15 ex-dividend date, extending a track record of regular distributions that dates back to 2004.
- The payout has risen every year since 2009; however, a high payout ratio and recently weaker EPS raise questions about how far future dividend increases can stretch without pressuring financial flexibility.
- Next, the focus will shift to how Extra Space Storage's dividend record, and its strain on earnings, shapes the broader investment narrative.
Compare Extra Space Storage's income profile with a curated group of real estate stocks on our 6 dividend fortresses to see how other payout stories stack up against this headline.
Extra Space Storage Investment Narrative Recap
For an investor to stay with Extra Space Storage, the core belief is that dense urban markets, steady storage demand and its large US footprint can support durable cash generation, even while headline growth is subdued. The current backdrop is tougher. Same store revenue guidance is flat, new supply weighs on pricing and property taxes keep chewing into margins.
The recent US$1.62 dividend underscores that the REIT still leans on income as its calling card. Yet a high payout ratio and weaker EPS make the distribution policy the key short term swing factor. The main risk is pressure on financial flexibility if earnings stay soft while property costs and interest expense remain stubborn.
The fresh dividend announcement is the most relevant development for that story. Extra Space Storage is signaling commitment to a long running income stream at a time when revenue growth is muted and net profit margins have slipped from 28.8% to 27.2%. That decision keeps the focus squarely on cash flow quality and balance sheet headroom.
For catalysts, investors will likely watch how the payout interacts with debt coverage and modestly forecast earnings growth of 5.1% a year. If management can protect occupancy, grow ancillary fee income and manage property tax creep while still servicing obligations comfortably, the current dividend profile could remain a central part of the Extra Space Storage thesis.
Extra Space Storage's narrative projects US$3.3b revenue and US$1.1b earnings by 2029. This assumes revenue declines by 2.1% a year and requires an earnings increase of about US$144m from US$956.1m today.
Discover how Extra Space Storage's fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Simply Wall St Community members have produced 2 fair value estimates for Extra Space Storage that cluster in a tight US$159.65 to US$167.60 band, yet many on Wall Street still flag moderate growth concerns as new supply, tax pressure and changing digital search habits bite. You can use these contrasting viewpoints to stress test your own thesis.
Explore another Extra Space Storage fair value estimate, including one that suggests it could be worth just $159.65.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Extra Space Storage research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Extra Space Storage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Extra Space Storage's overall financial health at a glance.
Looking For More Ideas Beyond Extra Space Storage?
If the Extra Space Storage story has sharpened your focus on income, quality and risk, the next step is lining up a broader watchlist that fits your preferences. The Simply Wall St Screener can help you filter for different flavours of opportunity so you are not relying on a single dividend REIT to carry your portfolio income goals.
- For income seekers who want yield with resilience, you can filter for large, consistent payouts supported by solid metrics through our 6 dividend fortresses.
- If valuation discipline sits at the top of your checklist, you can scan for attractively priced businesses with strong fundamentals using the 34 high quality undervalued stocks.
- For readers hunting for future leaders before they hit the spotlight, you can surface underfollowed companies with robust balance sheets and earnings quality through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com