
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
LCI Industries (LCII) Stock May Be Reasonable As AI Planning Shifts The Story
LCI Industries has seen a sharp reset in sentiment this year, and the question now is whether the current share price lines up with what its earnings realistically support. With the stock under pressure, investors are weighing how recent developments at the business feed into that earnings picture.
- The share price is down 29.5% year to date, which puts the spotlight firmly on whether the earnings profile still justifies where LCI Industries trades today.
- Lippert's move to adopt an AI native supply chain planning platform can influence future cost efficiency and working capital needs, which in turn may reshape how investors think about the durability of its earnings power.
- Your read on LCI Industries is one view; the desks covering it have another. See what analysts think LCI Industries's shares could be worth.
The issue now is whether LCI Industries' current valuation is adequately supported by the earnings the business is generating today and is expected to produce over time.
If you want to test the same earnings question you are asking of LCI Industries across a wider watchlist, scan through 34 high quality undervalued stocks.
Is LCI Industries Still Cheap on Earnings?
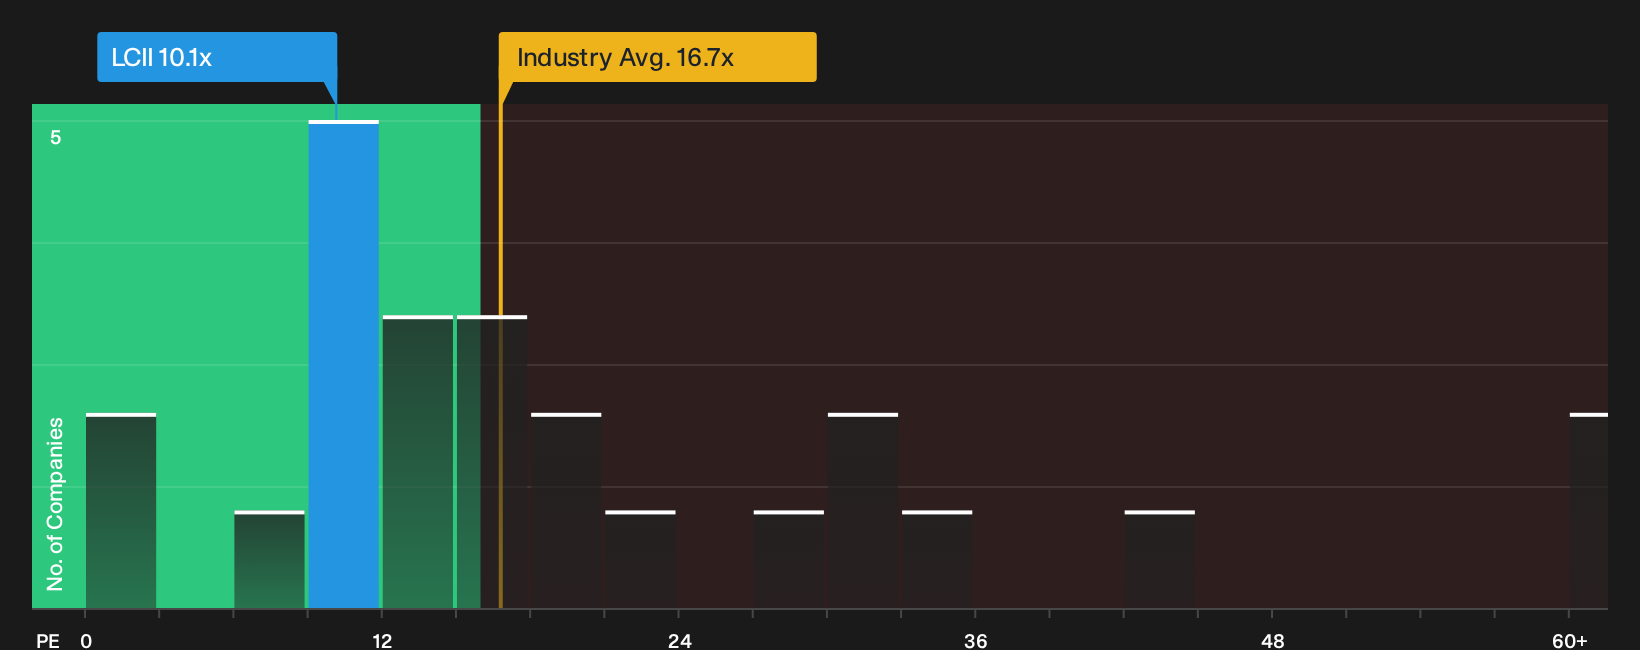
The P/E ratio works well for LCI Industries because earnings are a key focus for how investors frame this business. On that basis, the stock trades on a P/E of about 10.1x, compared with an Auto Components industry average near 16.7x and a peer group around 14.1x. That places LCI Industries at a clear discount to both its sector and similarly followed companies on earnings alone.
Given the fair multiple implied by the valuation model, which factors in the firm's margins, expected cash flows, size and risk profile, the current P/E sits below where you might expect the shares to trade. Because Lippert is rolling out an AI native supply chain planning platform that could influence how investors view its cost base and resilience, that discount on earnings may draw extra attention from readers who think the earnings profile can hold up. Explore the numbers behind LCI Industries's P/E valuation.
The LCI Industries Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the valuation puzzle for LCI Industries leaves off by spelling out which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s share price, and they sit on the Community page. Each one treats LCI Industries' fair value as a thesis you can track over time, rather than a single frozen snapshot of the business.
One of the top community narratives on LCI Industries: 47% undervalued
"LCI's recent entry and rapid expansion in essential municipal bus markets and utility trailers ..."
Discover why this Narrative puts LCI Industries at 47% undervalued.
One more angle on LCI Industries that could change how you see the whole story
Everything so far has focused on what LCI Industries looks like today, but professional analysts have mapped out where they think earnings and cash flows go next, and that checklist can sharpen how you read the current pricing. Explore where analysts expect LCI Industries to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com