
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Privacy Settlement Just Shift Grindr (GRND) Investment Narrative?
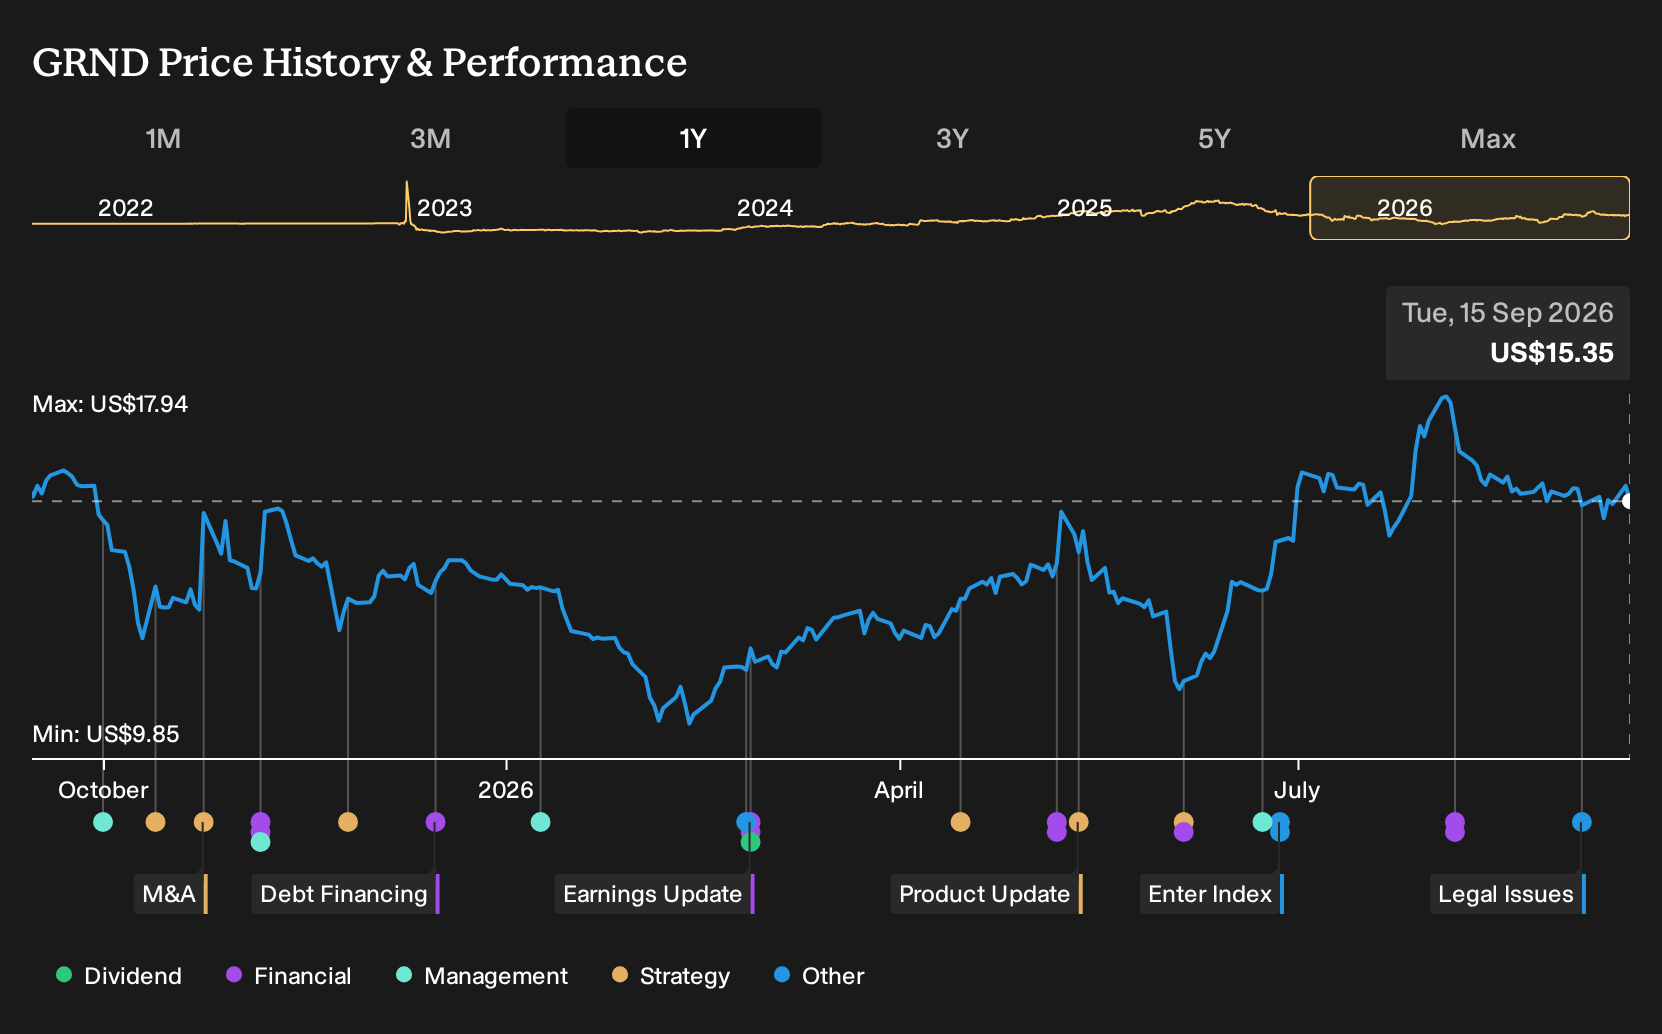
- Grindr has resolved a long running UK group action over alleged pre 2020 privacy violations, agreeing to pay £13.0 million by December 31, 2026 and £13.0 million by March 31, 2027, without any admission of liability.
- The settlement removes a specific legal overhang tied to Grindr’s historical data practices and also highlights that current management has rebuilt its privacy framework since ownership changed and the business listed on the NYSE.
- We will now look at how Grindr's updated privacy footing and settlement obligations could reshape the existing investment narrative for investors.
Scan how Grindr’s privacy reset compares with other platforms that treat user trust as a financial asset by reviewing our hand picked 11 resilient stocks with low risk scores.
Grindr Investment Narrative Recap
To own Grindr, you need to believe the app can keep growing its LGBTQ community, lift ARPU through premium tiers and ads, and manage heavy product spending without eroding profitability. The UK settlement looks contained in size and timing, so it mainly cleans up an old issue rather than changing the near term operating story.
The more pressing swing factor is execution on product and AI features while controlling costs, especially with elevated stock based compensation and high debt. The biggest risk remains that expenses stay high just as user growth or monetization slows, which could pressure margins and test the current valuation.
The upcoming appearance by George Arison at the Goldman Sachs Communacopia + Technology Conference on September 10, 2026 now matters more. Investors will likely watch for clear commentary on how the privacy overhaul, legal settlement, and ongoing regulatory scrutiny shape product roadmaps and compliance spending from here.
That conference slot also gives Grindr a stage to talk about user trends, premium tier traction, ad partnerships and international expansion, all of which tie directly into revenue and earnings forecasts. Any extra detail on debt, negative equity and capital allocation could help you judge whether the balance between growth investment and financial risk feels acceptable.
Grindr's narrative projects US$794.3 million revenue and US$166.1 million earnings by 2029. That implies 15.9% yearly revenue growth and an earnings increase of about US$80.4 million from US$85.7 million today.
Uncover how Grindr's fair value indicates a 36% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view on Grindr leans hard into the risk that premium AI tiers like Edge and higher priced XTRA and Unlimited plans never really scale. The most cautious analysts were only penciling in about US$796.2 million of revenue and US$160.2 million of earnings for 2029. Those projections came before this privacy settlement and the upcoming Goldman Sachs conference, so you may see some opinions shift as new information lands.
Explore 4 other Grindr fair value estimates, including one that suggests as much as 8% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Grindr research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Grindr. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Grindr's overall financial health at a glance.
Looking For More Investment Ideas Beyond Grindr?
If Grindr is already on your watchlist and you want a broader shortlist to compare it against, the Simply Wall St Screener can surface other stocks that match the kind of risk and quality profile you care about most.
- If capital preservation ranks high for you, start with a 11 resilient stocks with low risk scores that can help you focus on companies with steadier risk profiles.
- If you are hunting for quality at a sensible entry point, scan a 34 high quality undervalued stocks that may trade below what their fundamentals suggest.
- If you want ideas that combine resilience with cash strength, filter through a list of solid balance sheet and fundamentals (22 results) that pair sturdier finances with fundamental support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com