
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Honeywell Aerospace (HONA) As Defense Spending Buzz Meets A Cheaper Valuation
Geopolitical strain and a proposed record US$1.15 trillion U.S. defense budget in the 2026 National Defense Authorization Act have pushed defense spending into focus, putting Honeywell Aerospace (HONA) and its recent spin off firmly on investor radars.
The recent spin off has not insulated Honeywell Aerospace from market pressure, with the 90 day share price return down 41.29% and the year to date share price return down 20.75% even after a 1.98% gain over the past week. That pattern suggests momentum has faded despite the proposed US$1.15t defense budget, as investors weigh the large contract backlog against a sharp reset in expectations around risk and future cash generation at a last close of US$158.495 per share.
Scan defense and aerospace peers reacting to the same US$1.15t budget tailwind using our curated list of 38 power grid technology and infrastructure stocks
For Honeywell Aerospace, that sharp reset in the share price now sits between two stories. Is this mostly about sentiment after the spin off, or does it better reflect what the business is currently worth on the numbers?
Price-to-Earnings of 25.8x for Honeywell Aerospace: Is it justified?
On simple numbers, Honeywell Aerospace looks cheap next to its peers. The stock trades on a P/E of 25.8x while the broader US Aerospace & Defense group sits at 34.2x and the selected peer set averages a far richer 71.4x. That gap sits alongside a last close of $158.50 and a business generating $19.46 in net income on $17.92b of revenue.
The P/E ratio compares what investors are willing to pay today for each dollar of earnings generated by Honeywell Aerospace. For a sector built around long contracts, heavy capital needs and multi decade programs, earnings carry a lot of information about how reliably cash can be turned out of that backlog over time.
Here, a lower P/E than both the industry and peer averages suggests the market is attaching a more cautious earnings tag to Honeywell Aerospace. This is despite revenue growth of 9.2% over the past year and what appears to be high quality earnings. At the same time, profit margins have moved from 16.8% to 10.9%, liabilities exceed assets and debt is not well covered by operating cash flow. All of these factors can justify some discount if investors are questioning balance sheet strength and the impact of negative earnings growth of 29.3% over the last year.
Against that backdrop, the share price still reflects a company that analysts expect to grow earnings by 16.2% a year, with revenue forecast to rise 7.3% annually. The stock also screens as good value on several fronts, including a 38.4% discount to an estimated future cash flow value of $257.46 and a 33.1% gap to the $211.00 analyst price target. Taken together, the P/E of 25.8x looks materially lower than what the market is paying for comparable aerospace and defense stocks, even after factoring in the reset in margins, new management and board, and a balance sheet built entirely on higher risk borrowing.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 25.8x (UNDERVALUED)
Still, Honeywell Aerospace faces real pressure points if margins remain compressed and debt-reliant funding coincides with any slowdown in contract awards or delayed government spending.
Find out about the key risks to this Honeywell Aerospace narrative.
Another view on Honeywell Aerospace using cash flows
Price tags tell one story. For Honeywell Aerospace, the SWS DCF model adds a different angle by estimating a future cash flow value of $257.46 per share, versus the current $158.50 price, which screens as undervalued on this metric. If cash generation delivers as modeled, the gap could be interpreted as a margin of safety or as a warning on the underlying assumptions.
Look into how the SWS DCF model arrives at its fair value.
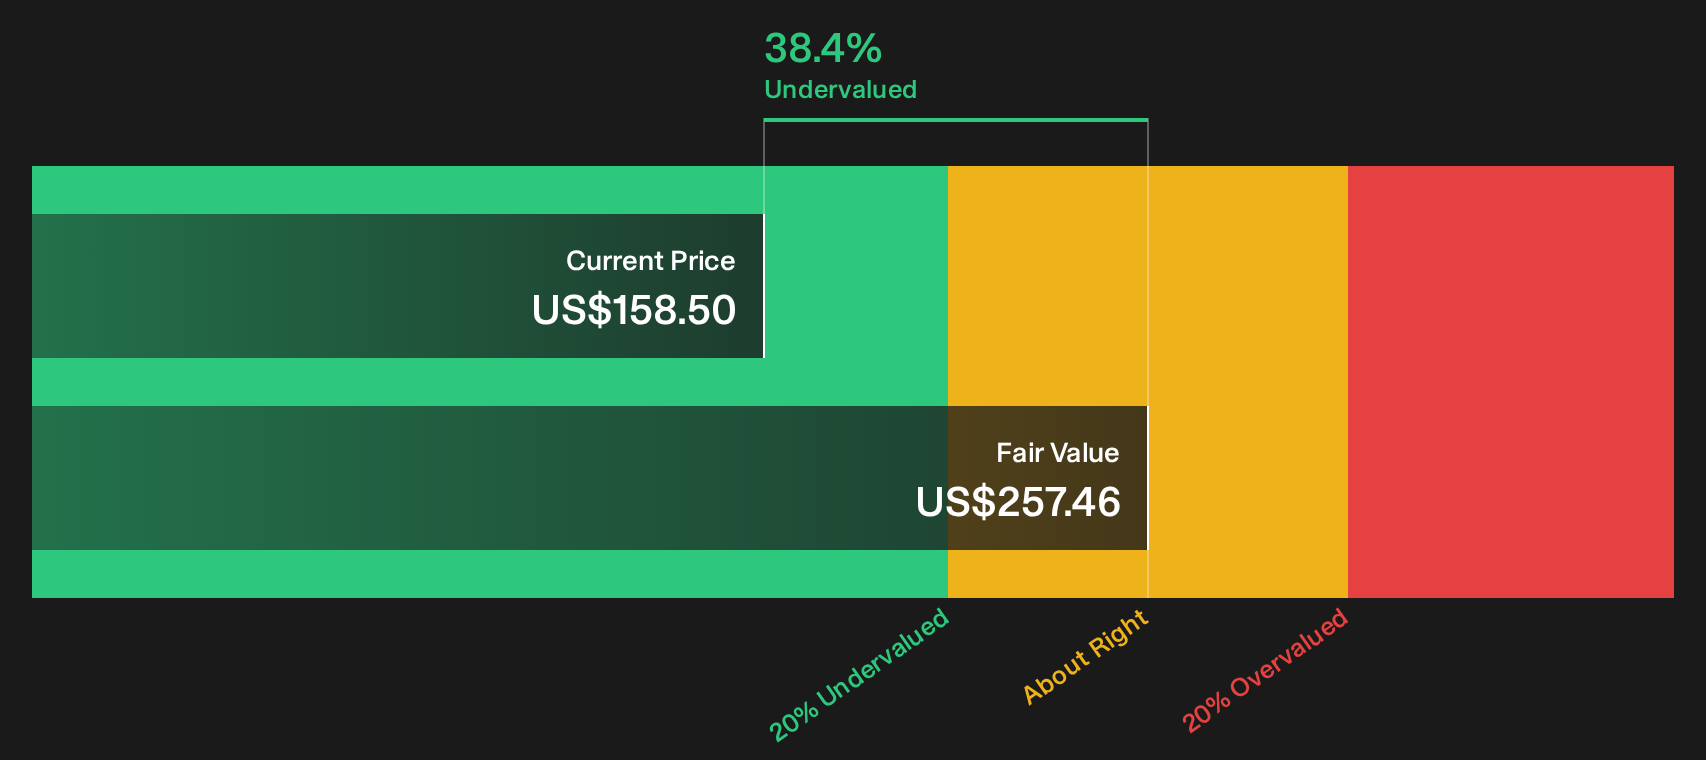
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Honeywell Aerospace for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Honeywell Aerospace so far. If you want to move fast and make up your own mind, start by weighing the 4 key rewards and 4 important warning signs.
Looking for more Honeywell Aerospace style investment ideas?
Do not stop with Honeywell Aerospace. Use the same clear, numbers first thinking to find opportunities that better match your risk comfort and return goals.
- Target potential value opportunities by scanning the 34 high quality undervalued stocks that combine lower prices with stronger fundamentals than the broader market.
- Prioritize stability and capital strength by reviewing the list of solid balance sheet and fundamentals (22 results) so you are not caught off guard by weak financial foundations.
- Identify possibilities by filtering for 16 high quality undiscovered gems to see companies that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com