
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 European Stocks Estimated To Be Trading Up To 49.8% Below Intrinsic Value
The European stock market has faced recent pressures, with the STOXX Europe 600 Index declining as geopolitical tensions and rising energy prices stoke inflation concerns. Amidst these challenges, investors are increasingly on the lookout for stocks that may be undervalued relative to their intrinsic value, offering potential opportunities in a fluctuating economic landscape.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Voxel (WSE:VOX) | PLN141.80 | PLN269.39 | 47.4% |
| Sulzer (SWX:SUN) | CHF144.70 | CHF288.01 | 49.8% |
| Promotica (BIT:PMT) | €3.10 | €5.81 | 46.7% |
| Marimekko Oyj (HLSE:MEKKO) | €9.39 | €16.82 | 44.2% |
| KSB SE KGaA (XTRA:KSB) | €904.00 | €1765.14 | 48.8% |
| Kalmar Oyj (HLSE:KALMAR) | €38.84 | €65.82 | 41% |
| Embla Medical hf (CPSE:EMBLA) | DKK27.20 | DKK46.38 | 41.4% |
| DWS Group GmbH KGaA (XTRA:DWS) | €72.80 | €127.26 | 42.8% |
| CombinedX (OM:CX) | SEK39.70 | SEK78.51 | 49.4% |
| Boliden (OM:BOL) | SEK515.20 | SEK1013.28 | 49.2% |
Let's review some notable picks from our screened stocks.
Sulzer (SWX:SUN)
Overview: Sulzer AG develops and sells products and services for fluid engineering and chemical processing applications worldwide, with a market cap of CHF4.90 billion.
Operations: Sulzer's revenue segments include Flow at CHF1.52 billion, Chemtech at CHF662.30 million, and Services at CHF1.30 billion.
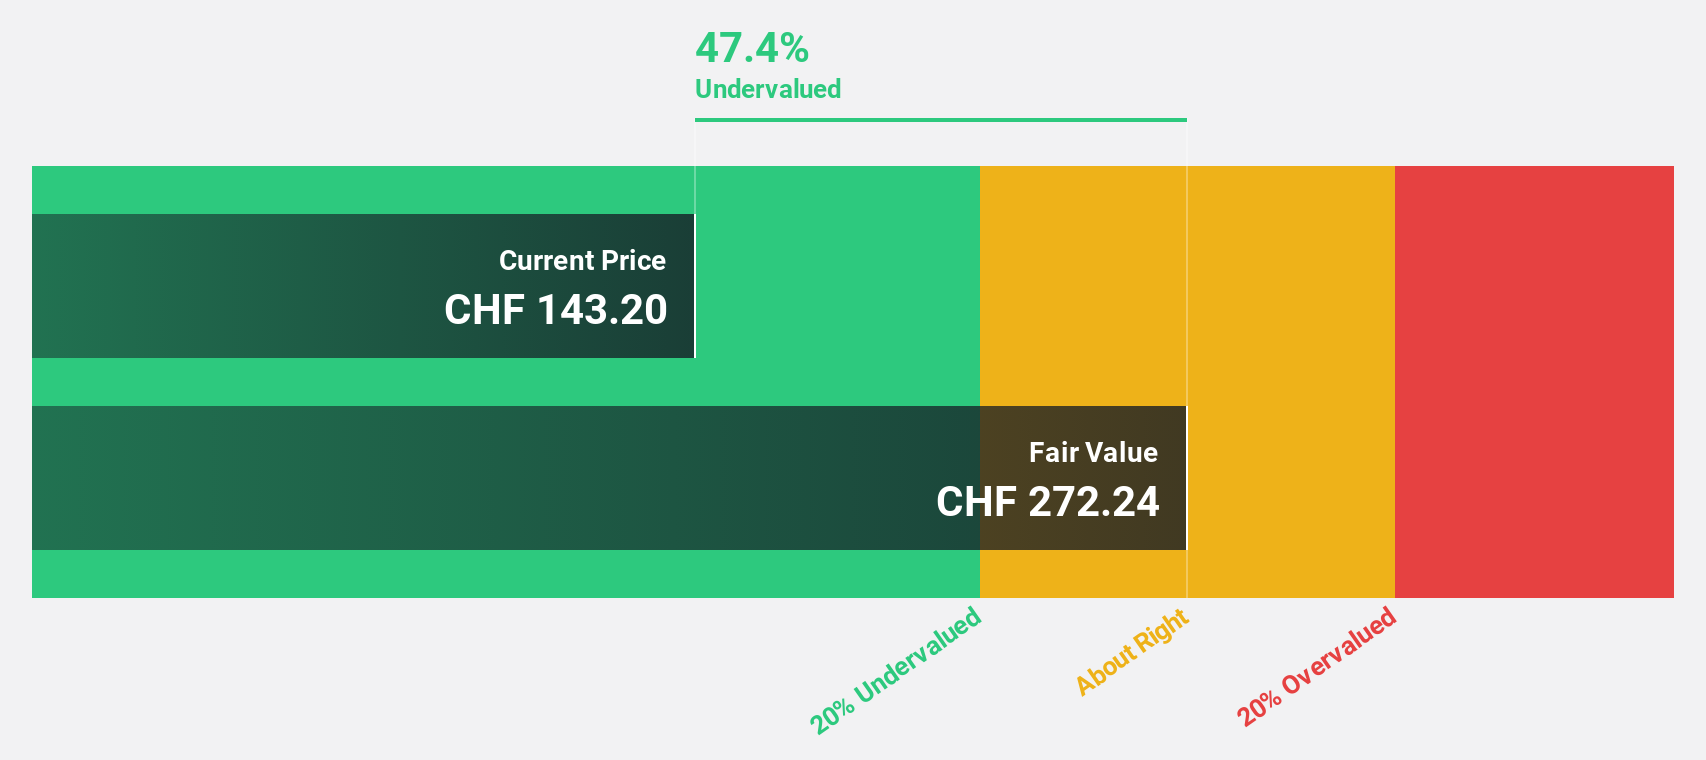
Estimated Discount To Fair Value: 49.8%
Sulzer AG's recent earnings report shows a net income increase to CHF 137.8 million, despite a decline in sales. The company trades at CHF 144.7, significantly below its estimated future cash flow value of CHF 288.01, indicating it is undervalued by more than 20%. While revenue growth is slower than the Swiss market average, Sulzer offers good relative value compared to peers and maintains a reliable dividend yield of 3.28%.
- Upon reviewing our latest growth report, Sulzer's projected financial performance appears quite optimistic.
- Navigate through the intricacies of Sulzer with our comprehensive financial health report here.
Ypsomed Holding (SWX:YPSN)
Overview: Ypsomed Holding AG, along with its subsidiaries, specializes in the development, manufacturing, and sale of injection and infusion systems for self-medication across Switzerland, Europe, North America, and other international markets; it has a market cap of CHF4.69 billion.
Operations: The company's revenue is primarily derived from its Ypsomed Delivery Systems segment, which accounts for CHF601.55 million, and its Ypsomed Diabetes Care segment, contributing CHF75.16 million.
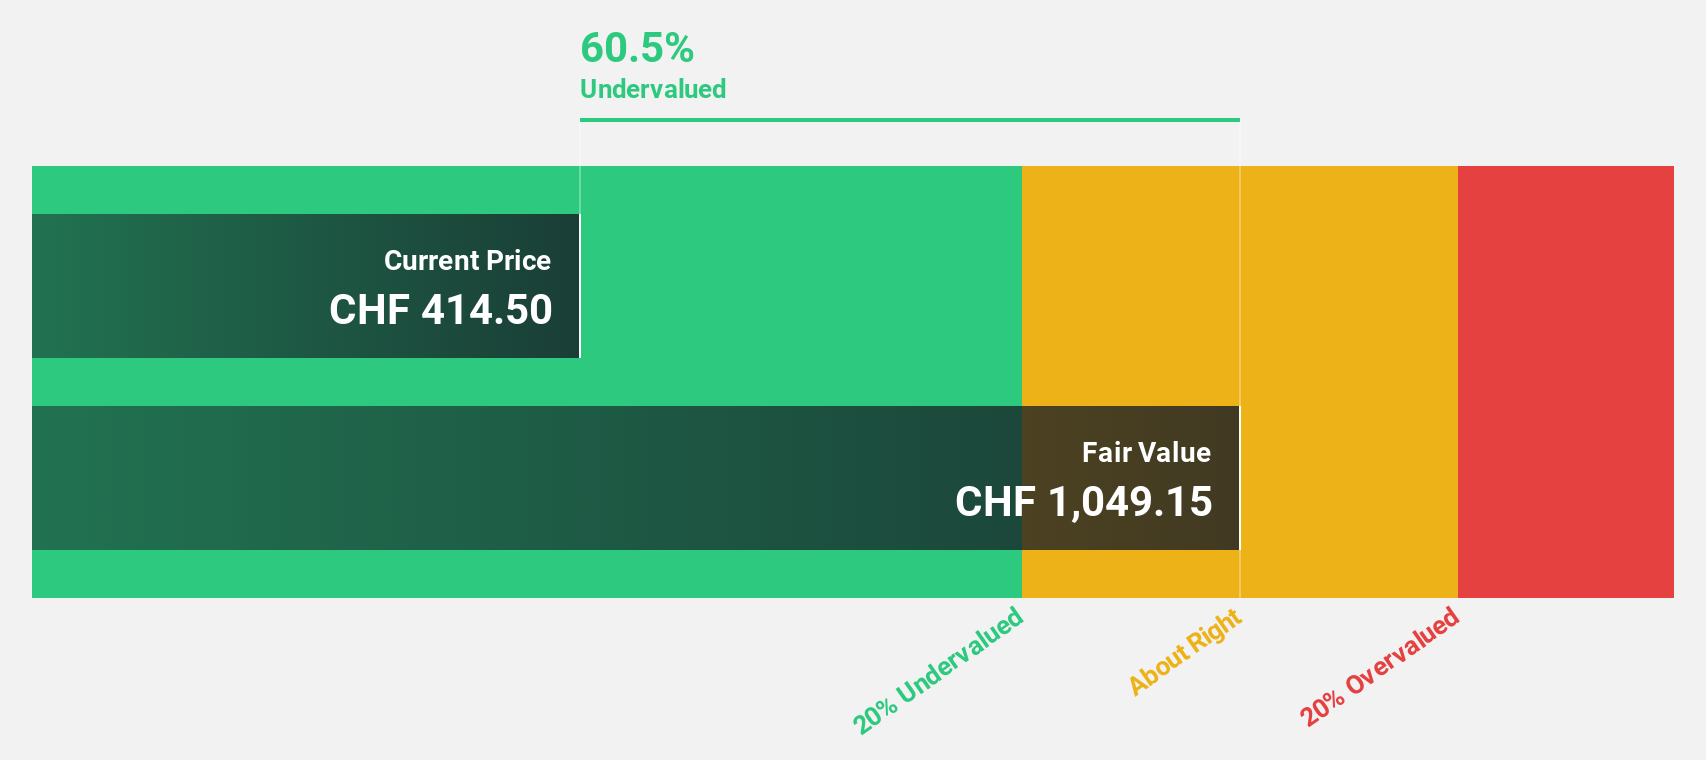
Estimated Discount To Fair Value: 20.8%
Ypsomed Holding is trading at CHF356.8, over 20% below its estimated future cash flow value of CHF450.7, representing an undervaluation based on discounted cash flows. The company forecasts a high return on equity and good relative value compared to peers, although earnings growth is modest at 5.7% annually. Recent expansion into the US with a new facility in North Carolina supports revenue growth prospects and aligns with sustainability objectives, enhancing its strategic position in the healthcare market.
- Our earnings growth report unveils the potential for significant increases in Ypsomed Holding's future results.
- Click here to discover the nuances of Ypsomed Holding with our detailed financial health report.
Voxel (WSE:VOX)
Overview: Voxel S.A. operates in Poland, offering medical services, and has a market cap of PLN1.49 billion.
Operations: Voxel S.A.'s revenue is primarily derived from three segments: Therapy - Neuroradiosurgery (PLN16.13 million), IT & Infrastructure - IT Products and Laboratory Equipment (PLN200.88 million), and Diagnostics - Medical Services and Sales of Radiopharmaceuticals (PLN450.03 million).
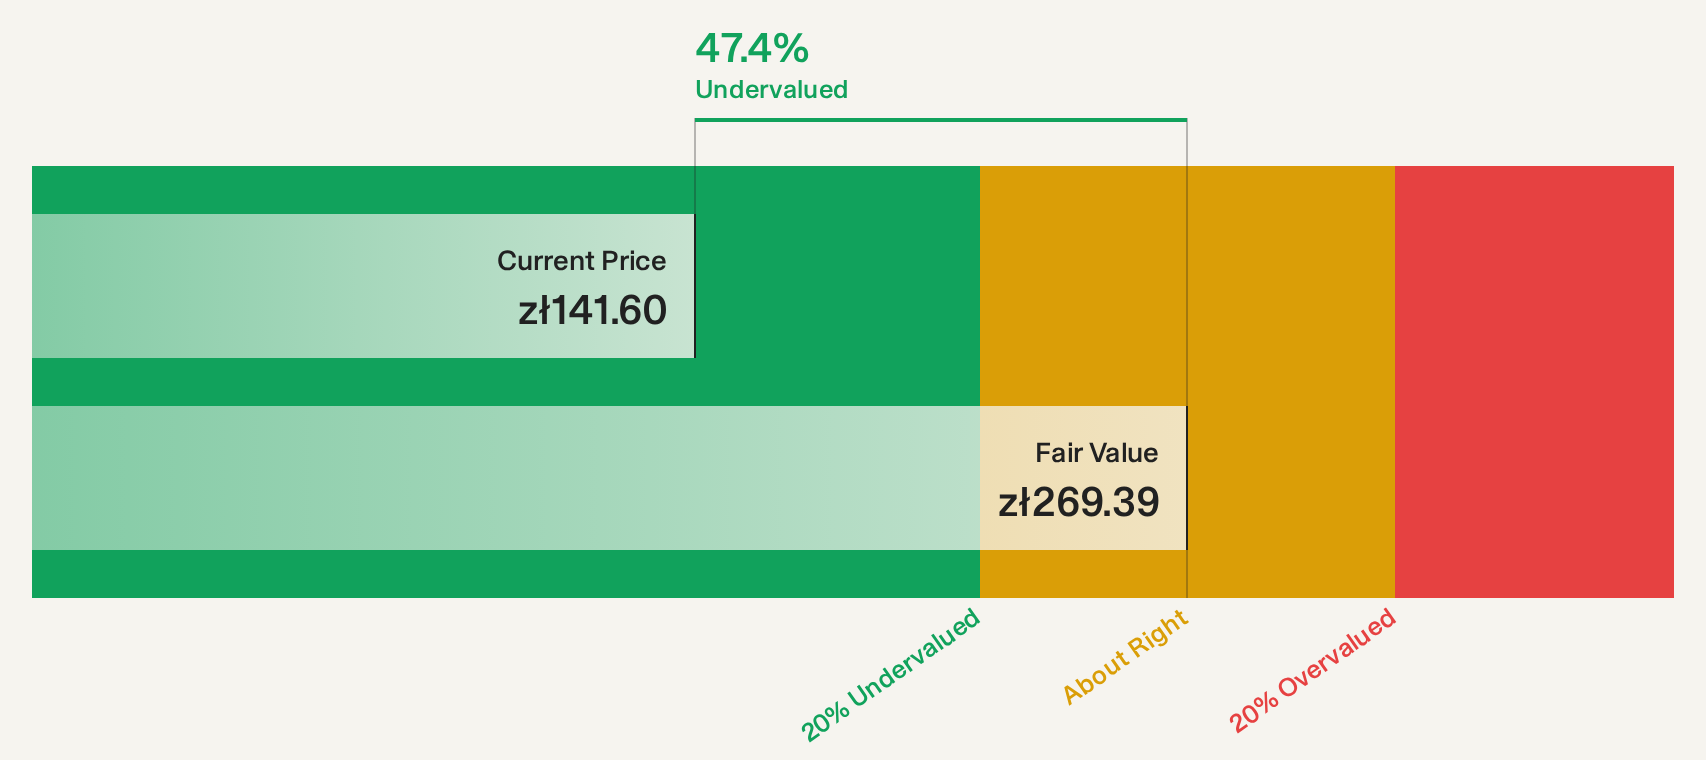
Estimated Discount To Fair Value: 47.4%
Voxel S.A. is trading at PLN141.8, significantly below its estimated future cash flow value of PLN269.39, indicating undervaluation based on discounted cash flows. Despite a 15.9% earnings growth over the past year and good relative value compared to peers, Voxel's forecasted revenue growth of 4.4% per year lags behind the Polish market average of 4.8%, with earnings expected to decline by an average of 0.7% annually over the next three years.
- The analysis detailed in our Voxel growth report hints at robust future financial performance.
- Dive into the specifics of Voxel here with our thorough financial health report.
Make It Happen
- Unlock more gems! Our Undervalued European Stocks Based On Cash Flows screener has unearthed 21 more companies for you to explore.Click here to unveil our expertly curated list of 24 Undervalued European Stocks Based On Cash Flows.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com