
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Snap (SNAP)'s Ad Sales Leadership Change Means For Shareholders
- Snap confirmed that Chief Business Officer Ajit Mohan, who spent nearly four years at the company, chose to leave after notifying the firm on September 3, 2026, with his last day expected on December 31, 2026.
- Snap appointed Ronan Harris as Chief Commercial Officer, placing the architect of its EMEA advertising performance and a former long-time Google executive in charge of global ad sales and go-to-market execution.
- We will look at how Snap's investment narrative is reshaped by Ronan Harris taking charge of global advertising revenue execution.
Scan how Snap's leadership shift compares with other advertising driven platforms by reviewing hand picked 16 high quality undiscovered gems that could be flying under most investors' radar.
Snap Investment Narrative Recap
To own Snap, you need to believe the platform can grow advertising effectiveness faster than costs while gradually turning an engaged audience into a healthier mix of ad and subscription revenue. The short term swing factor is still ad yield and demand. Ronan Harris now owns that problem, so this leadership move looks operationally important.
The biggest near term risk remains persistent losses in a market where Meta, Alphabet and TikTok pressure user time and ad pricing. Snap is still heavily tied to ad budgets with limited diversification, so this executive change only matters if it tightens execution around monetization, not because leadership turnover itself moves fundamentals.
The most relevant recent development is the appointment of Ronan Harris as Chief Commercial Officer. His remit covers global ad sales and go to market delivery, which sits directly on top of Snap's main revenue engine. For a business still unprofitable, that role has real operational weight.
Harris previously managed Snap's EMEA business, where Europe reported several quarters of double digit revenue growth and strong first half 2026 performance. That track record gives investors a tangible reference point. The key question is whether similar playbooks can improve global ad productivity while Snap continues to invest in AR, subscriptions and creator content as future catalysts.
Snap's current analyst narrative points to revenues of US$8.1b and earnings of US$384.0 million by 2029. That outlook assumes 10.0% yearly revenue growth and an earnings swing of roughly US$794.0 million from a loss of US$409.9 million today to the projected profit.
Uncover how Snap's fair value indicates a 26% potential upside to its current price that could narrow quickly.
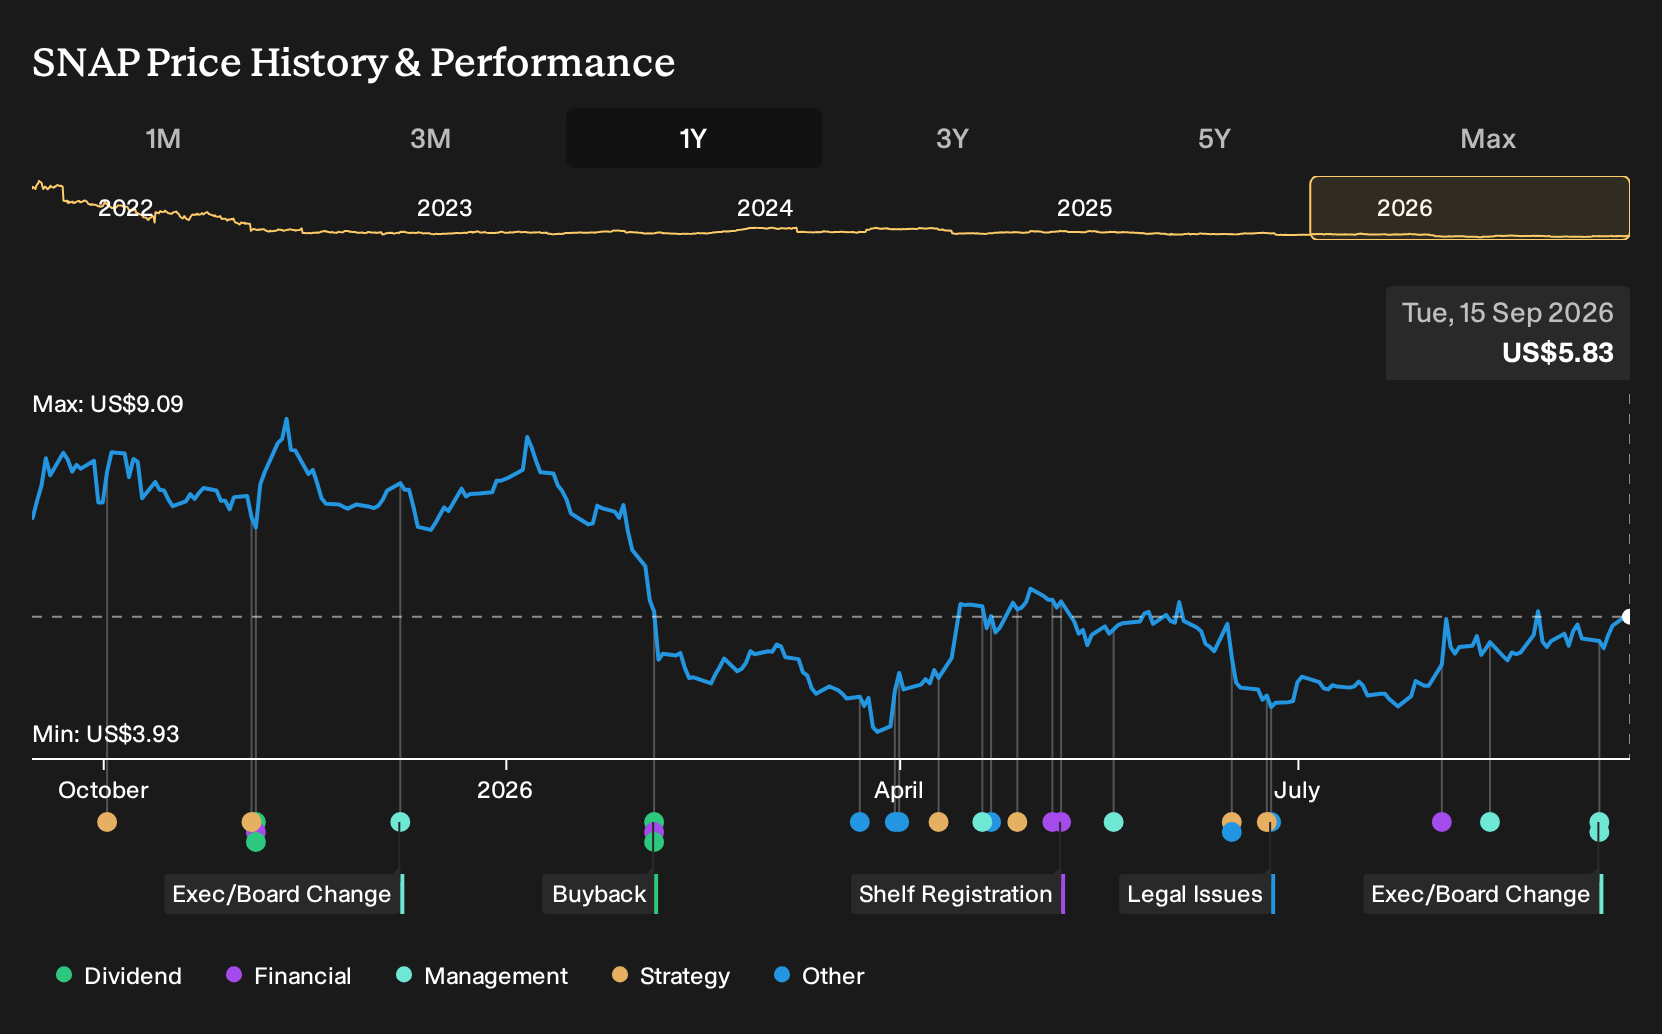
Exploring Other Perspectives
One bullish twist focuses on Snap's AR and Specs plans. The most optimistic analysts were already penciling in about US$9.0b of revenue and US$1.7b of earnings by 2029, far above consensus. It is possible that those forecasts could look either more aggressive or more realistic once Ronan Harris' appointment is reflected in updated models.
Explore 7 other Snap fair value estimates, including one that suggests as much as 176% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Snap research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Snap. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Snap's overall financial health at a glance.
Looking for more investment ideas beyond Snap?
If Snap is only one piece of your watchlist, it can help to scan for other opportunities that fit different roles in your portfolio, from potential growth stories to income payers or steadier balance sheets.
- For investors hunting for underappreciated opportunities with strong fundamentals, scan the 16 high quality undiscovered gems that might not yet be widely followed.
- If you want potential value candidates with quality financials, review the 34 high quality undervalued stocks that blend solid balance sheets with attractive pricing signals.
- For those who care about dependable income streams, check out the 6 dividend fortresses that focus on stocks offering 5%+ yields alongside an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com