
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Record Fan Attendance Will Impact Live Nation (LYV) Stock
- Live Nation Entertainment reported its busiest fan attendance week of the year in the U.S., supported by a new global report showing strong preference for real world experiences and live music.
- The same report highlights that 93% of surveyed fans favor in person experiences over digital ones, underscoring how live music sits at the center of brand partnerships that seek deeper customer loyalty.
- We will now look at how Live Nation Entertainment's investment narrative could be shaped by this surge in demand for live experiences.
Live Nation Entertainment Investment Narrative Recap
To own Live Nation Entertainment, you need to believe live experiences can keep drawing crowds and sponsors even as digital options multiply. The recent record attendance week supports that belief, but the short term swing factor still looks operational. Execution around concerts, ticketing technology and sponsorship yields will likely matter more than one strong week of demand.
The biggest risk remains regulatory and reputational pressure on Ticketmaster. Strong attendance does not change that. Scrutiny on fees, transparency and market power can still affect pricing and contract structures. Expansion into new regions and venues also introduces execution risk if demand or onsite spending does not match investment.
The new global report from Live Nation for Brands is the clearest recent signal tied to this story. It shows 93% of surveyed fans favor real experiences over digital and positions live music as a preferred form of entertainment. That data point aligns with the long term experience economy theme that underpins Live Nation Entertainment’s concert and venue build out.
For investors, the report also matters for sponsorship and advertising. If brands increasingly prioritize live music to reach audiences, that could support higher margin marketing deals on top of ticket and onsite spend. The opportunity sits next to familiar risks, including competition for artist relationships and ongoing ticketing scrutiny that could influence how much value Live Nation captures from each event.
Live Nation Entertainment's analyst narrative points to revenues of US$34.4b and earnings of US$996.6m by 2029, based on an assumed 9.4% yearly increase in revenue and a swing in earnings of roughly US$1.3b from a current loss of US$258.0m.
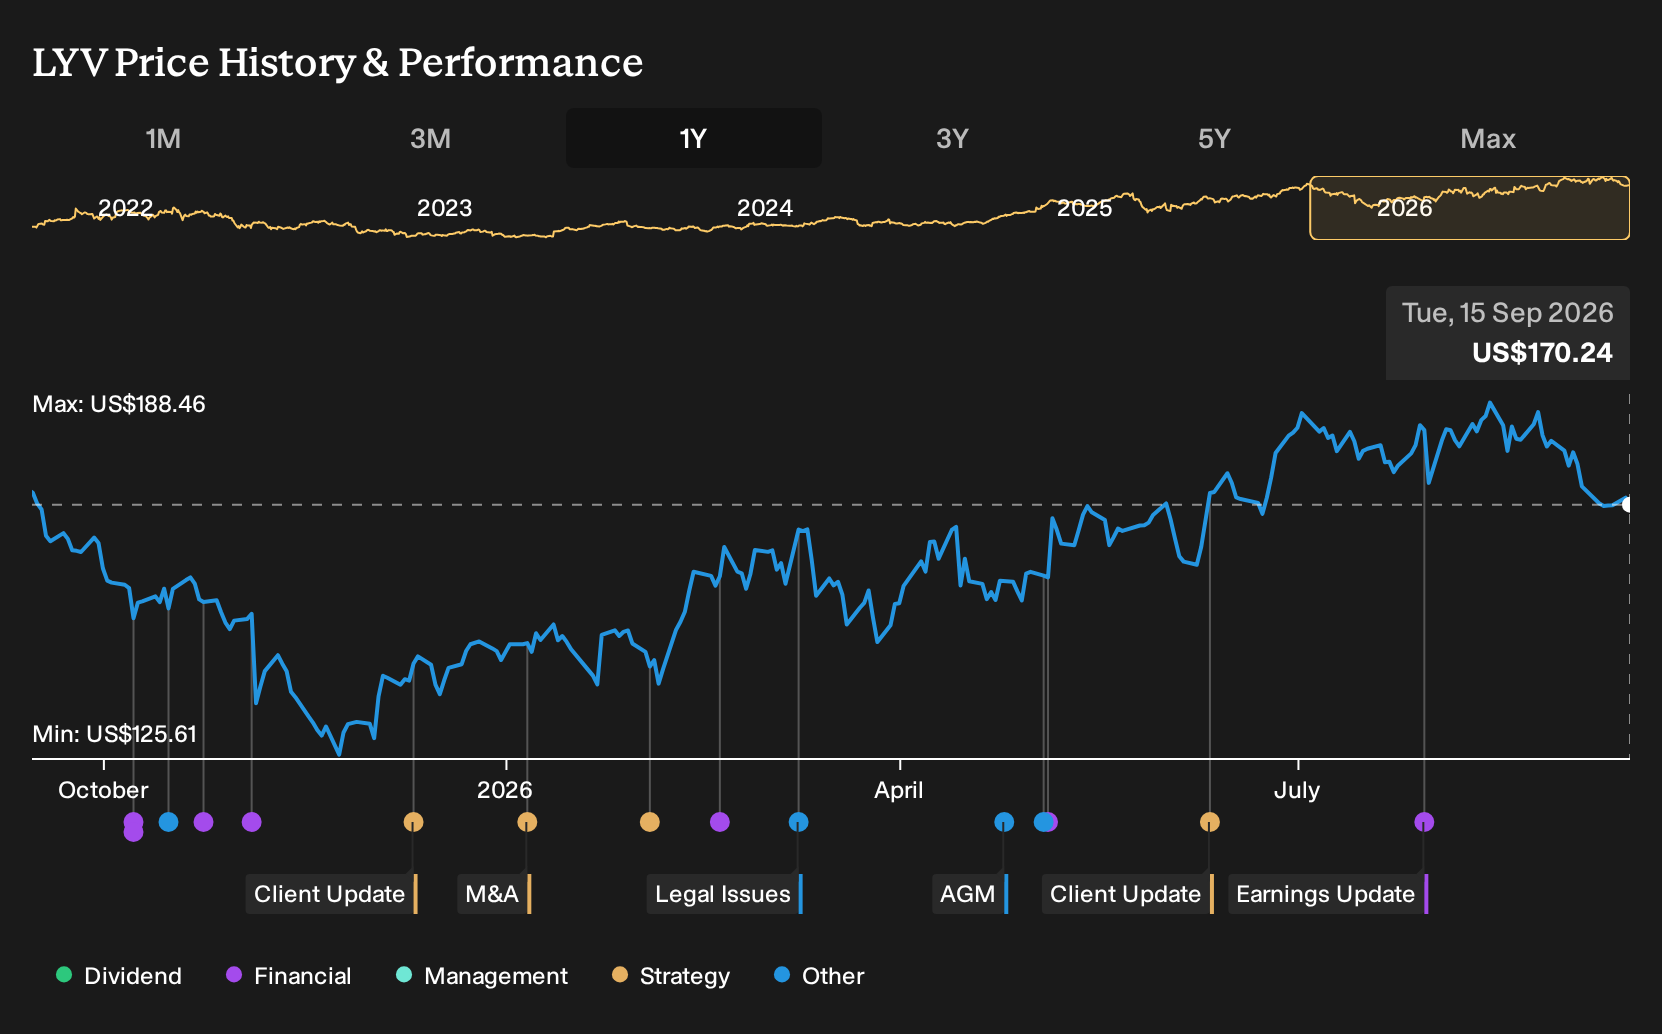
Discover how Live Nation Entertainment's fair value indicates a 19% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community has three fair value estimates for Live Nation Entertainment that cluster between US$175.13 and US$201.96, so retail opinions already span a wide band. Those views sit beside unresolved antitrust and reputational risks around Ticketmaster, which could reshape how much of this experience demand Live Nation ultimately converts into sustainable earnings. Readers should compare several of these community viewpoints before forming a stance.
Explore 2 other Live Nation Entertainment fair value estimates, including one that suggests it could be worth just $175.13.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Live Nation Entertainment research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Live Nation Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Live Nation Entertainment's overall financial health at a glance.
Looking for more investment ideas beyond Live Nation Entertainment?
If Live Nation Entertainment has sparked your interest in experience driven businesses, it can help to line it up against a wider set of opportunities using the Simply Wall St Screener.
- For investors who prioritize value and quality together, scan a focused set of candidates with solid cash flows using our 34 high quality undervalued stocks.
- If capital preservation sits high on your list, filter for businesses with steadier profiles through the 11 resilient stocks with low risk scores.
- For those who care most about financial resilience, run your eye over a list of solid balance sheet and fundamentals (22 results) to see which companies pair durable balance sheets with sound fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com