
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is AI Spending Worries Altering The Investment Case For Coherent Stock (COHR)?
- Recent reports describe Coherent as a premium valued S&P 500 manufacturer of lasers, optical components, and advanced materials that is seeing strong demand tied to AI infrastructure and high performance communications.
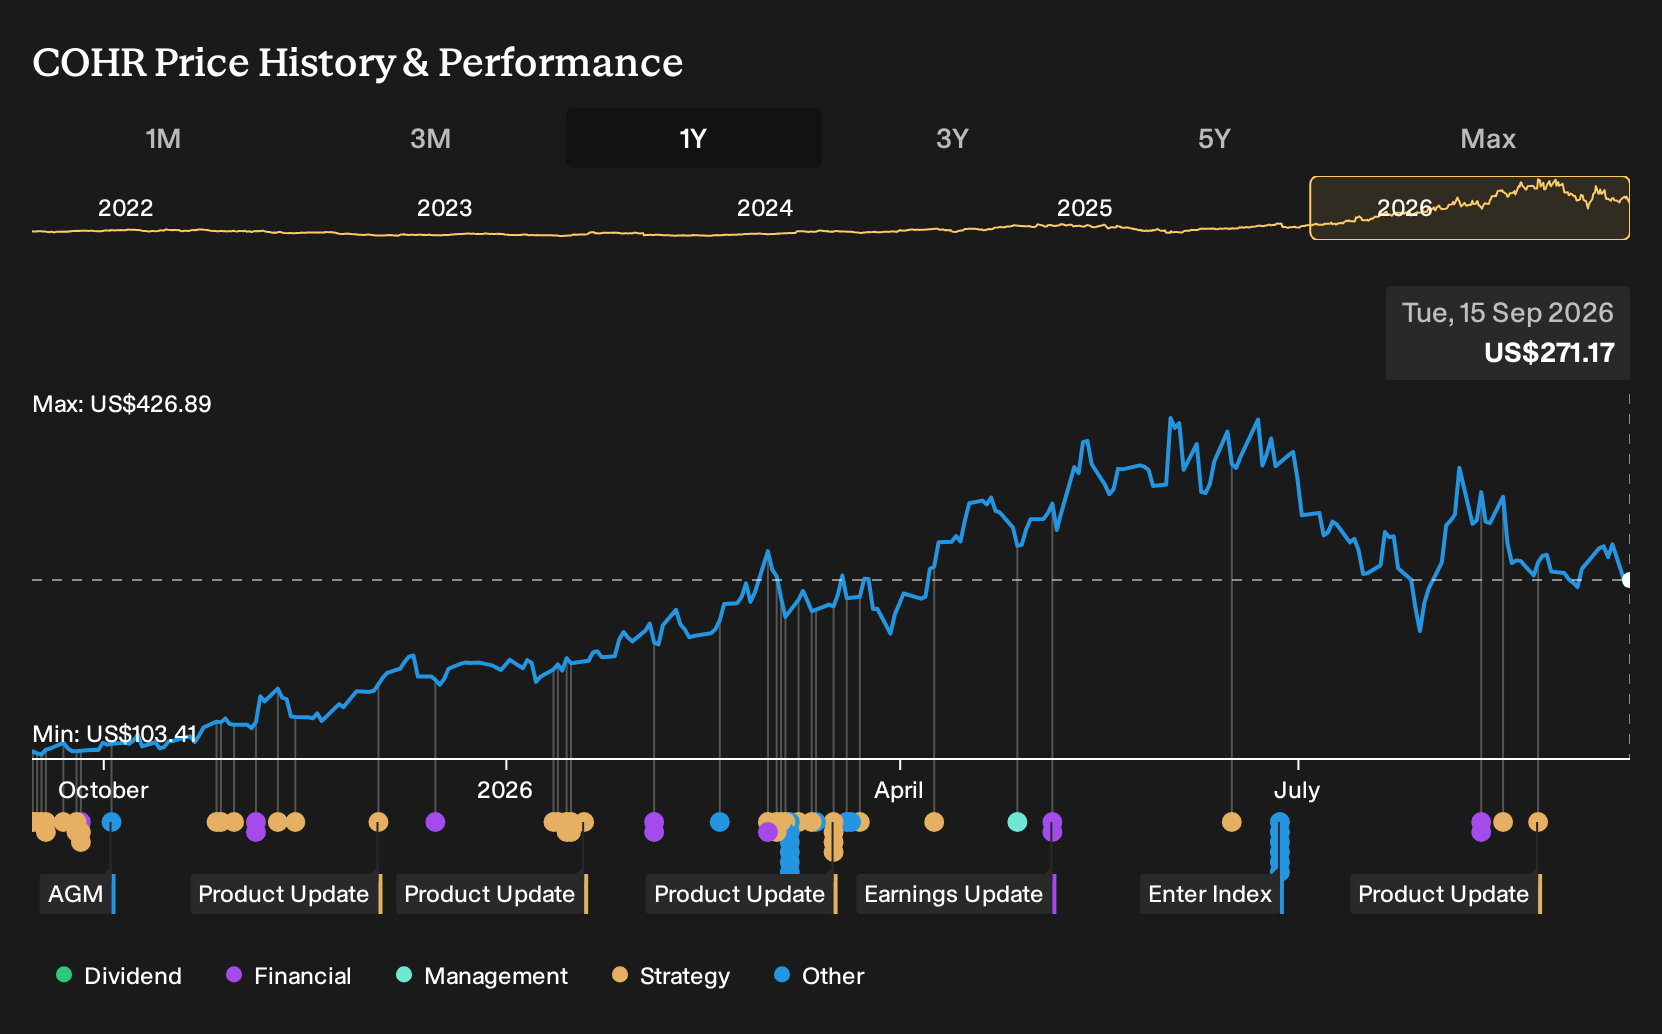
- The same coverage highlights a sharp pullback in Coherent alongside other AI and chip stocks, pointing to macro pressures and AI capex worries rather than an obvious shift in the company’s underlying demand or cost structure.
- The discussion then turns to how this AI driven sector pullback might reshape Coherent’s investment narrative and perceived long term earnings power.
Compare Coherent’s AI driven correction with other potential opportunities by scanning our hand picked 60 AI infrastructure stocks, which is now linked to the buildout of data centers and advanced communications.
Coherent Investment Narrative Recap
To own Coherent, you need to believe that demand for AI data centers, high speed communications, and precision industrial tools will continue to require more of its photonics, lasers, and advanced materials. The sharp pullback and recent 11% drop appear more related to macro concerns and AI spending headlines than to a definitive change in that operating thesis.
The key near term factor is how quickly hyperscalers and carriers turn AI and optical connectivity plans into firm orders and higher volumes. The largest current risk is that customers slow or stagger projects while Coherent is already committing significant capital to indium phosphide and other capacity, which could pressure utilization and margins.
Because recent moves are tied to sector-wide AI concerns rather than a specific new announcement from Coherent, the most relevant data point remains its push into 6 inch indium phosphide manufacturing in Texas. That buildout is directly linked to the AI infrastructure narrative that has recently seen sentiment cool and the stock decline about 24% over the month.
For shareholders, the question is straightforward: can Coherent fill that new capacity with datacom and communications demand quickly enough to support the premium 31.3x forward P/E and the ongoing capital spending. If AI capex or hyperscaler orders fall short of expectations, that same expansion could shift from an earnings catalyst to an execution and balance sheet risk.
Coherent's current earnings of US$769.9 million are set against analyst forecasts that point to revenue of US$19.2b and earnings of US$3.5b by 2029. This assumes yearly revenue growth of 39.2% and an earnings increase of roughly US$2.7b from earnings today.
Uncover why Coherent's fair value indicates a 53% potential upside to its current price before enthusiasm for the discount fades.
Exploring Other Perspectives
One twist in the alternate Coherent story is capacity risk. You might worry that AI data centers overbuild, then slow orders just as new fabs ramp. The most cautious analysts still penciled in about US$18.5b of revenue and US$3.6b of earnings by 2029, yet used a lower P/E and price target. That gap shows how sharply opinions can differ before today’s AI correction and why it is worth exploring several viewpoints that may shift after this pullback.
Explore 4 other Coherent fair value estimates, including one that suggests it could be worth just $415.36!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your Coherent research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Coherent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coherent's overall financial health at a glance.
Looking For More Ideas Beyond Coherent?
Once you have a view on Coherent, it can help to cross-check that thesis against other listed businesses that share similar qualities or offer very different risk profiles.
- If you care most about strong balance sheets and fundamentals, start with a list of solid balance sheet and fundamentals (22 results) that can handle stress without relying heavily on fresh capital.
- If valuation discipline is your priority, filter for companies trading on appealing metrics using a focused 34 high quality undervalued stocks that already screen well on cash generation and financial strength.
- If you prefer to hunt for potential early stage stories before they become widely followed, scan a 16 high quality undiscovered gems that already pass basic quality checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com